Document
FOR IMMEDIATE RELEASE
DATE: July 23, 2026
Heritage Financial Announces Second Quarter 2026 Results and Declares Regular Cash Dividend of $0.25 Per Share
Second Quarter 2026 Highlights
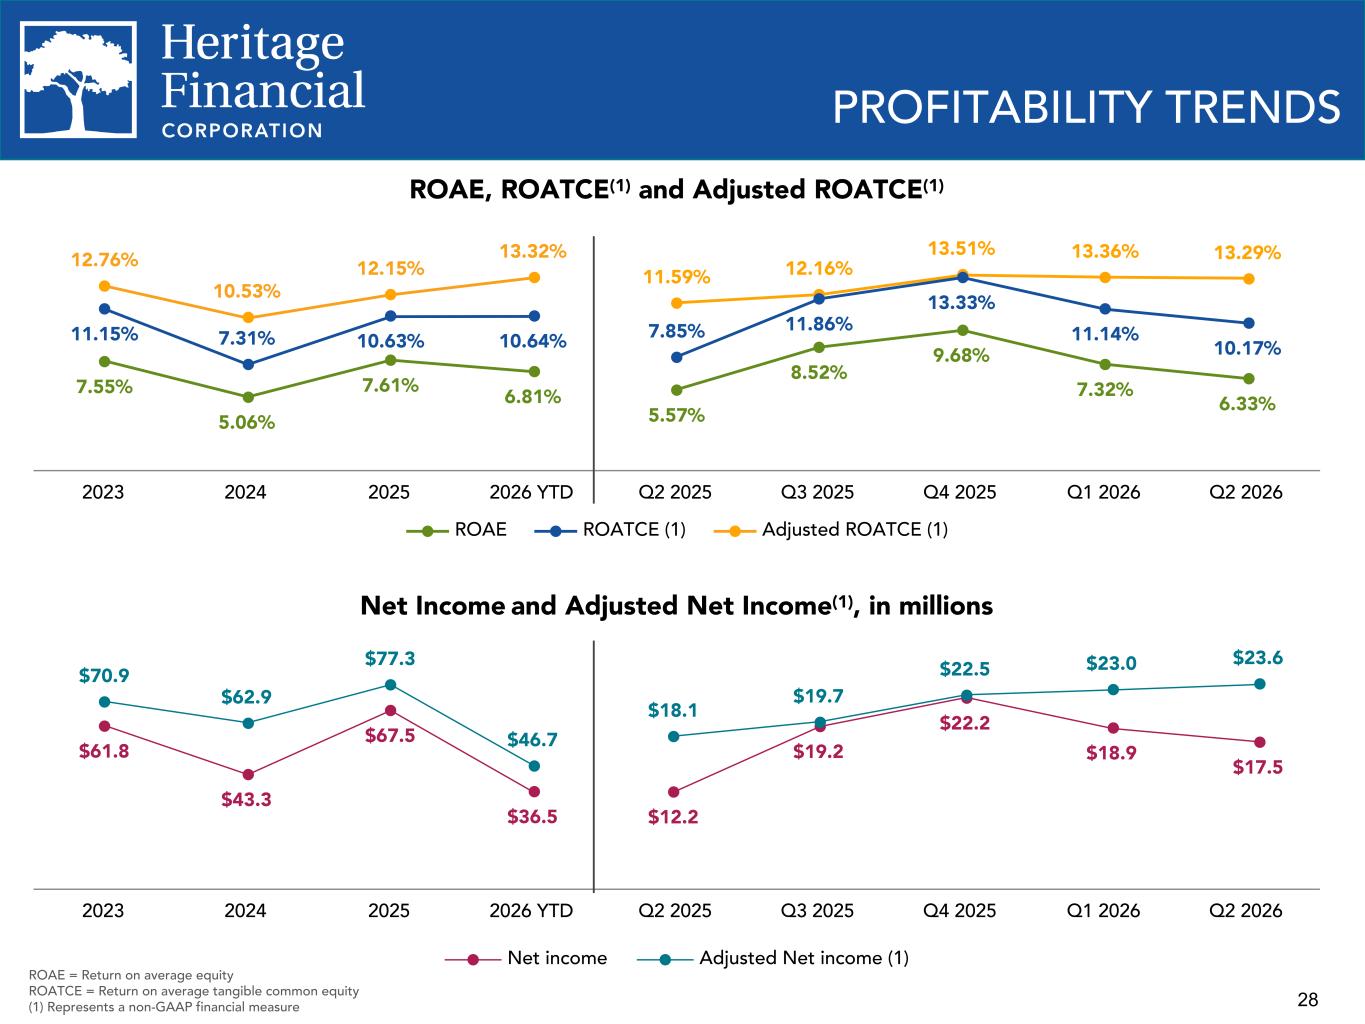
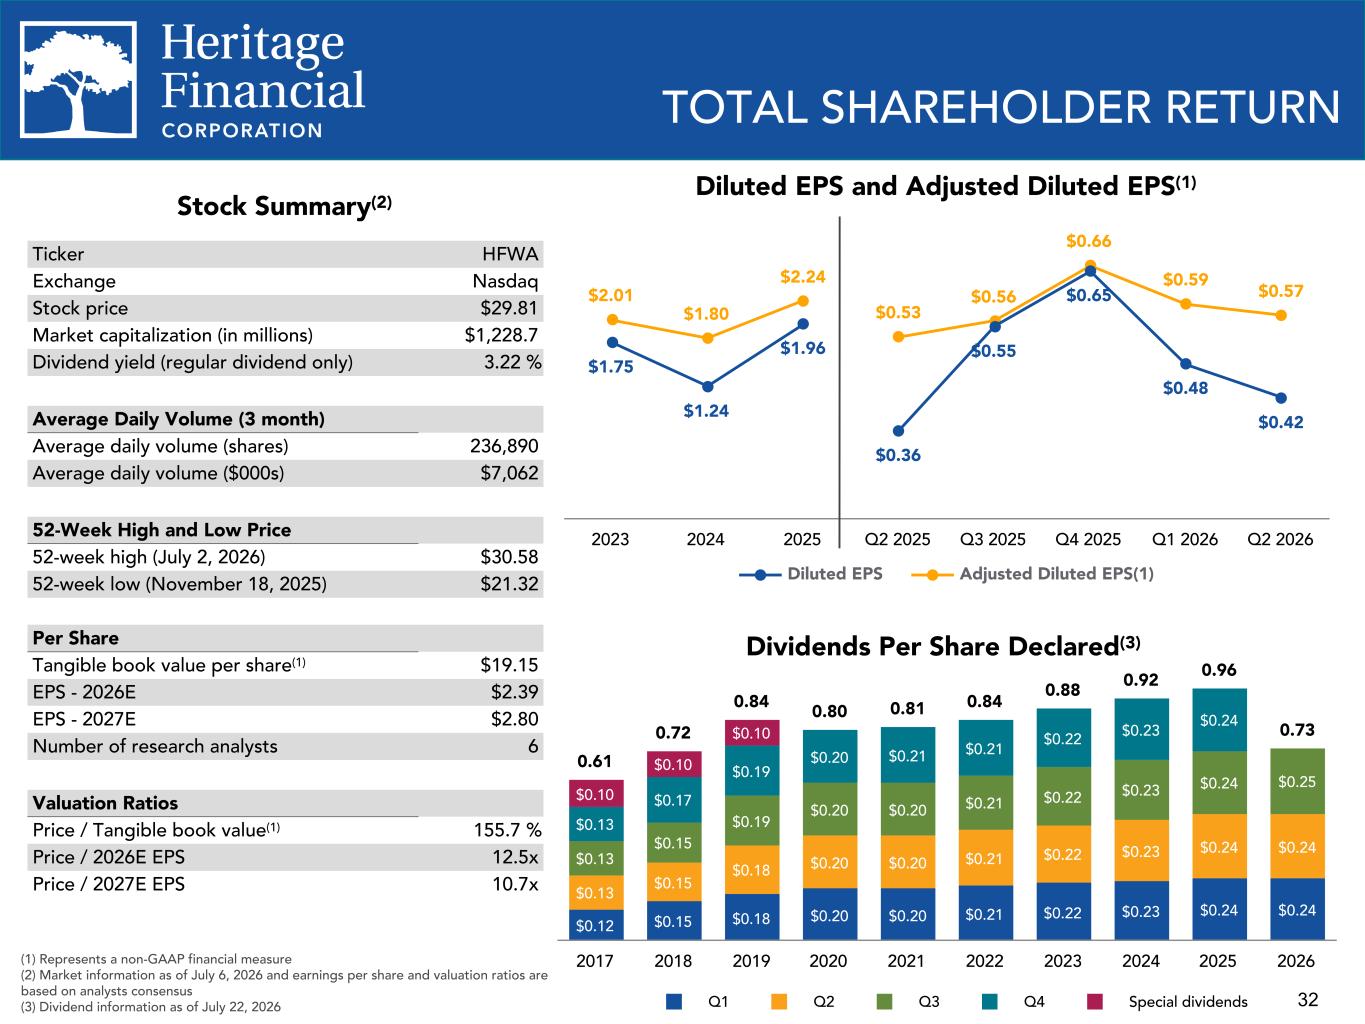
•Net income was $17.5 million, or $0.42 per diluted share, compared to $18.9 million, or $0.48 per diluted share, for the first quarter of 2026.
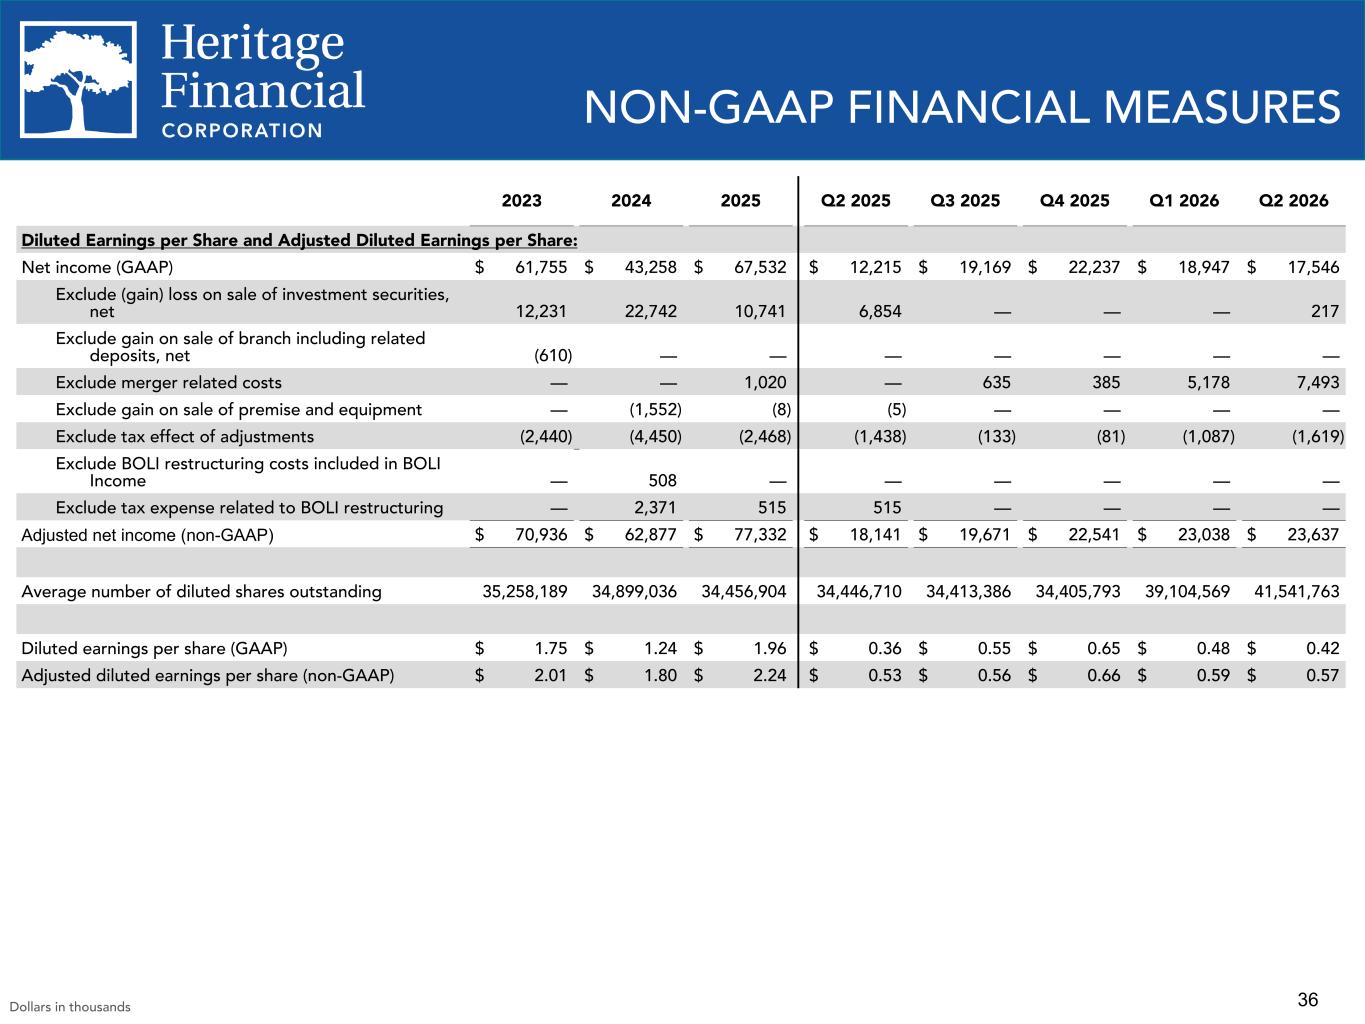
•Adjusted diluted earnings per share (1) was $0.57, compared to $0.59 in the first quarter of 2026.
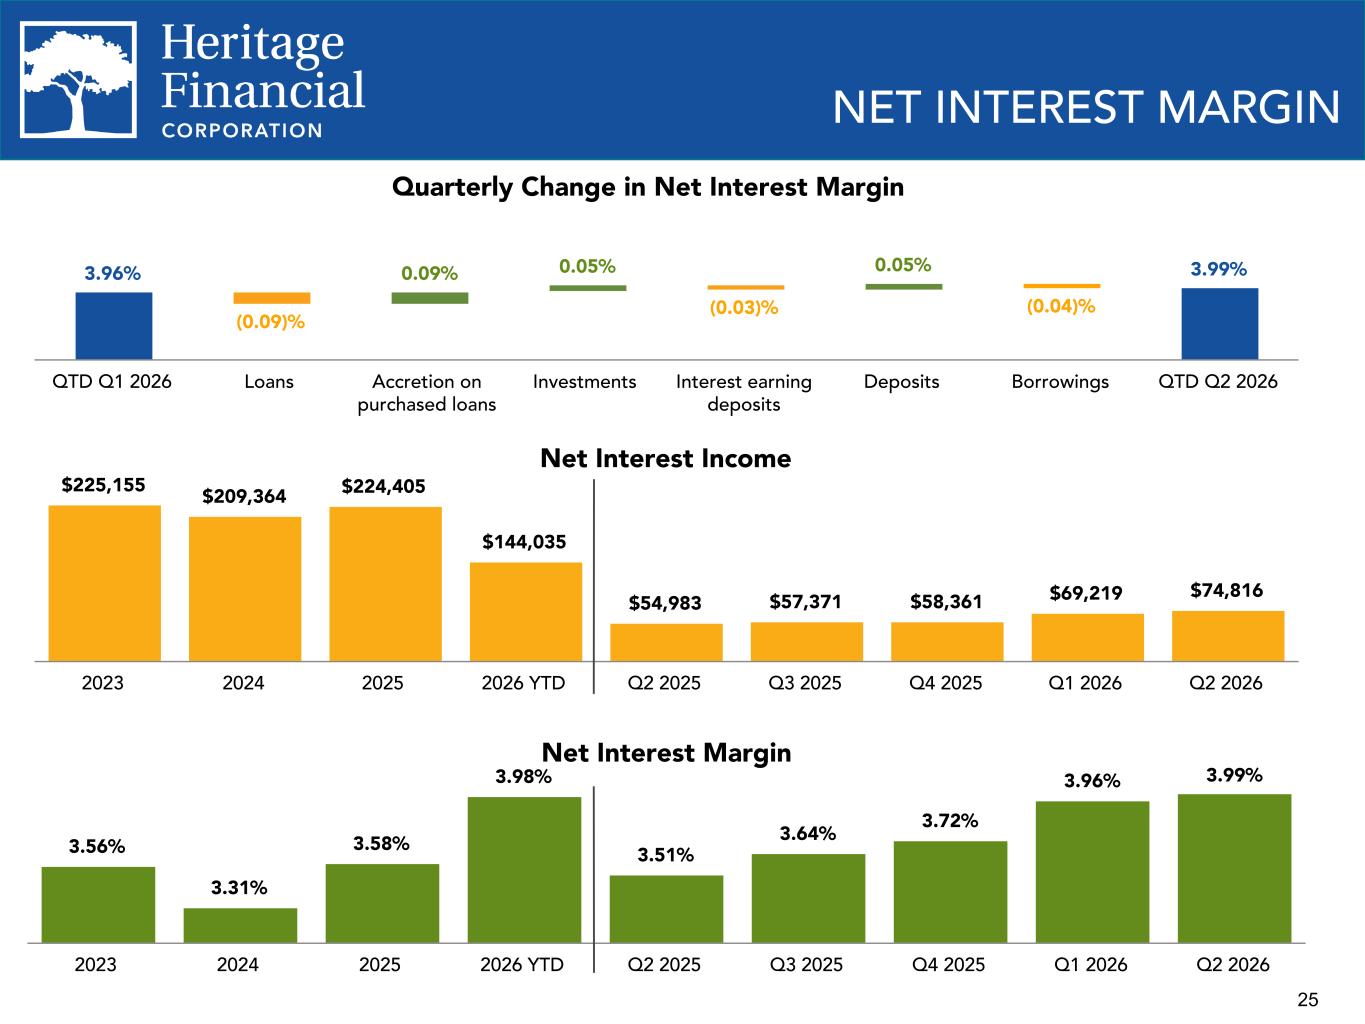
•Net interest margin increased to 3.99%, an increase of 3 basis points from 3.96% for the first quarter of 2026.
•Cost of interest bearing deposits decreased to 1.67%, from 1.71% for the first quarter of 2026.
•Declared a regular cash dividend of $0.25 per share on July 22, 2026, an increase of 4.2% from the $0.24 regular cash dividend per share declared in the second quarter of 2026.
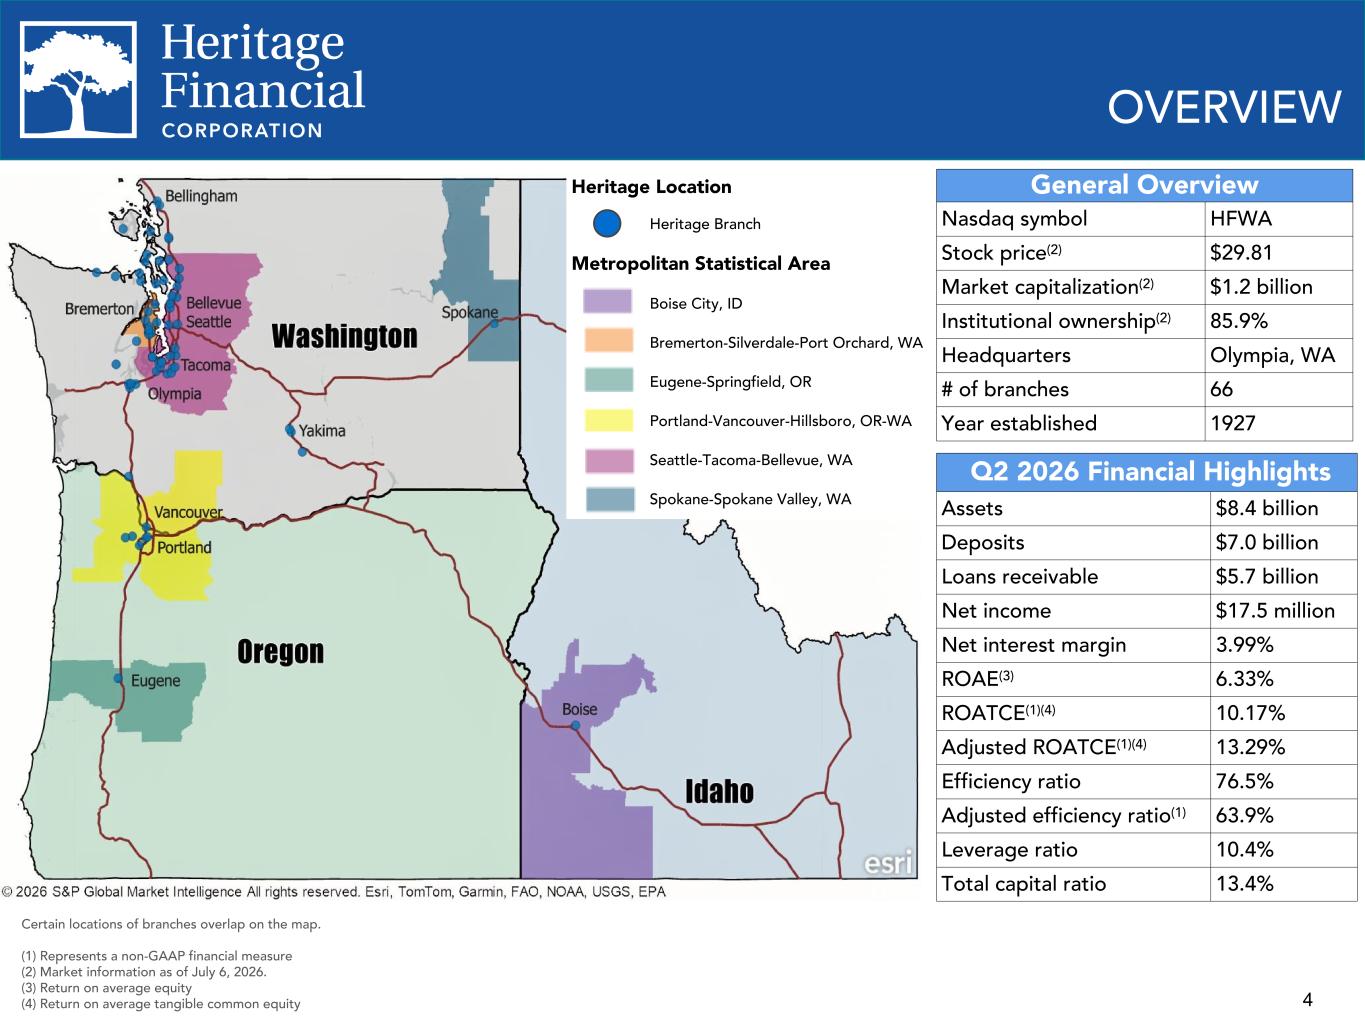
Olympia, WA - Heritage Financial Corporation (Nasdaq GS: HFWA) (the “Company," ”we," or "us"), the parent company of Heritage Bank (the "Bank"), today reported net income of $17.5 million for the second quarter of 2026, compared to $18.9 million for the first quarter of 2026 and $12.2 million for the second quarter of 2025. Diluted earnings per share was $0.42 for the second quarter of 2026, compared to $0.48 for the first quarter of 2026 and $0.36 for the second quarter of 2025. Adjusted diluted earnings per share(1) was $0.57 for the second quarter of 2026, compared to $0.59 for the first quarter of 2026 and $0.53 for the second quarter of 2025.
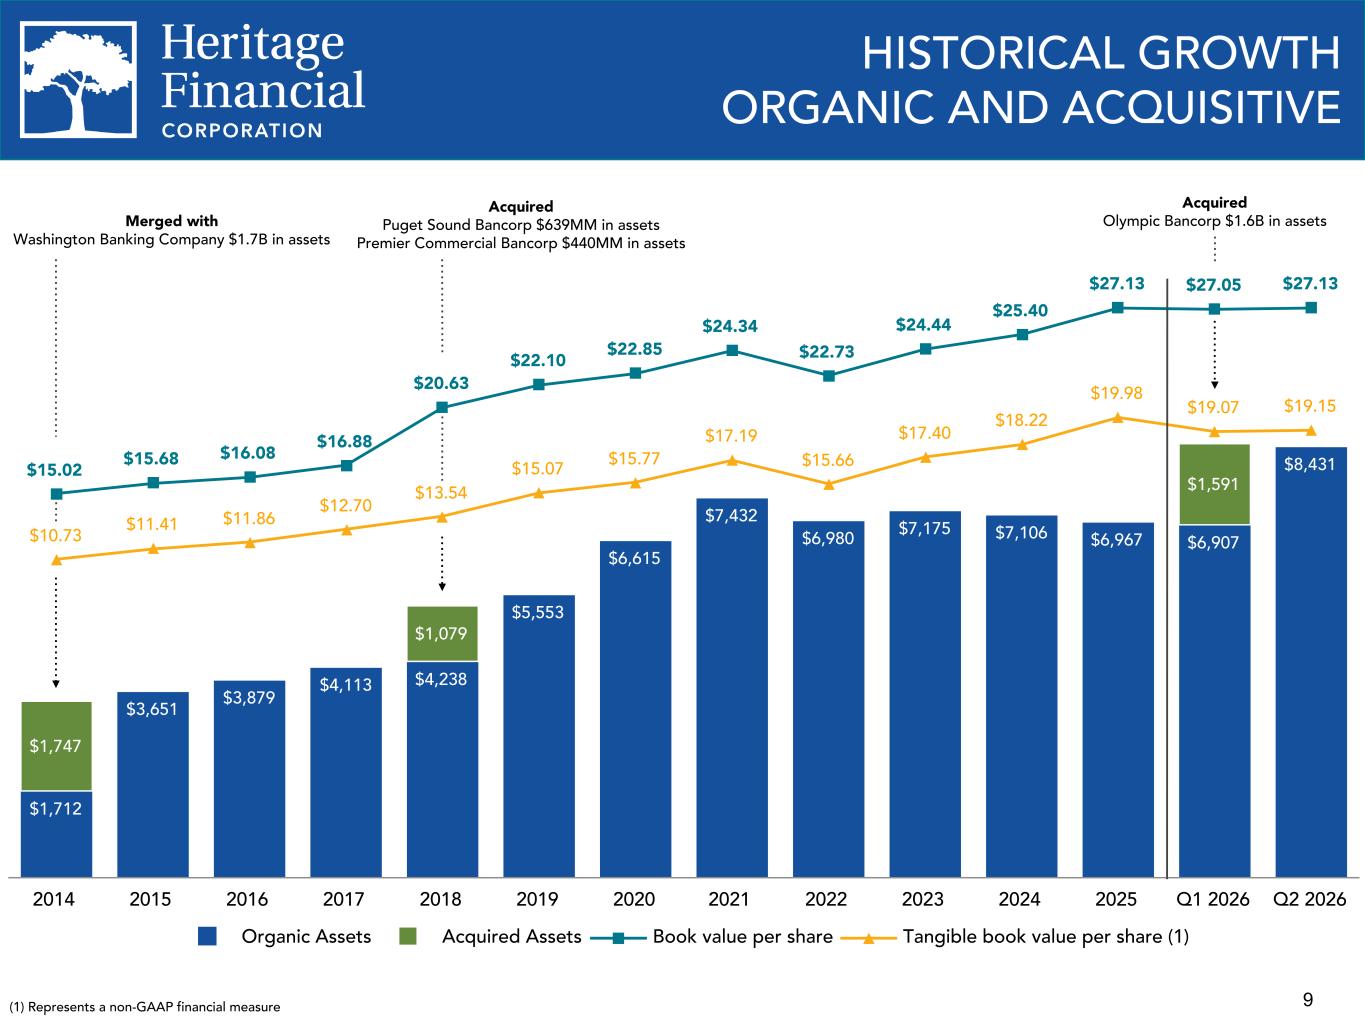
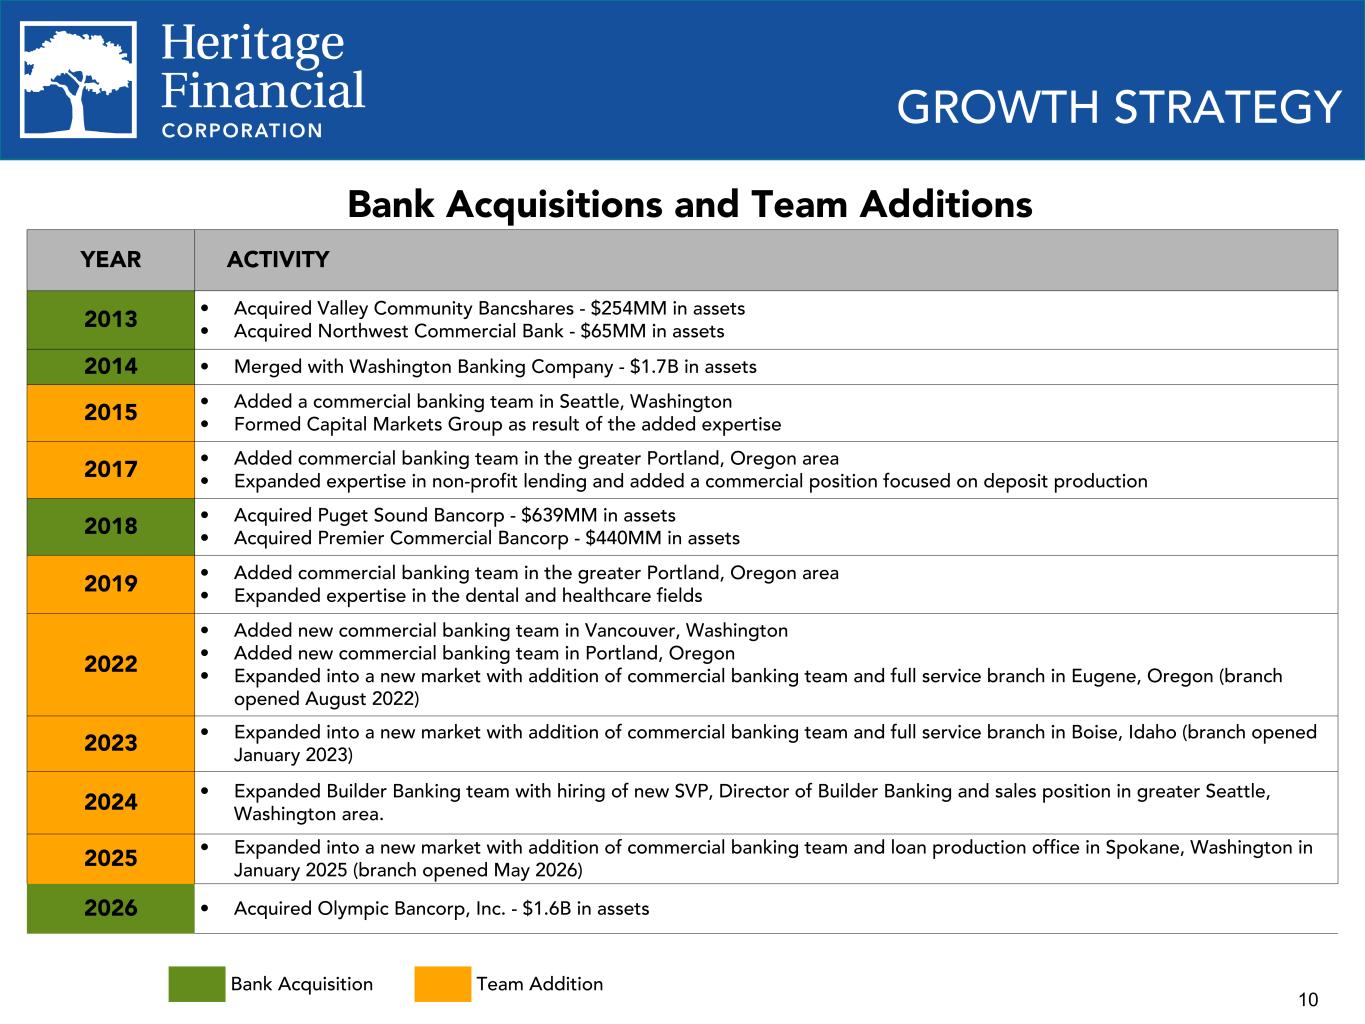
This is the first full quarter of financial results subsequent to the acquisition of Olympic Bancorp, Inc. (the "Merger") which closed on January 31, 2026. The Company recognized merger-related expenses of $7.5 million in the second quarter of 2026, compared to $5.2 million in the first quarter of 2026. After the systems conversion in the third quarter 2026, the Company will recognize additional cost savings.
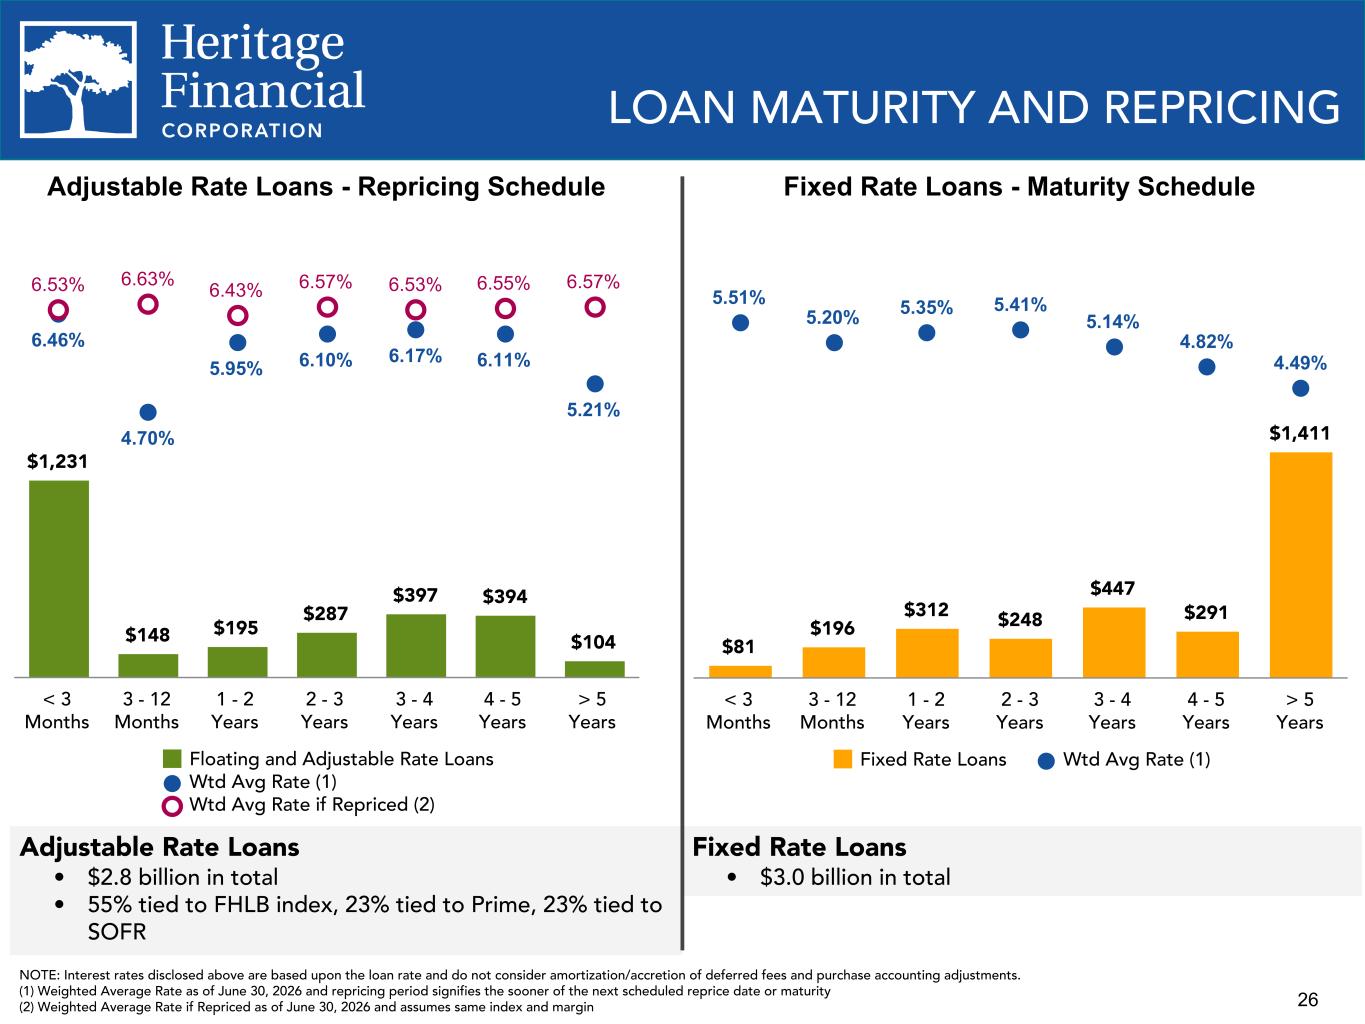
Bryan McDonald, President and Chief Executive Officer of the Company, commented, "We are pleased with the continued improvement in our net interest margin and our strong credit quality metrics. Although loan growth was muted by higher prepayments in the second quarter, we saw strong loan origination and continue to maintain a solid loan pipeline. As our fixed rate loans reprice to higher yields, we expect that our net interest margin will continue to improve. The increase in net interest margin, as well as the expected cost savings from the acquisition, provides optimism for enhanced future earnings.”
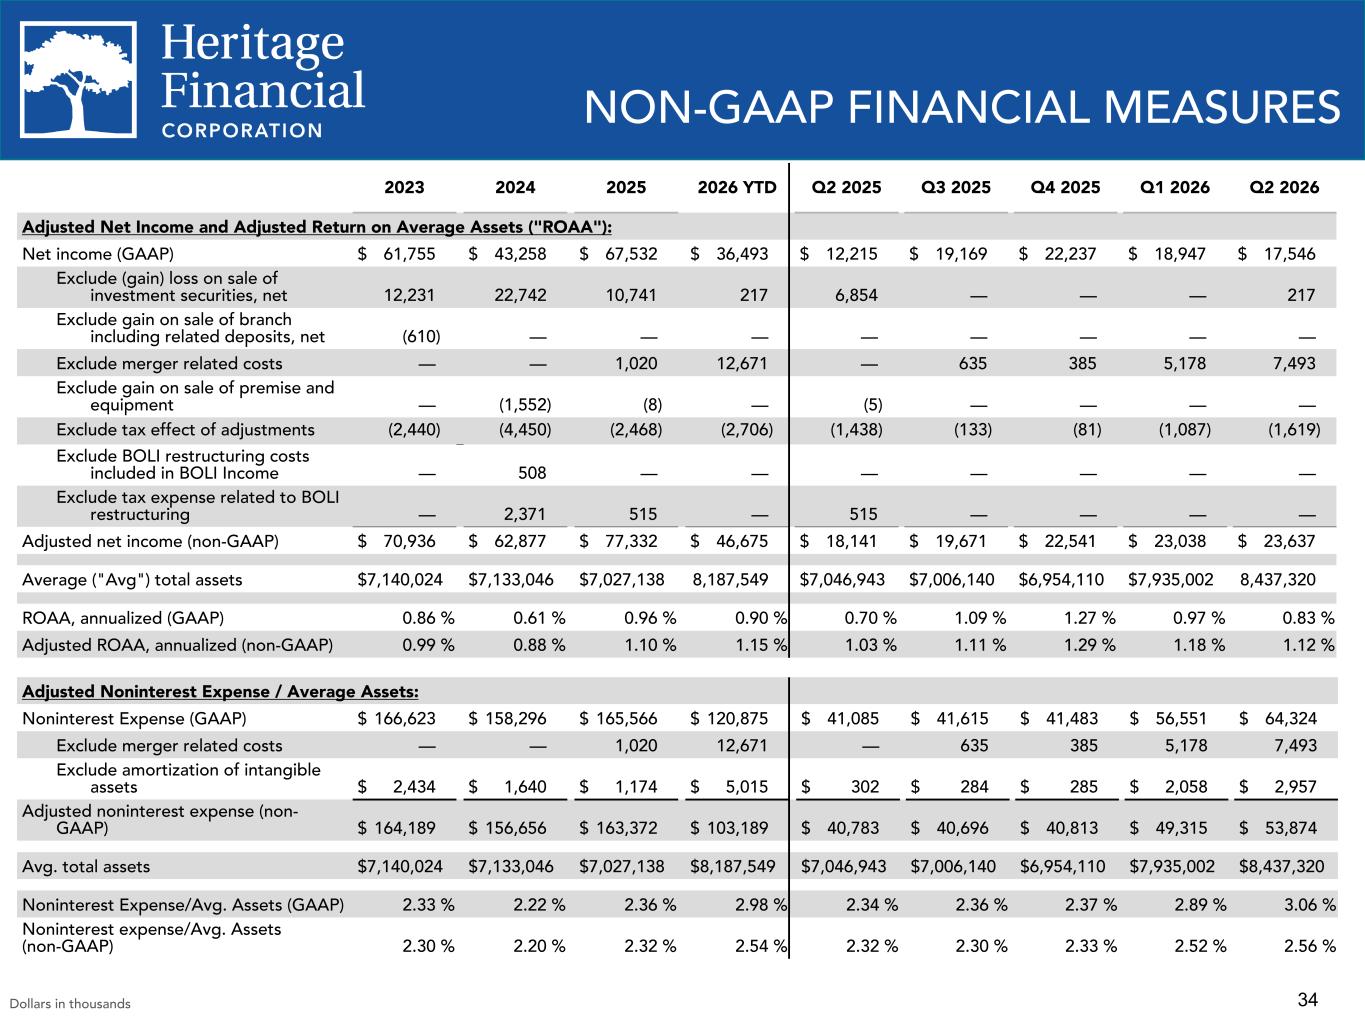
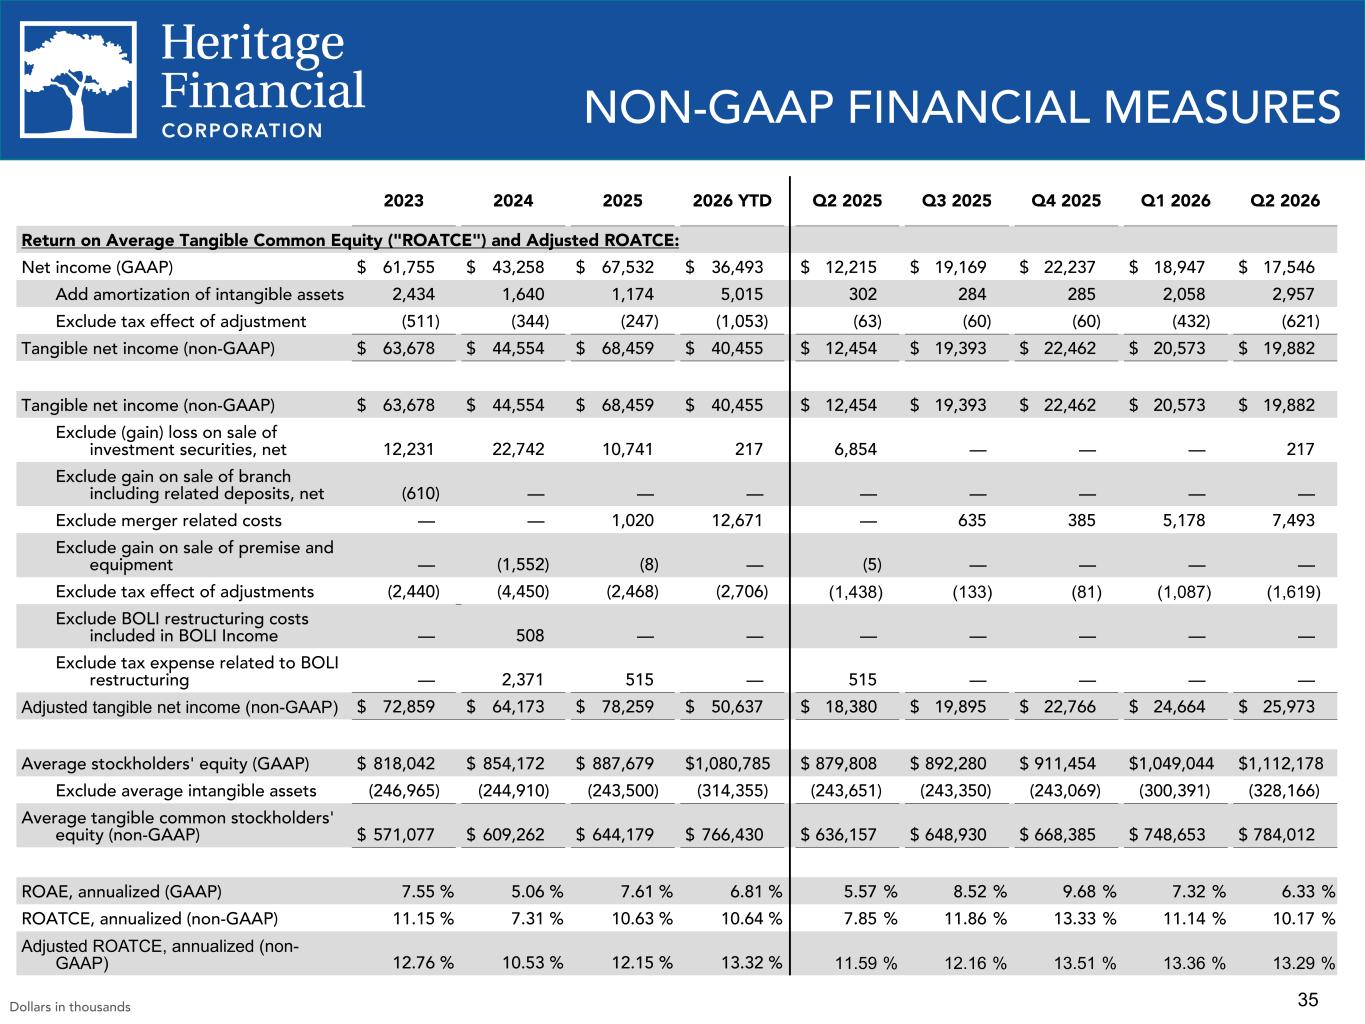
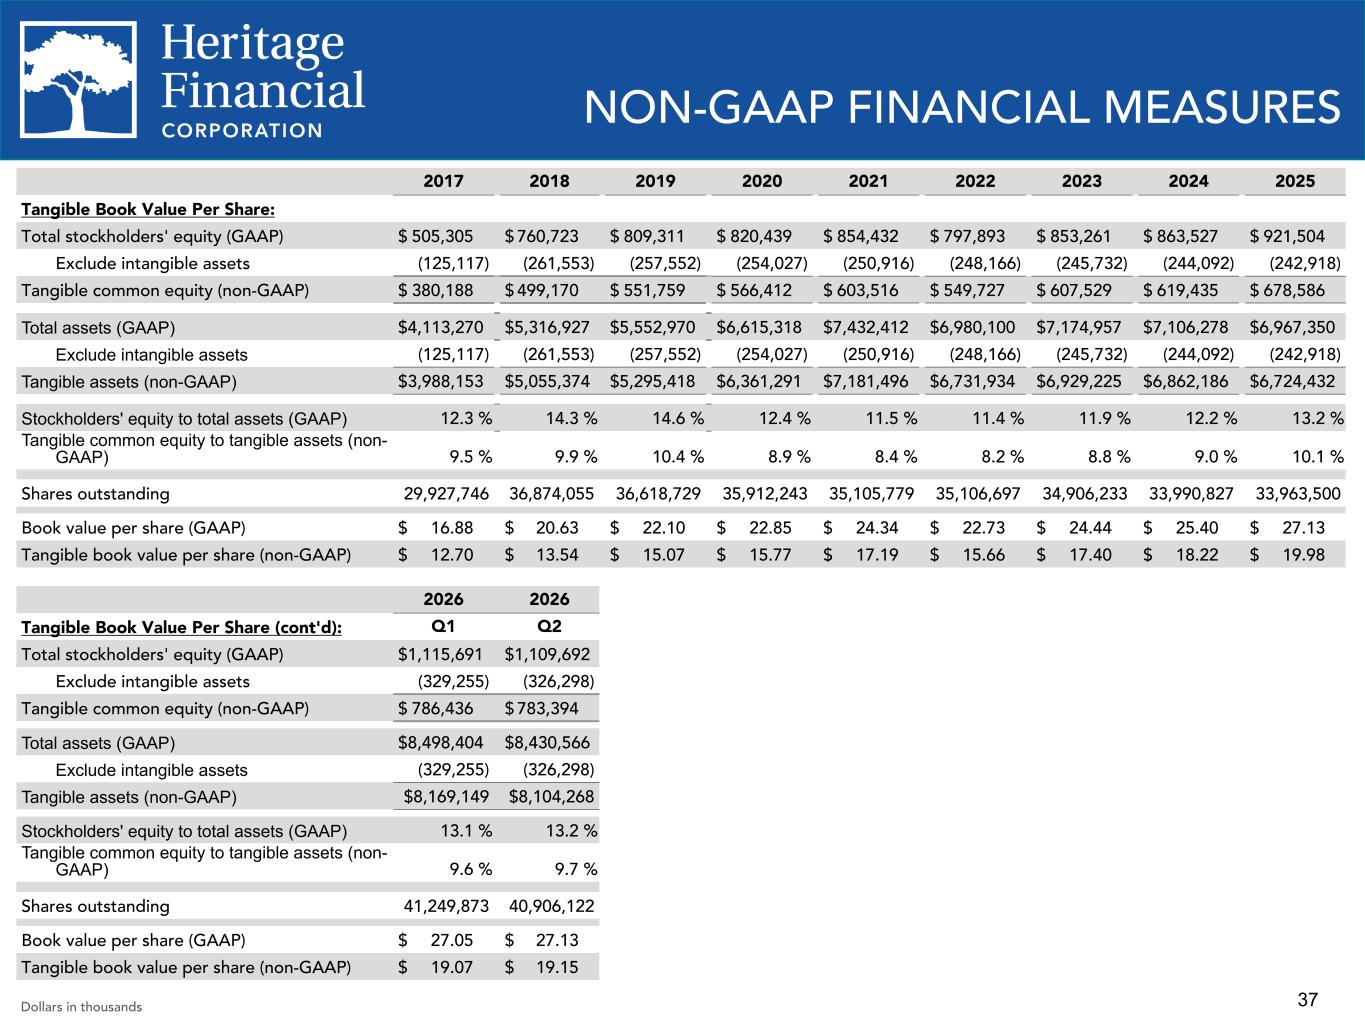
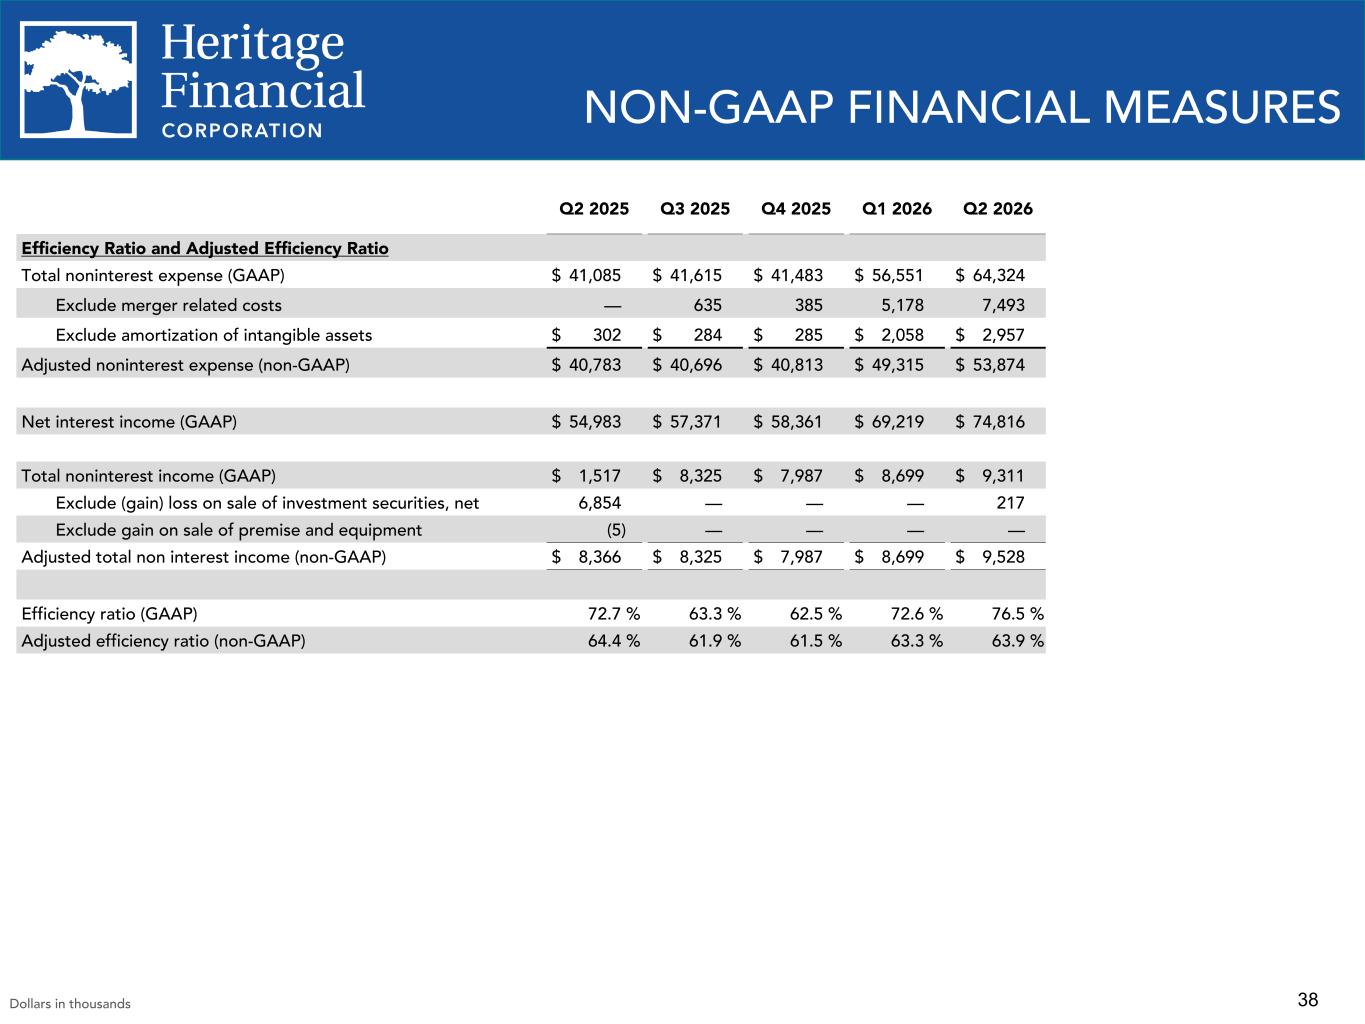
(1) Represents a non-GAAP financial measure. See “Non-GAAP Financial Measures” section for a reconciliation to the comparable GAAP financial measure.
Financial Highlights
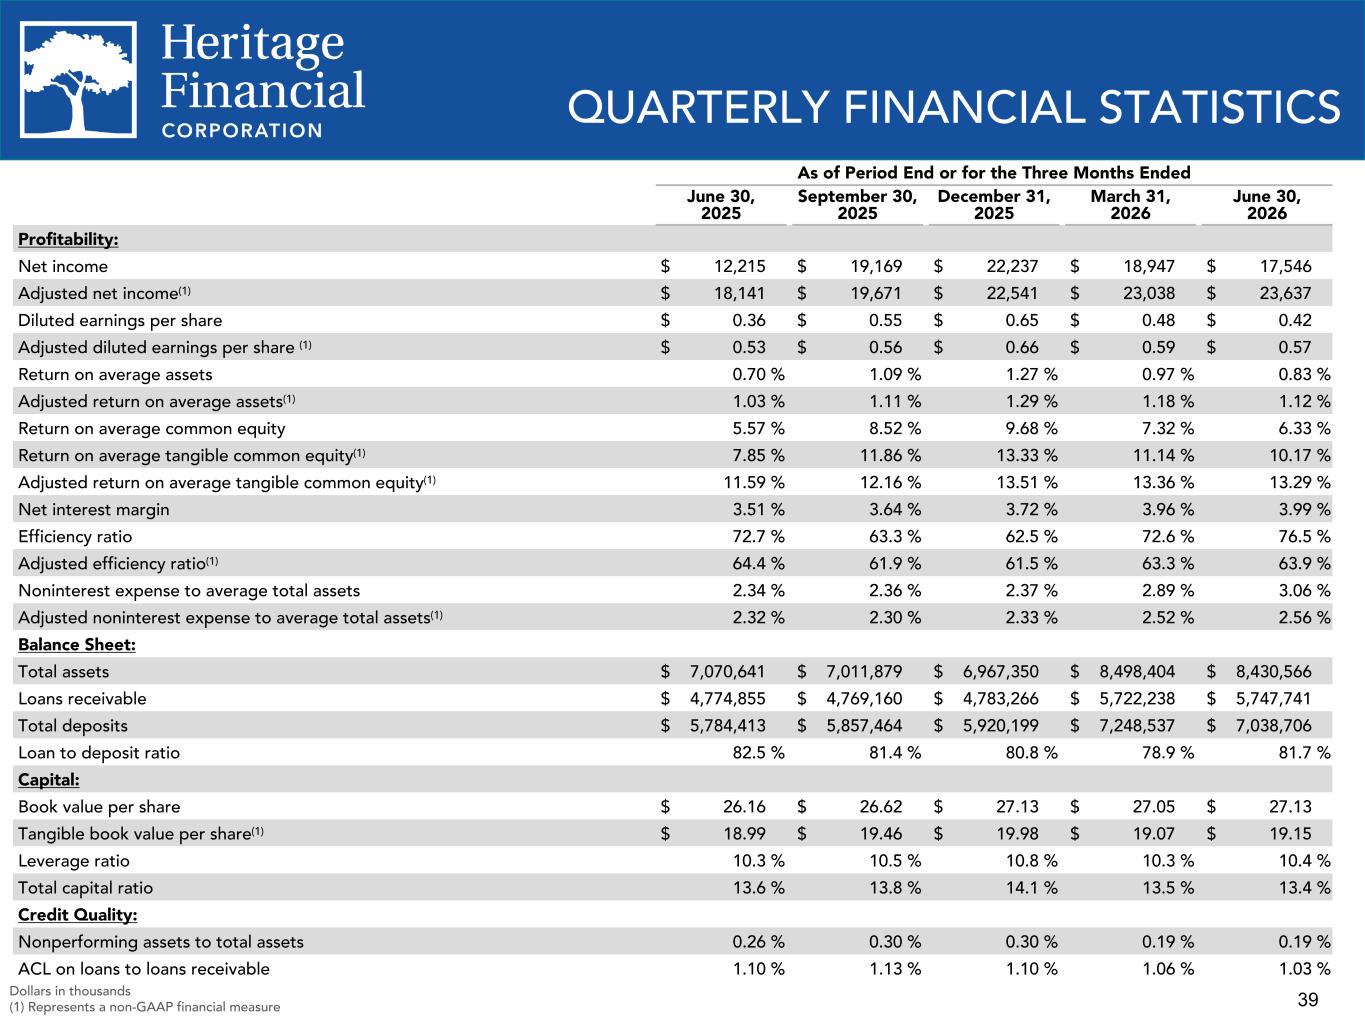
The following table provides financial highlights as of the dates and for the periods indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
As of or for the Quarter Ended |
|
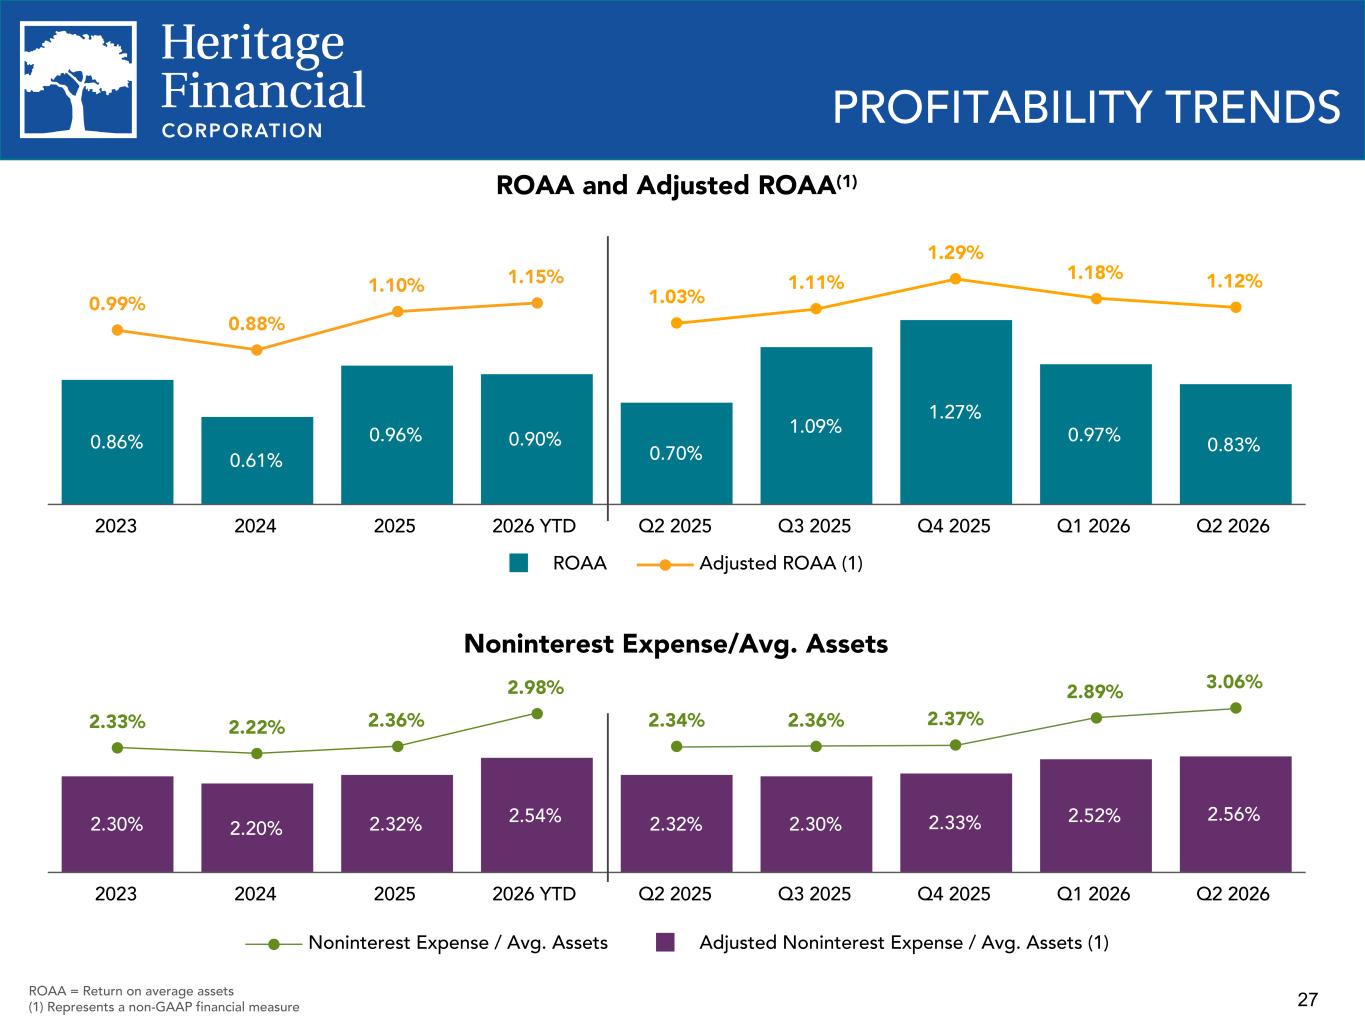
June 30,
2026 |
|
March 31,
2026 |
|
June 30,
2025 |
|
(Dollars in thousands, except per share amounts) |
| Net income |
$ |
17,546 |
|
|
$ |
18,947 |
|
|
$ |
12,215 |
|
| Diluted earnings per share |
0.42 |
|
|
0.48 |
|
|
0.36 |
|
Adjusted diluted earnings per share(1)
|
0.57 |
|
|
0.59 |
|
|
0.53 |
|
Return on average assets(2)
|
0.83 |
% |
|
0.97 |
% |
|
0.70 |
% |
Adjusted return on average assets(1)(2)
|
1.12 |
% |
|
1.18 |
% |
|
1.03 |
% |
Return on average common equity(2)
|
6.33 |
|
|
7.32 |
|
|
5.57 |
|
Return on average tangible common equity(1)(2)
|
10.17 |
|
|
11.14 |
|
|
7.85 |
|
Adjusted return on average tangible common equity(1)(2)
|
13.29 |
|
|
13.36 |
|
|
11.59 |
|
Net interest margin(2)
|
3.99 |
|
|
3.96 |
|
|
3.51 |
|
Cost of total deposits(2)
|
1.21 |
|
|
1.25 |
|
|
1.40 |
|
| Efficiency ratio |
76.5 |
|
|
72.6 |
|
|
72.7 |
|
Adjusted efficiency ratio(1)
|
63.9 |
|
|
63.3 |
|
|
64.4 |
|
Noninterest expense to average total assets(2)
|
3.06 |
|
|
2.89 |
|
|
2.34 |
|
Adjusted noninterest expense to average total assets(1)(2)
|
2.56 |
|
|
2.52 |
|
|
2.32 |
|
| Total assets |
$ |
8,430,566 |
|
|
$ |
8,498,404 |
|
|
$ |
7,070,641 |
|
Loans receivable |
5,747,741 |
|
|
5,722,238 |
|
|
4,774,855 |
|
| Total deposits |
7,038,706 |
|
|
7,248,537 |
|
|
5,784,413 |
|
Loan to deposit ratio(3)
|
81.7 |
% |
|
78.9 |
% |
|
82.5 |
% |
| Book value per share |
$ |
27.13 |
|
|
$ |
27.05 |
|
|
$ |
26.16 |
|
Tangible book value per share(1)
|
19.15 |
|
|
19.07 |
|
|
18.99 |
|
(1) Represents a non-GAAP financial measure. See “Non-GAAP Financial Measures” section for a reconciliation to the comparable GAAP financial measure.
(2) Annualized.
(3) Loans receivable divided by total deposits.
Investment Securities
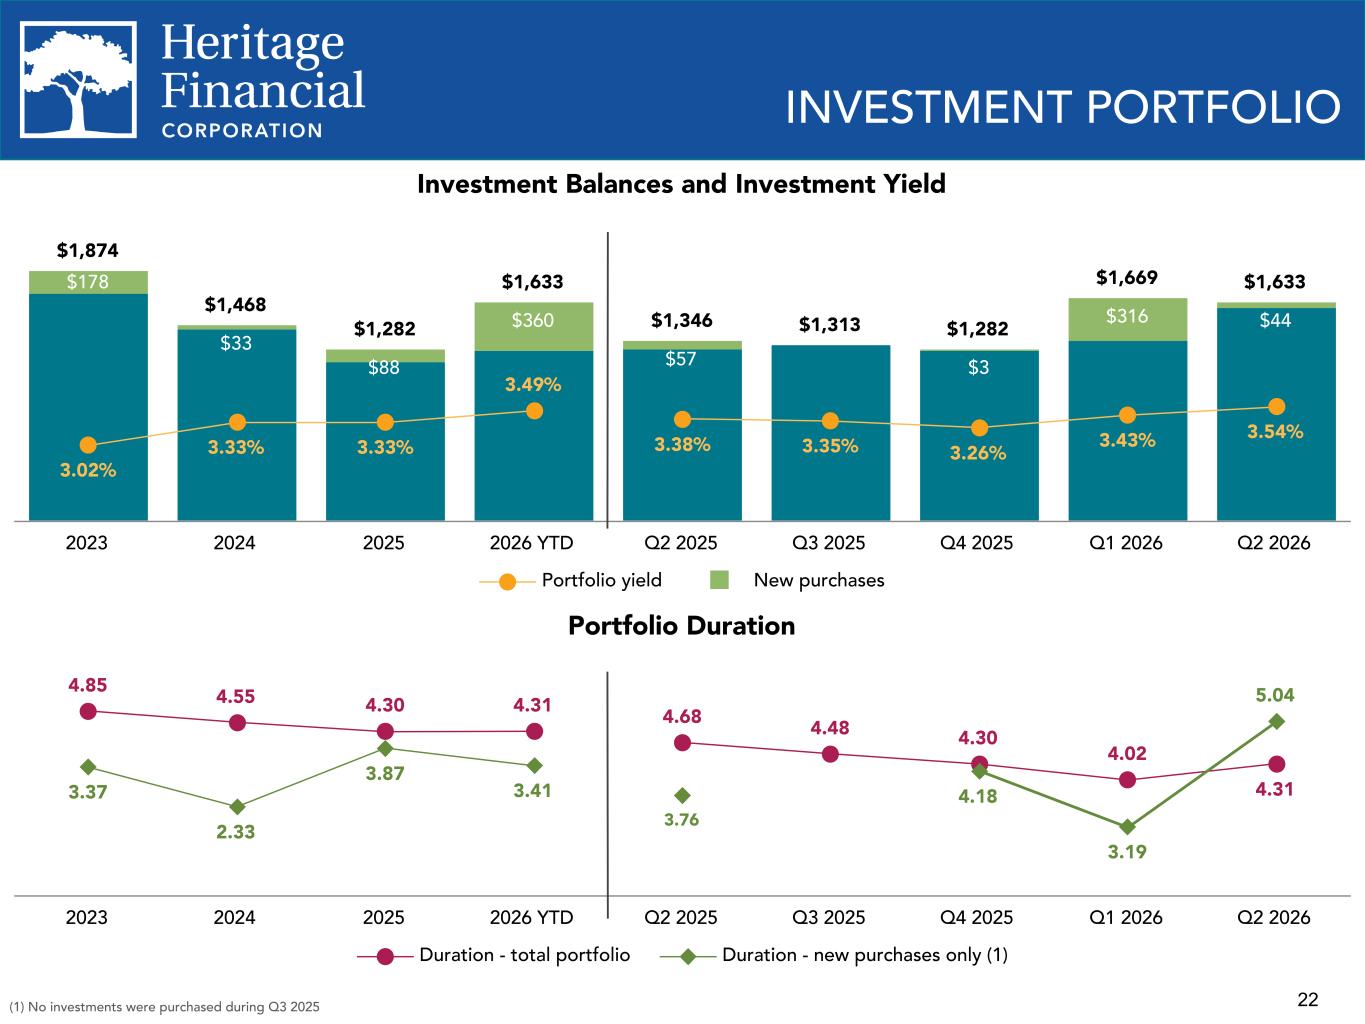
Total investment securities decreased $36.1 million, or 2.2%, to $1.63 billion at June 30, 2026, from $1.67 billion at March 31, 2026. The Company sold $38.1 million of investment securities at a pre-tax loss of $217,000 during the quarter. In addition, there were investment maturities and repayments of $35.8 million and a $6.4 million increase in unrealized losses on available for sale securities during the second quarter of 2026. These decreases to carrying value were partially offset by investment security purchases of $44.0 million during the second quarter of 2026.
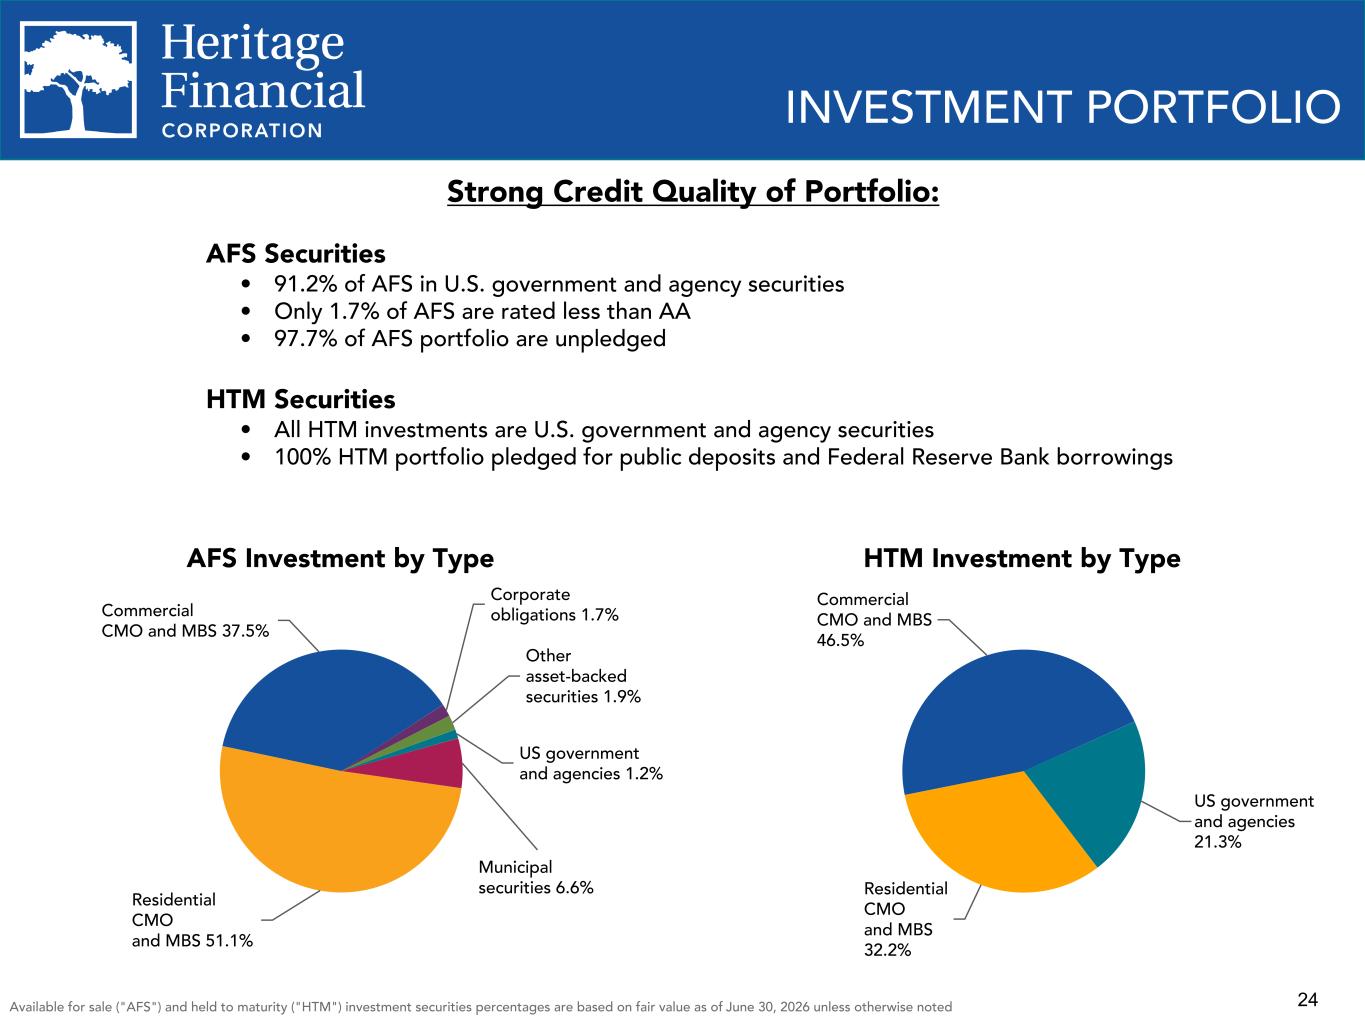
The following table summarizes the composition of the Company's investment securities portfolio at the dates indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
June 30, 2026 |
|
March 31, 2026 |
|
Change |
| |
Balance |
|
% of
Total |
|
Balance |
|
% of
Total |
|
$ |
|
% |
| |
(Dollars in thousands) |
| Investment securities available for sale, at fair value: |
| U.S. government and agency securities |
$ |
11,823 |
|
|
0.7 |
% |
|
$ |
11,861 |
|
|
0.7 |
% |
|
$ |
(38) |
|
|
(0.3) |
% |
| Municipal securities |
64,390 |
|
|
3.9 |
|
|
63,972 |
|
|
3.8 |
|
|
418 |
|
|
0.7 |
|
Residential CMO and MBS(1)
|
496,178 |
|
|
30.4 |
|
|
497,228 |
|
|
29.8 |
|
|
(1,050) |
|
|
(0.2) |
|
Commercial CMO and MBS(1)
|
363,713 |
|
|
22.2 |
|
|
396,816 |
|
|
23.7 |
|
|
(33,103) |
|
|
(8.3) |
|
| Corporate obligations |
16,423 |
|
|
1.0 |
|
|
11,580 |
|
|
0.7 |
|
|
4,843 |
|
|
41.8 |
|
| Other asset-backed securities |
18,910 |
|
|
1.2 |
|
|
19,691 |
|
|
1.2 |
|
|
(781) |
|
|
(4.0) |
|
| Total |
$ |
971,437 |
|
|
59.4 |
% |
|
$ |
1,001,148 |
|
|
59.9 |
% |
|
$ |
(29,711) |
|
|
(3.0) |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
June 30, 2026 |
|
March 31, 2026 |
|
Change |
| |
Balance |
|
% of
Total |
|
Balance |
|
% of
Total |
|
$ |
|
% |
| |
(Dollars in thousands) |
| Investment securities held to maturity, at amortized cost: |
| U.S. government and agency securities |
$ |
151,363 |
|
|
9.3 |
% |
|
$ |
151,341 |
|
|
9.1 |
% |
|
$ |
22 |
|
|
— |
% |
|
|
|
|
|
|
|
|
|
|
|
|
Residential CMO and MBS(1)
|
207,387 |
|
|
12.7 |
|
|
213,096 |
|
|
12.8 |
|
|
(5,709) |
|
|
(2.7) |
|
Commercial CMO and MBS(1)
|
303,089 |
|
|
18.6 |
|
|
303,826 |
|
|
18.2 |
|
|
(737) |
|
|
(0.2) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total |
$ |
661,839 |
|
|
40.6 |
% |
|
$ |
668,263 |
|
|
40.1 |
% |
|
$ |
(6,424) |
|
|
(1.0) |
% |
|
|
|
|
|
|
|
|
|
|
|
|
| Total investment securities |
$ |
1,633,276 |
|
|
100.0 |
% |
|
$ |
1,669,411 |
|
|
100.0 |
% |
|
$ |
(36,135) |
|
|
(2.2) |
% |
(1) U.S. government agency and government-sponsored enterprise CMO and MBS.
Loans Receivable
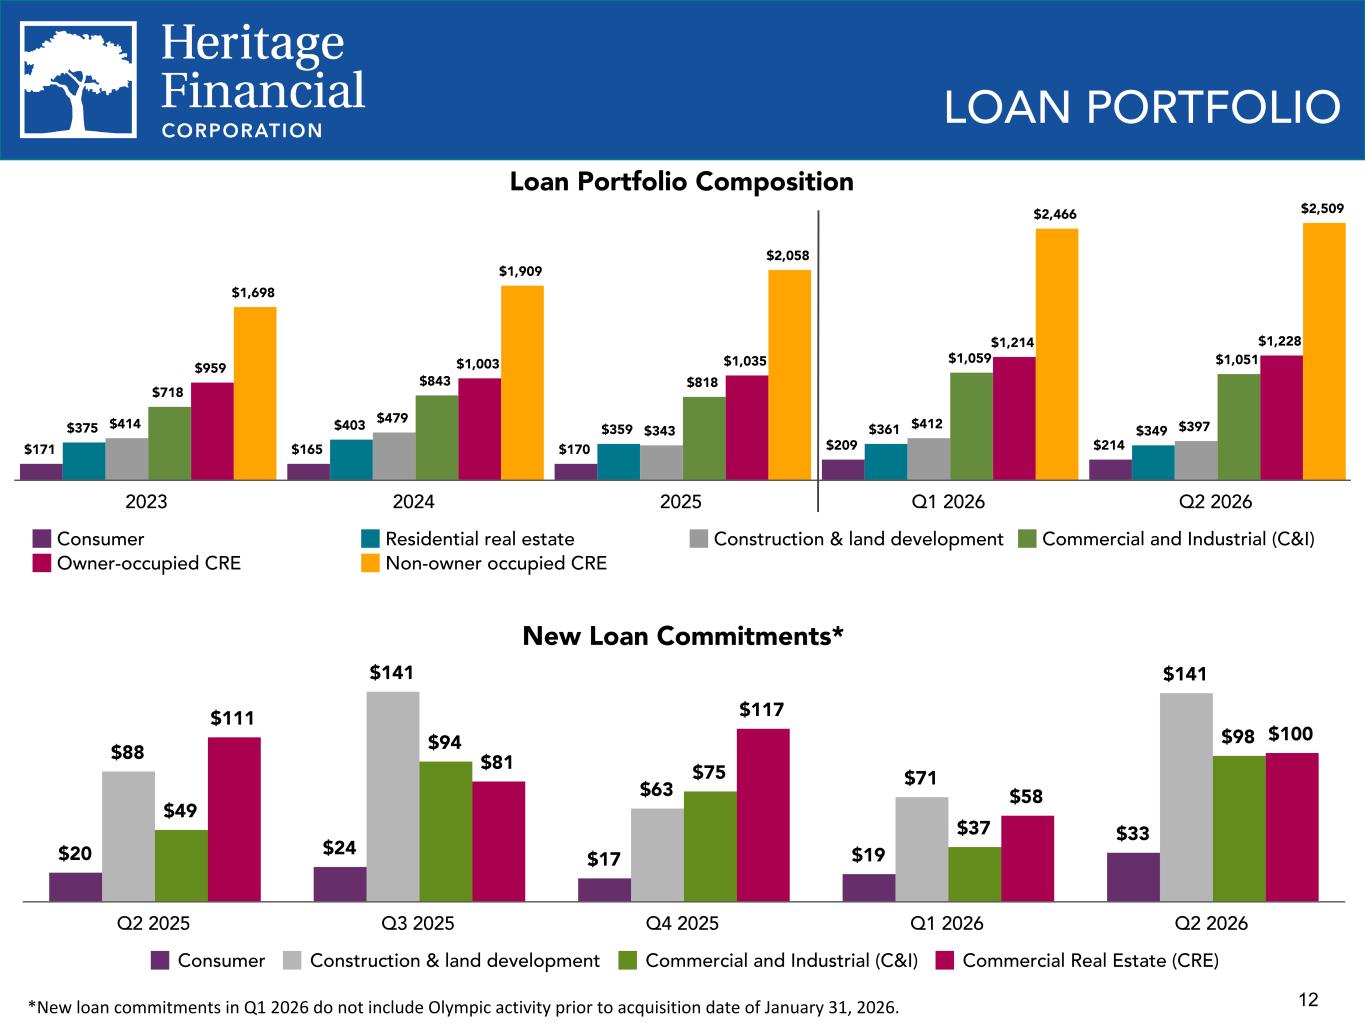
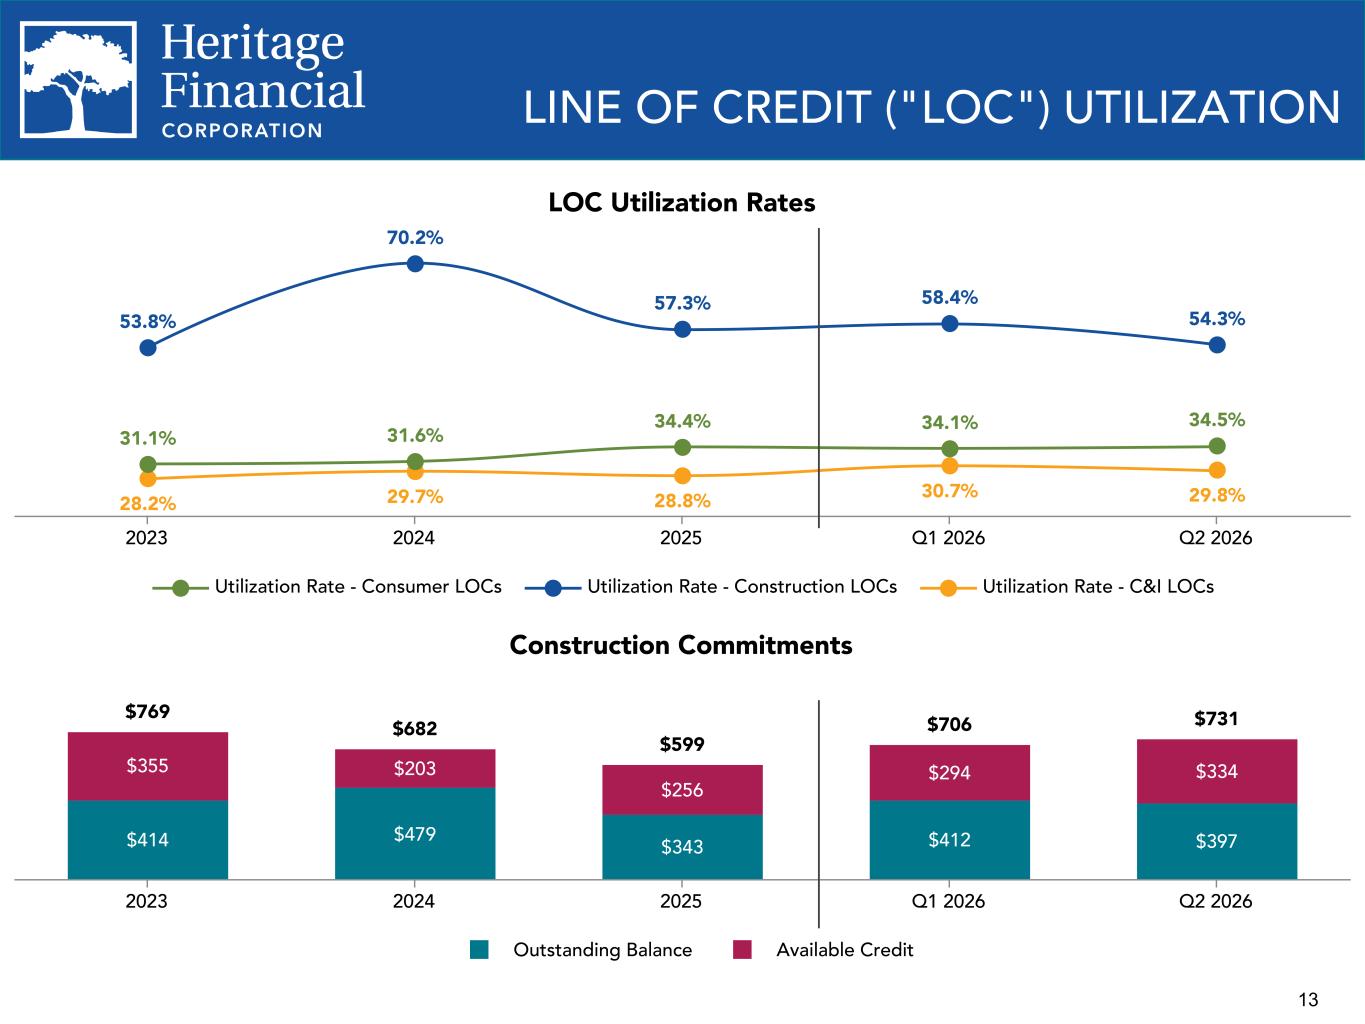
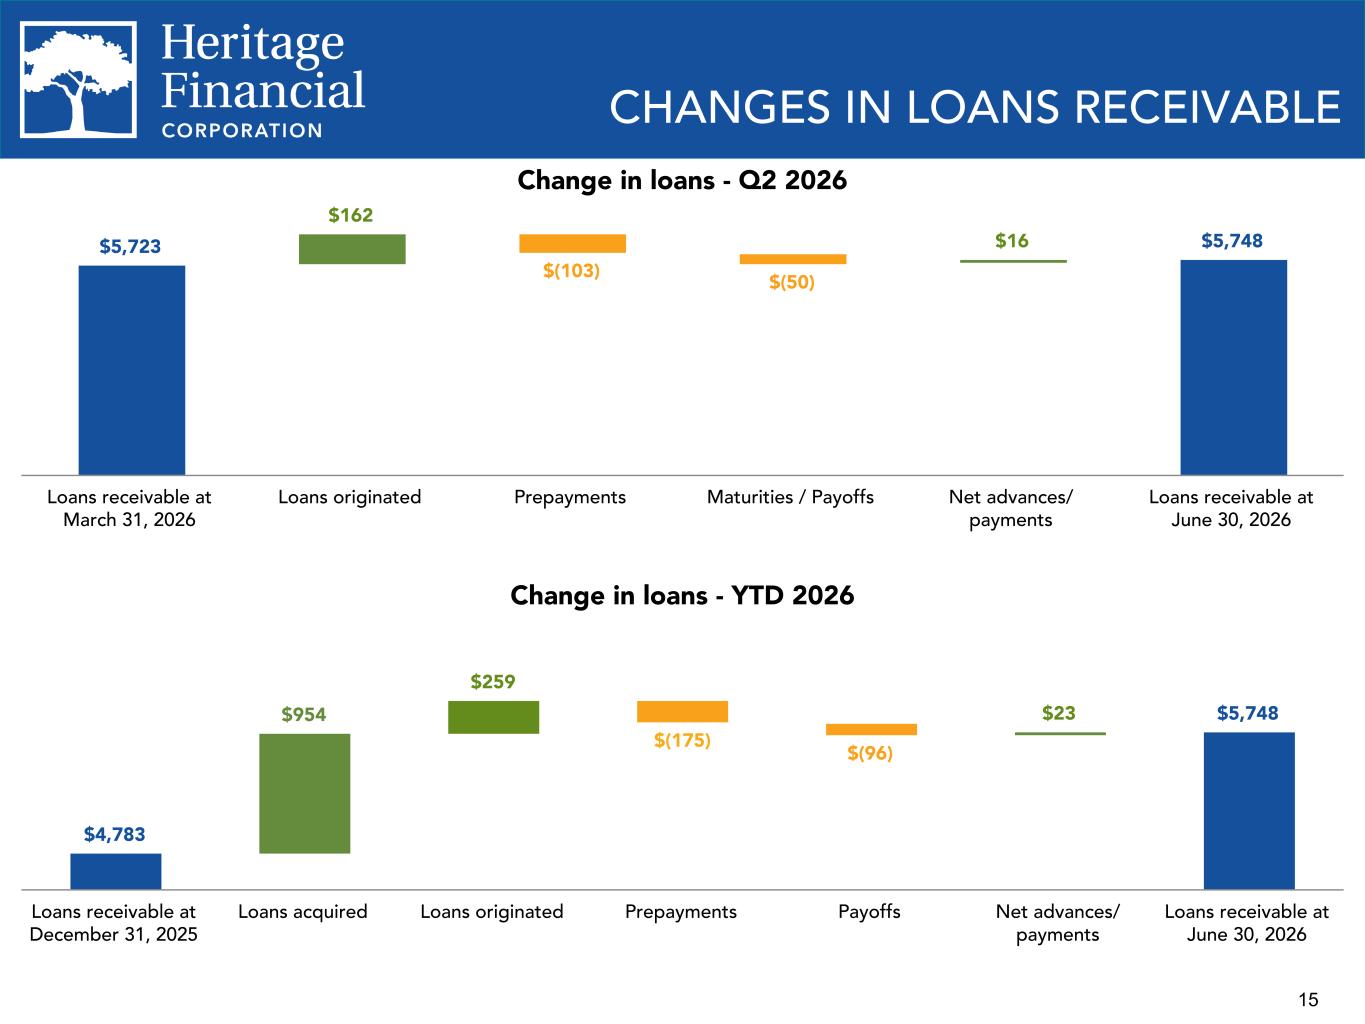
Loans receivable increased $25.5 million, or 0.4%, during the second quarter of 2026. New loans funded during the second quarter of 2026 were $162.2 million, an increase from new loans funded during the first quarter of 2026 of $97.0 million and new loans funded during the second quarter of 2025 of $139.9 million. Loan prepayments were higher at $102.5 million during the second quarter of 2026, compared to $72.5 million during the first quarter of 2026. Loan payoffs were slightly higher at $49.9 million, compared to $46.5 million in the first quarter of 2026.
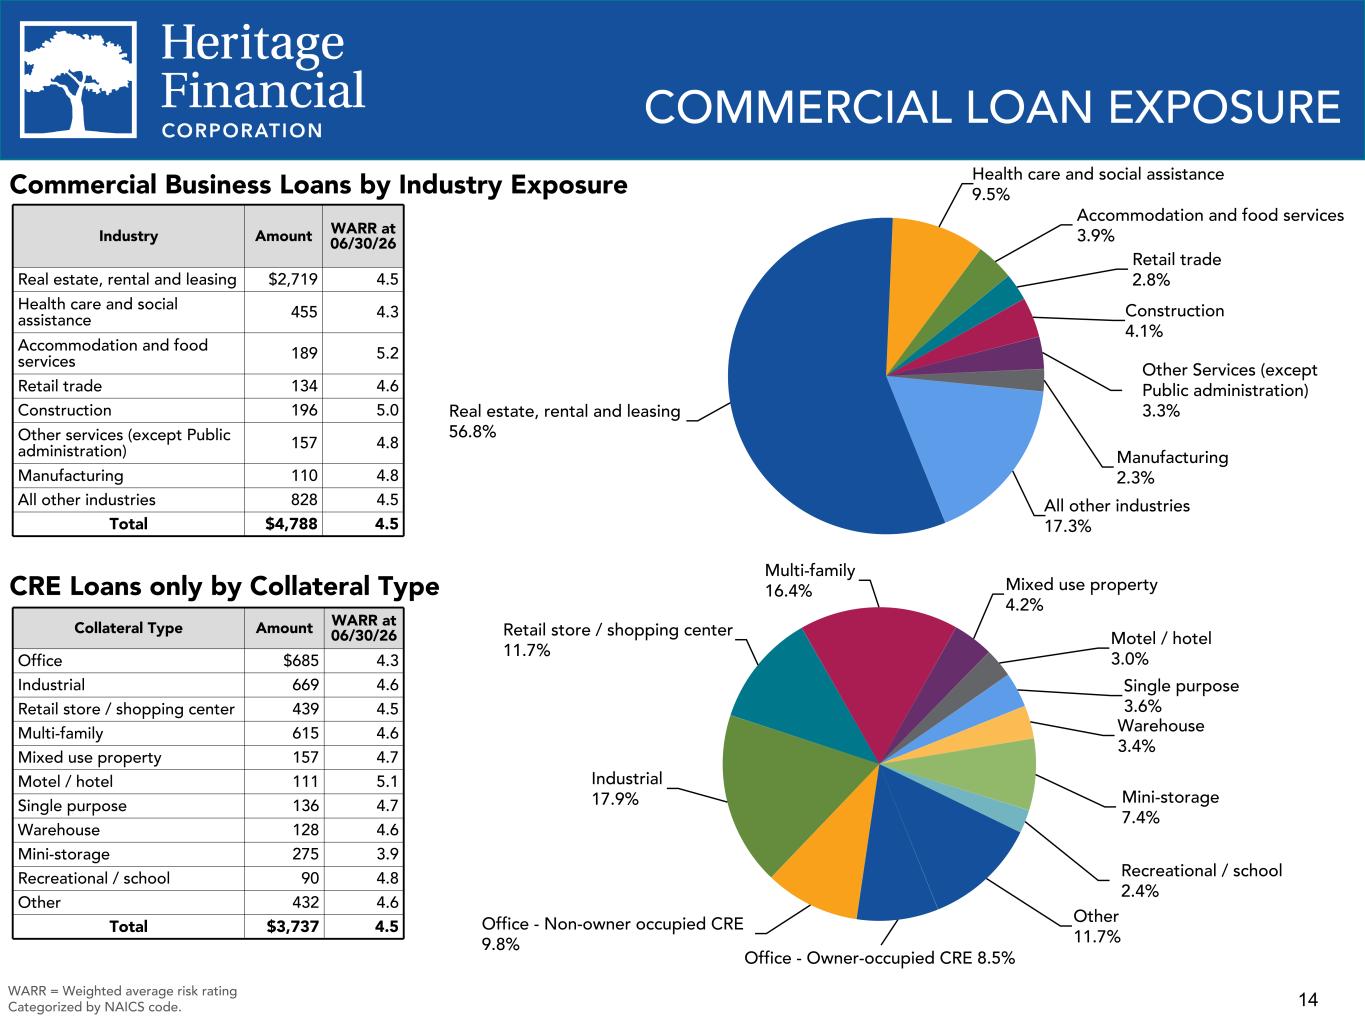
Commercial and industrial loans decreased $8.2 million, or 0.8%, during the second quarter of 2026, due primarily to pay downs on outstanding balances, partially offset by new loan production of $34.5 million. Owner-occupied commercial real estate ("CRE") loans increased $14.1 million, or 1.2%, during the second quarter, due primarily to new loan production of $41.8 million, offset by pay downs on outstanding balances. Non-owner occupied CRE loans increased $42.9 million, or 1.7%, during the quarter, due primarily to new loan production of $55.7 million, offset by pay downs on outstanding balances. Residential construction increased $13.2 million, or 10.7%, during the second quarter, due primarily to new loan production of $18.9 million, partially offset by pay downs on outstanding balances. Commercial and multifamily construction loans decreased $28.5 million or 9.9%, during the quarter, due primarily to pay downs on outstanding balances.
The following table summarizes the Company's loans receivable at the dates indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
June 30, 2026 |
|
March 31, 2026 |
|
Change |
|
Balance |
|
% of Total |
|
Balance |
|
% of Total |
|
$ |
|
% |
|
(Dollars in thousands) |
| Commercial business: |
|
|
|
|
|
|
|
|
|
|
|
| Commercial and industrial |
$ |
1,051,269 |
|
|
18.3 |
% |
|
$ |
1,059,457 |
|
|
18.5 |
% |
|
$ |
(8,188) |
|
|
(0.8) |
% |
Owner-occupied CRE |
1,227,674 |
|
|
21.4 |
|
|
1,213,585 |
|
|
21.2 |
|
|
14,089 |
|
|
1.2 |
|
| Non-owner occupied CRE |
2,509,283 |
|
|
43.6 |
|
|
2,466,417 |
|
|
43.1 |
|
|
42,866 |
|
|
1.7 |
|
| Total commercial business |
4,788,226 |
|
|
83.3 |
|
|
4,739,459 |
|
|
82.8 |
|
|
48,767 |
|
|
1.0 |
|
Residential real estate |
348,838 |
|
|
6.1 |
|
|
361,384 |
|
|
6.3 |
|
|
(12,546) |
|
|
(3.5) |
|
| Real estate construction and land development: |
|
|
|
|
|
|
|
|
|
|
|
Residential |
136,595 |
|
|
2.4 |
|
|
123,409 |
|
|
2.2 |
|
|
13,186 |
|
|
10.7 |
|
Commercial and multifamily |
259,947 |
|
|
4.5 |
|
|
288,493 |
|
|
5.0 |
|
|
(28,546) |
|
|
(9.9) |
|
| Total real estate construction and land development |
396,542 |
|
|
6.9 |
|
|
411,902 |
|
|
7.2 |
|
|
(15,360) |
|
|
(3.7) |
|
| Consumer |
214,135 |
|
|
3.7 |
|
|
209,493 |
|
|
3.7 |
|
|
4,642 |
|
|
2.2 |
|
| Loans receivable |
$ |
5,747,741 |
|
|
100.0 |
% |
|
$ |
5,722,238 |
|
|
100.0 |
% |
|
$ |
25,503 |
|
|
0.4 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Deposits
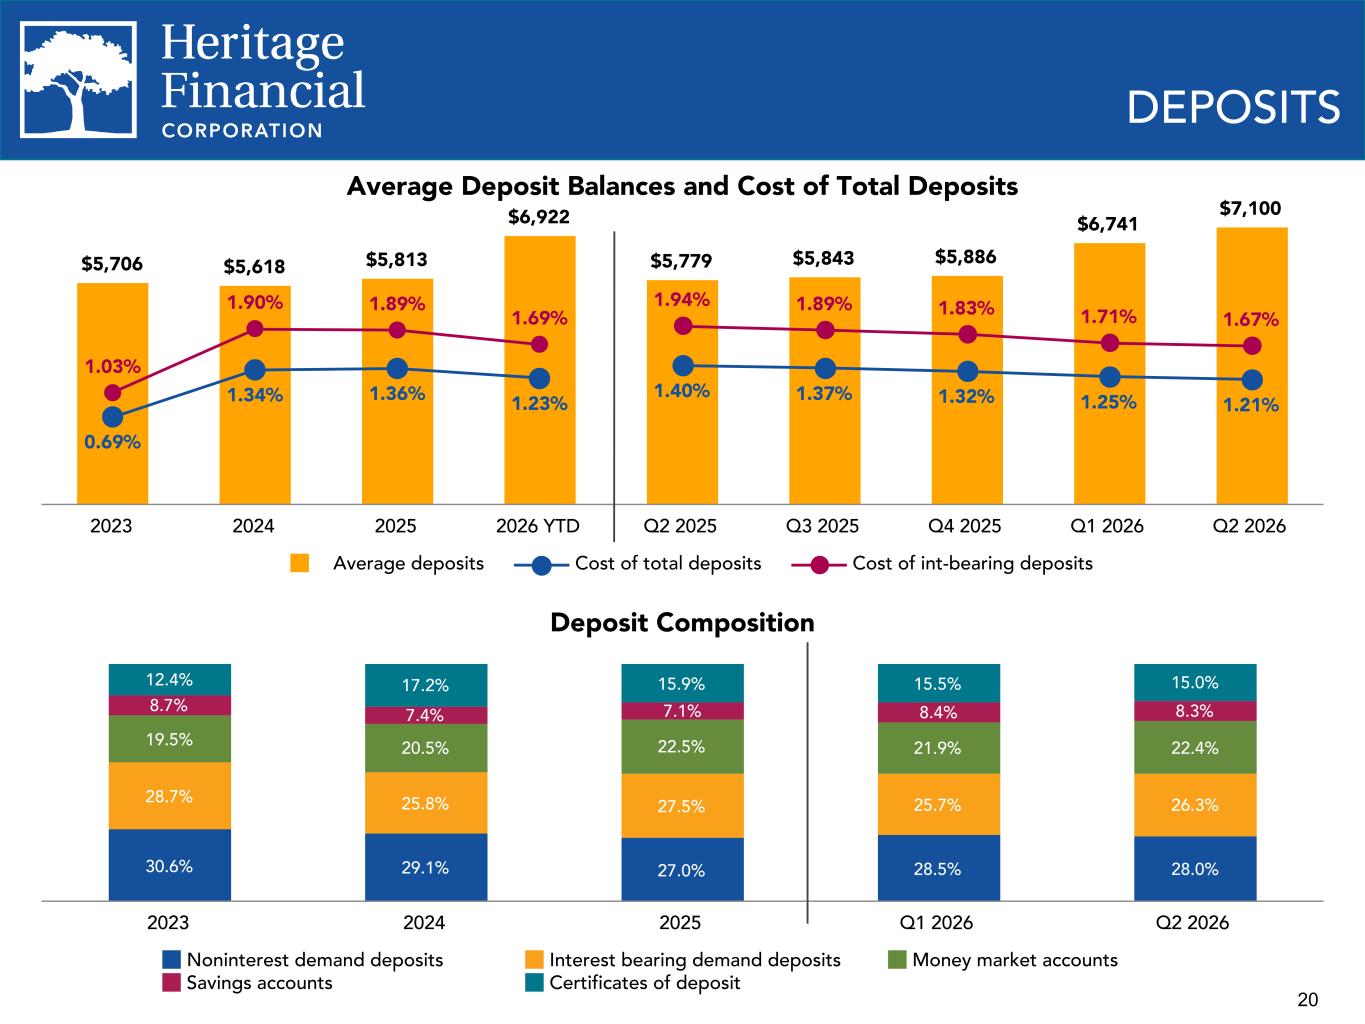
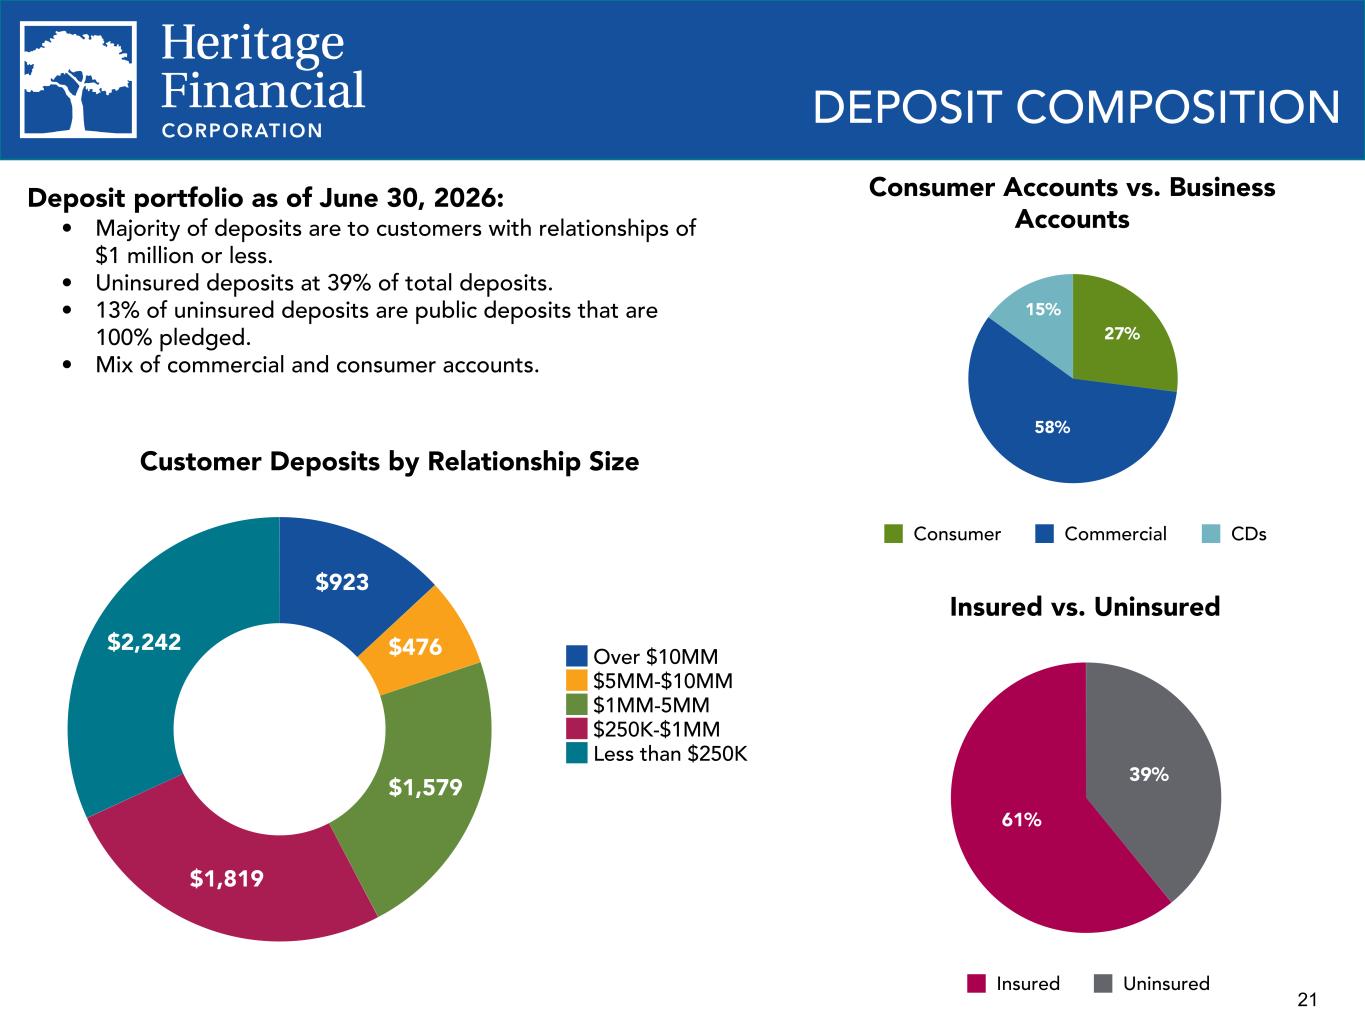
Total deposits decreased $209.8 million, or 2.9%, to $7.04 billion at June 30, 2026, from $7.25 billion at March 31, 2026.
Non-maturity deposits decreased by $138.4 million, or 2.3%, from March 31, 2026 due primarily to a decline in customer balances in noninterest bearing demand accounts as is typical in the second quarter of each year due to tax payments. Noninterest demand deposits declined mostly due a single deposit relationship which had approximately $67.0 million in funds which were deposited on a short-term basis in the first quarter of 2026 and withdrawn in the second quarter of 2026. Certificates of deposit declined $71.4 million during the second quarter of 2026 due mostly to the maturity of brokered certificates of deposit of $48.5 million.
The following table summarizes the Company's total deposits at the dates indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
June 30, 2026 |
|
March 31, 2026 |
|
Change |
|
Balance |
|
% of Total |
|
Balance |
|
% of Total |
|
$ |
|
% |
|
(Dollars in thousands) |
| Noninterest demand deposits |
$ |
1,972,702 |
|
|
28.0 |
% |
|
$ |
2,066,383 |
|
|
28.5 |
% |
|
$ |
(93,681) |
|
|
(4.5) |
% |
| Interest bearing demand deposits |
1,854,634 |
|
|
26.3 |
|
|
1,860,679 |
|
|
25.7 |
|
|
(6,045) |
|
|
(0.3) |
|
| Money market accounts |
1,574,835 |
|
|
22.4 |
|
|
1,588,678 |
|
|
21.9 |
|
|
(13,843) |
|
|
(0.9) |
|
| Savings accounts |
581,259 |
|
|
8.3 |
|
|
606,119 |
|
|
8.4 |
|
|
(24,860) |
|
|
(4.1) |
|
| Total non-maturity deposits |
5,983,430 |
|
|
85.0 |
|
|
6,121,859 |
|
|
84.5 |
|
|
(138,429) |
|
|
(2.3) |
|
| Certificates of deposit |
1,055,276 |
|
|
15.0 |
|
|
1,126,678 |
|
|
15.5 |
|
|
(71,402) |
|
|
(6.3) |
|
| Total deposits |
$ |
7,038,706 |
|
|
100.0 |
% |
|
$ |
7,248,537 |
|
|
100.0 |
% |
|
$ |
(209,831) |
|
|
(2.9) |
% |
Borrowings
Total borrowings increased $146.3 million to $166.3 million at June 30, 2026, compared to $20.0 million at March 31, 2026. All outstanding borrowings at June 30, 2026 were with the Federal Home Loan Bank ("FHLB") and mature in the third quarter of 2026.
Stockholders' Equity
Total stockholders' equity decreased $6.0 million, or 0.5%, to $1.11 billion at June 30, 2026, compared to $1.12 billion at March 31, 2026. This decrease was partially due to the repurchase of 372,343 shares of the Company's common stock, for an aggregate purchase price of $10.0 million, under the Company's current share repurchase plan.
The following table summarizes changes in stockholders' equity for the Company for the period indicated:
|
|
|
|
|
|
|
Quarter Ended |
|
June 30,
2026 |
|
(In thousands) |
| Balance, beginning of period |
$ |
1,115,691 |
|
|
|
| Net income |
17,546 |
|
| Cash dividends declared on common stock |
(10,002) |
|
| Common stock repurchased |
(10,112) |
|
Other comprehensive loss |
(5,000) |
|
| Other |
1,569 |
|
| Balance, end of period |
$ |
1,109,692 |
|
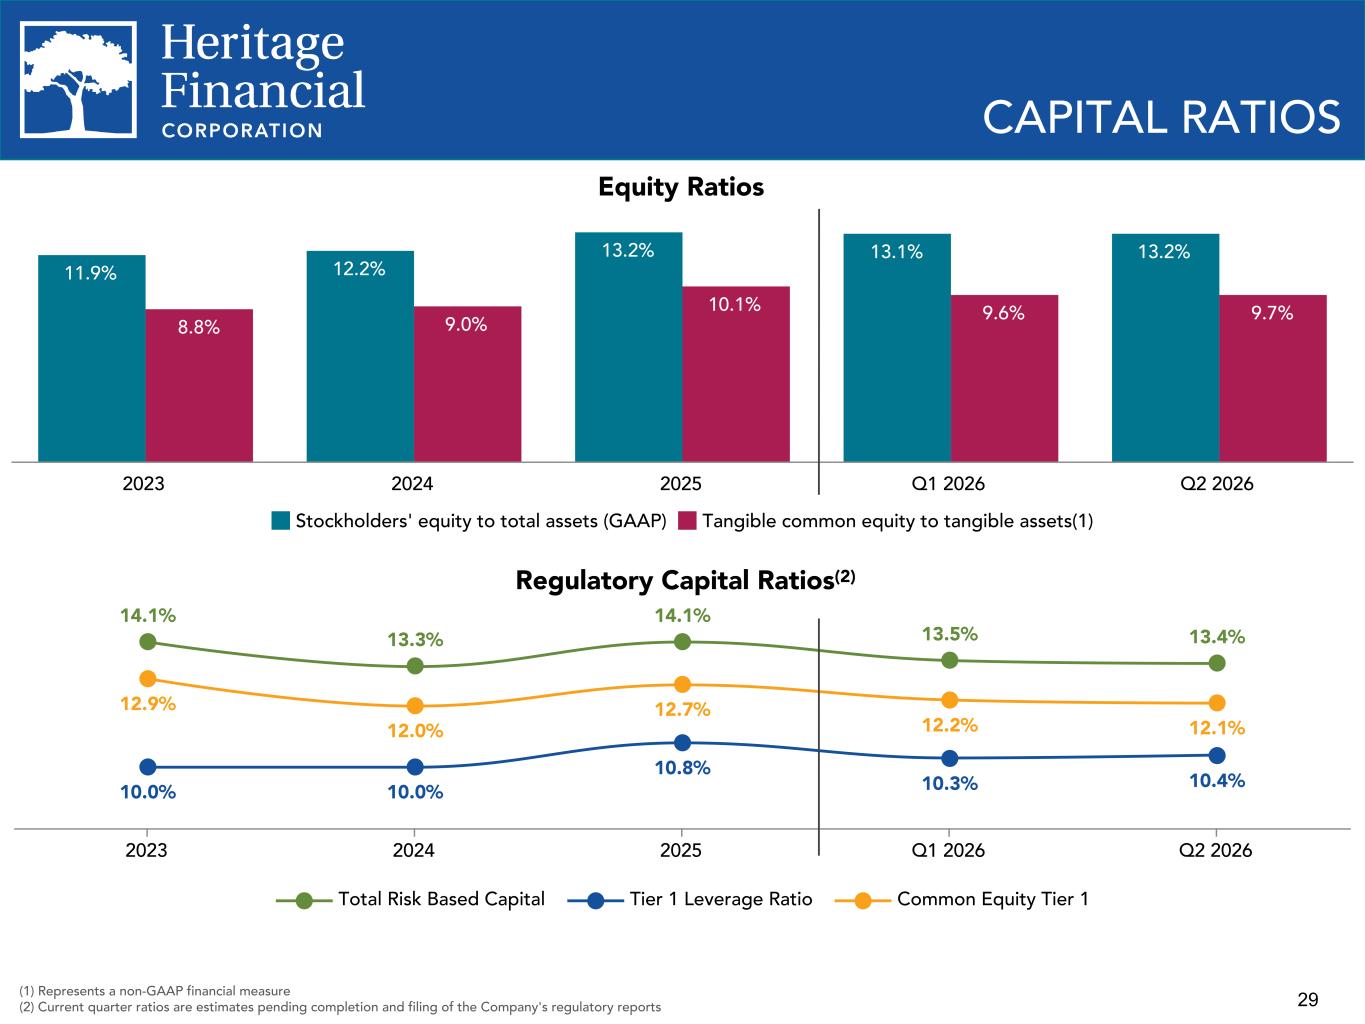
The Company and Bank continued to maintain capital levels in excess of the applicable regulatory requirements to be categorized as “well-capitalized” at June 30, 2026.
The following table summarizes the capital ratios for the Company at the dates indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
June 30,
2026 |
|
March 31,
2026 |
|
|
| Stockholders' equity to total assets |
13.2% |
|
13.1% |
|
|
Tangible common equity to tangible assets (1)
|
9.7 |
|
9.6 |
|
|
Common equity tier 1 capital ratio (2)
|
12.1 |
|
12.2 |
|
|
Leverage ratio (2)
|
10.4 |
|
10.3 |
|
|
Tier 1 capital ratio (2)
|
12.5 |
|
12.5 |
|
|
Total capital ratio (2)
|
13.4 |
|
13.5 |
|
|
(1) Represents a non-GAAP financial measure. See “Non-GAAP Financial Measures” section for a reconciliation to the comparable GAAP financial measure.
(2) Current quarter ratios are estimates pending completion and filing of the Company’s regulatory reports.
Allowance for Credit Losses and Provision for Credit Losses
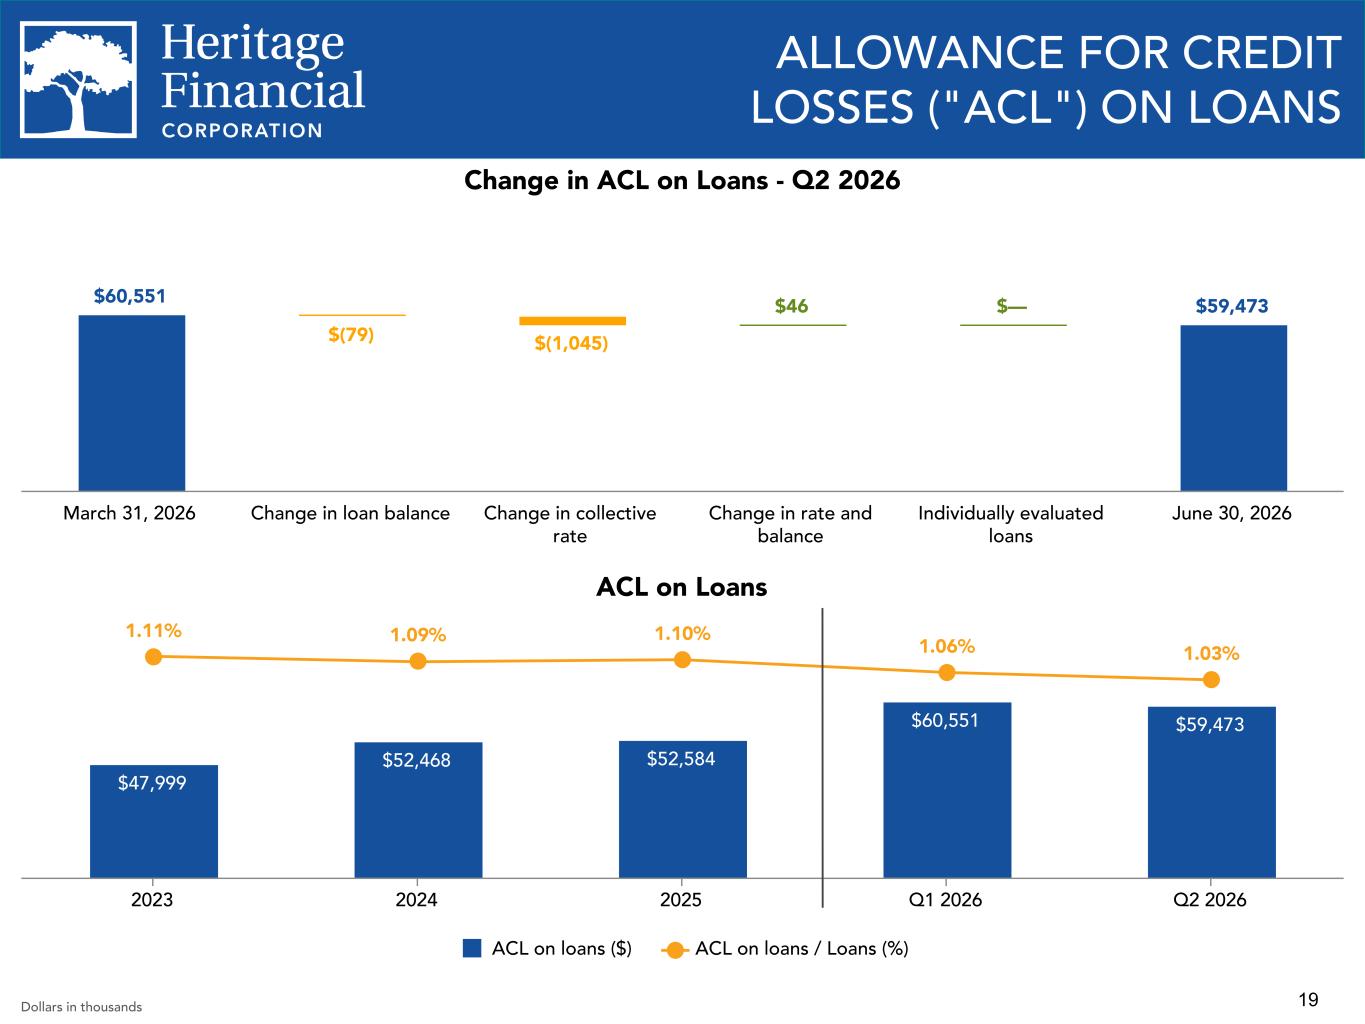
The allowance for credit losses ("ACL") on loans as a percentage of loans receivable was 1.03% at June 30, 2026, compared to 1.06% at March 31, 2026. The decrease in the ACL as a percentage of loans was due primarily to a decrease in the weighted average life of loans in the real estate construction and land development segment and an incremental change in the mix of loans from loans which have a higher ACL percentage to those which have a lower ACL percentage.
During the second quarter of 2026, the Company recorded a $844,000 reversal of provision for credit losses on loans, compared to an $820,000 reversal of provision during the first quarter of 2026. During the second quarter of 2026, the Company recorded a $77,000 reversal of provision for credit losses on unfunded commitments, compared to a $210,000 reversal of provision for credit losses on unfunded commitments during the first quarter of 2026.
The following table provides detail on the changes in the ACL on loans and the ACL on unfunded commitments ("ACL on Unfunded"), and the related (reversal of) provision for credit losses for the periods indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
As of or for the Quarter Ended |
|
June 30, 2026 |
|
March 31, 2026 |
|
June 30, 2025 |
|
ACL on Loans |
|
ACL on Unfunded |
|
Total |
|
ACL on Loans |
|
ACL on Unfunded |
|
Total |
|
ACL on Loans |
|
ACL on Unfunded |
|
Total |
|
(Dollars in thousands) |
| Balance, beginning of period |
$ |
60,551 |
|
|
$ |
1,185 |
|
|
$ |
61,736 |
|
|
$ |
52,584 |
|
|
$ |
1,047 |
|
|
$ |
53,631 |
|
|
$ |
52,160 |
|
|
$ |
647 |
|
|
$ |
52,807 |
|
Initial ACL recorded for the Merger |
— |
|
|
— |
|
|
$ |
— |
|
|
9,339 |
|
|
348 |
|
|
$ |
9,687 |
|
|
— |
|
|
— |
|
|
$ |
— |
|
| (Reversal of) provision for credit losses |
(844) |
|
|
(77) |
|
|
(921) |
|
|
(820) |
|
|
(210) |
|
|
(1,030) |
|
|
863 |
|
|
93 |
|
|
956 |
|
| (Net charge-offs) / recoveries |
(234) |
|
|
— |
|
|
(234) |
|
|
(552) |
|
|
— |
|
|
(552) |
|
|
(494) |
|
|
— |
|
|
(494) |
|
| Balance, end of period |
$ |
59,473 |
|
|
$ |
1,108 |
|
|
$ |
60,581 |
|
|
$ |
60,551 |
|
|
$ |
1,185 |
|
|
$ |
61,736 |
|
|
$ |
52,529 |
|
|
$ |
740 |
|
|
$ |
53,269 |
|
Credit Quality
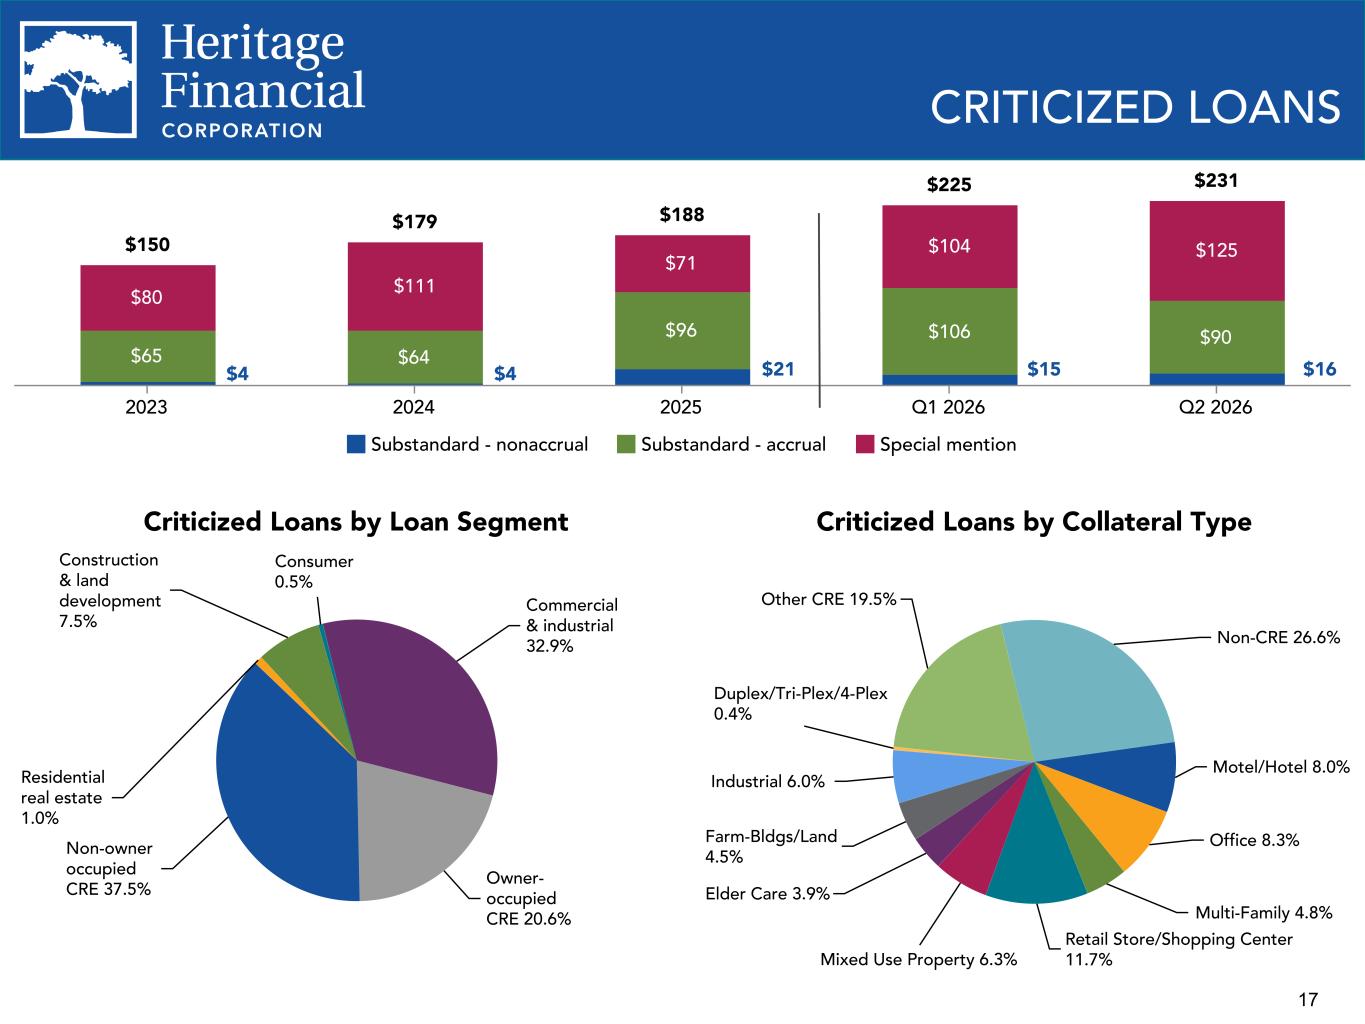
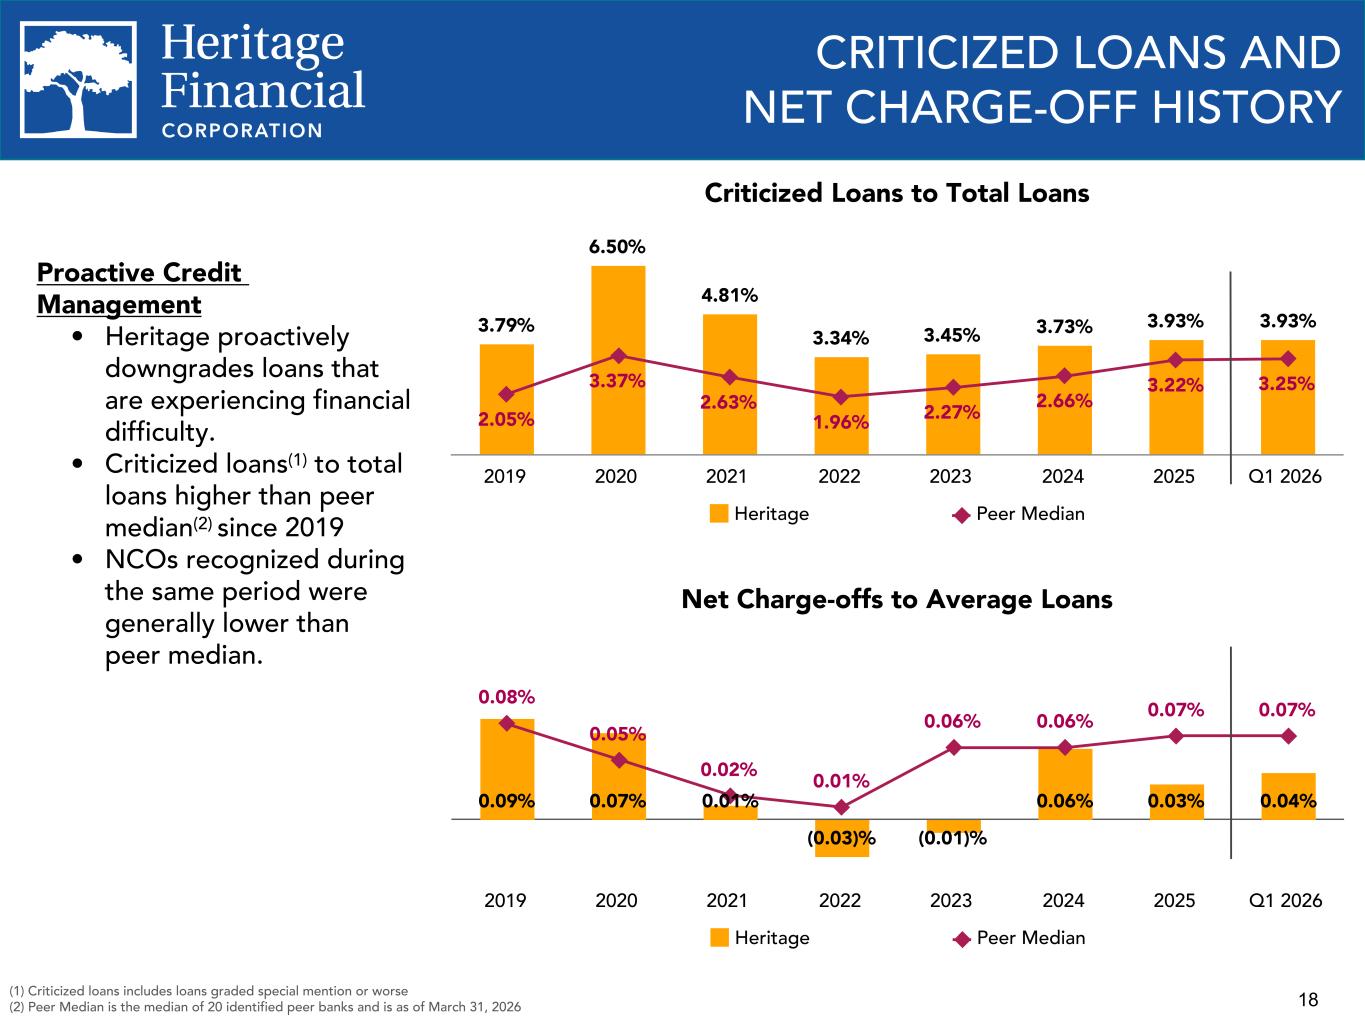
Classified loans (loans rated substandard or worse) decreased $15.9 million from the prior quarter due primarily to loan payoffs during the quarter. The percentage of classified loans to loans receivable decreased to 1.8% at June 30, 2026, compared to 2.1% at March 31, 2026.
The following table illustrates total loans by risk rating and their respective percentage of total loans at the dates indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
June 30, 2026 |
|
March 31, 2026 |
|
Balance |
|
% of Total |
|
Balance |
|
% of Total |
|
(Dollars in thousands) |
| Risk Rating: |
|
|
|
|
|
|
|
| Pass |
$ |
5,517,189 |
|
|
96.0 |
% |
|
$ |
5,497,208 |
|
|
96.1 |
% |
| Special Mention |
125,108 |
|
|
2.2 |
|
|
103,699 |
|
|
1.8 |
|
| Substandard |
105,444 |
|
|
1.8 |
|
|
121,331 |
|
|
2.1 |
|
| Total |
$ |
5,747,741 |
|
|
100.0 |
% |
|
$ |
5,722,238 |
|
|
100.0 |
% |
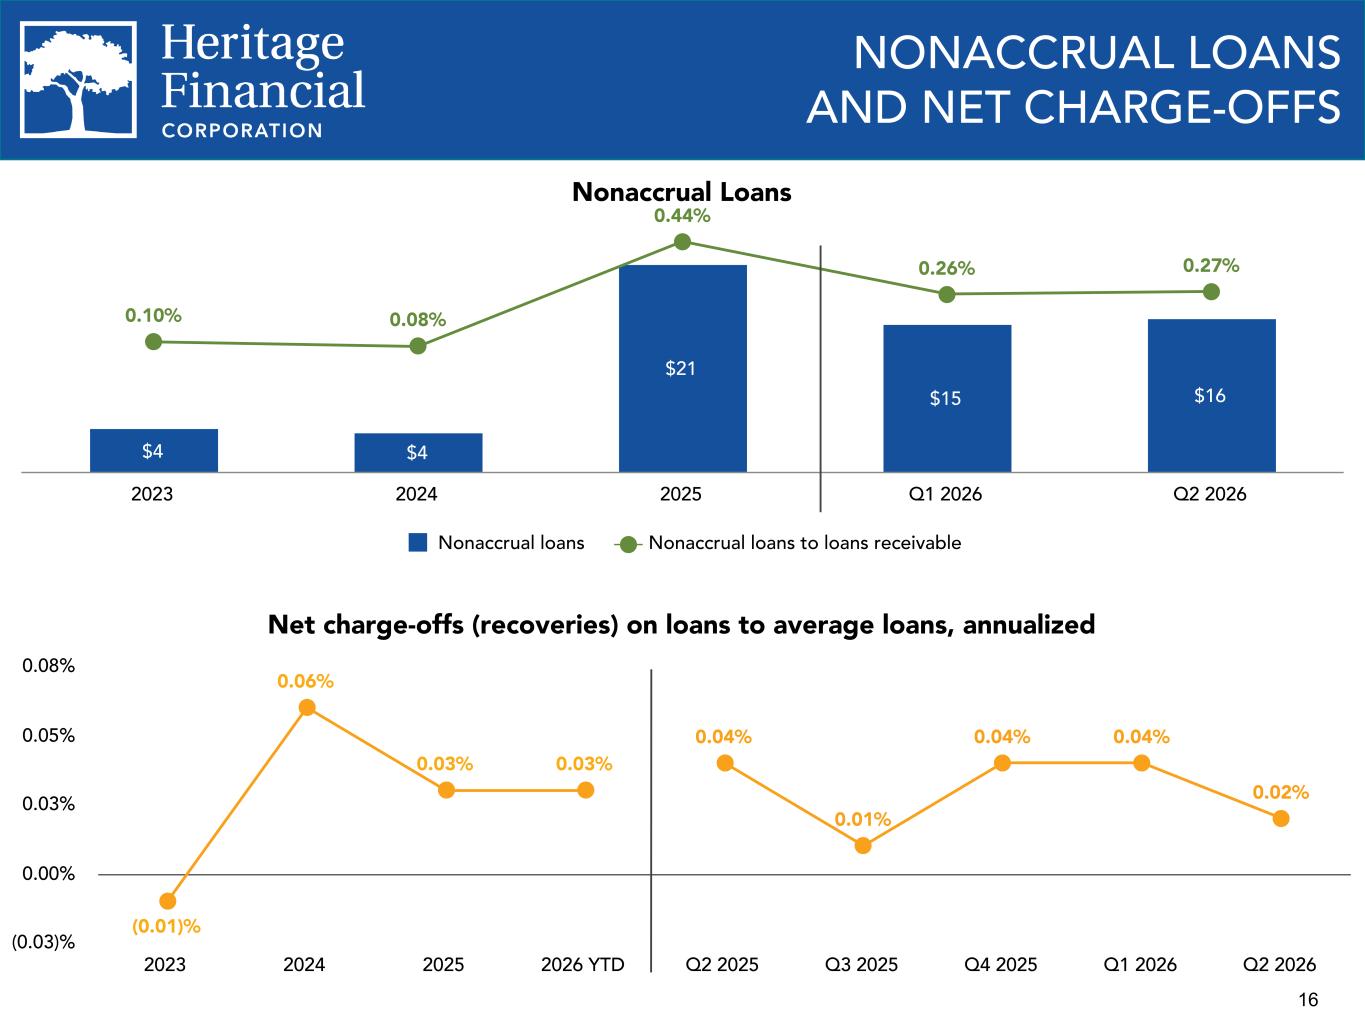
Nonaccrual loans were $15.5 million at June 30, 2026, compared to $15.0 million at March 31, 2026. Two commercial and industrial loan relationships totaling $5.0 million were migrated to nonaccrual during the second quarter of 2026, and both were paid off prior to the end of the quarter.
The following table illustrates changes in nonaccrual loans during the periods indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Quarter Ended |
|
June 30,
2026 |
|
March 31,
2026 |
|
June 30,
2025 |
|
(Dollars in thousands) |
| Balance, beginning of period |
$ |
14,958 |
|
|
$ |
20,976 |
|
|
$ |
4,438 |
|
| Additions |
5,988 |
|
|
3,388 |
|
|
7,922 |
|
Net principal payments |
(280) |
|
|
(261) |
|
|
(2,041) |
|
| Payoffs |
(5,156) |
|
|
(7,800) |
|
|
— |
|
| Charge-offs |
— |
|
|
(463) |
|
|
(454) |
|
| Transfer to OREO |
— |
|
|
(741) |
|
|
— |
|
| Return to accrual |
— |
|
|
(141) |
|
|
— |
|
| Balance, end of period |
$ |
15,510 |
|
|
$ |
14,958 |
|
|
$ |
9,865 |
|
| Nonaccrual loans to loans receivable |
0.27 |
% |
|
0.26 |
% |
|
0.21 |
% |
Liquidity
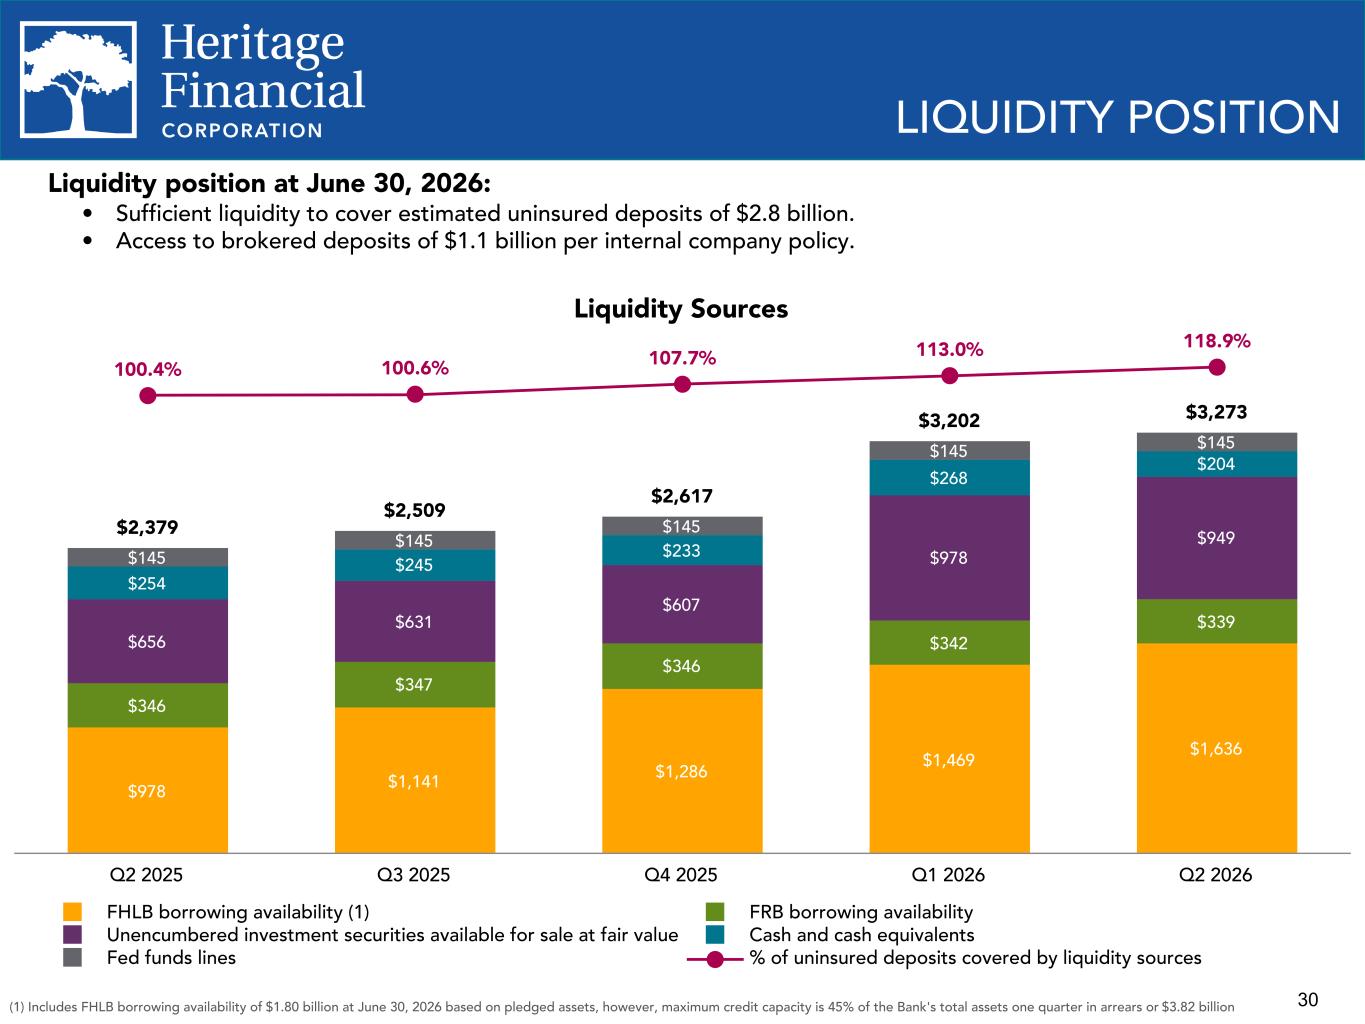
Total liquidity sources available at June 30, 2026 totaled $3.27 billion. This included on- and off-balance sheet liquidity. The Company has access to FHLB advances and the Federal Reserve Bank ("FRB") Discount Window. The Company's available liquidity sources at June 30, 2026 represented a coverage ratio of 46.5% of total deposits and 118.9% of estimated uninsured deposits.
The following table summarizes the Company's available liquidity as of the dates indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
Quarter Ended |
|
June 30,
2026 |
|
March 31,
2026 |
|
(Dollars in thousands) |
On-balance sheet liquidity |
|
|
|
| Cash and cash equivalents |
$ |
204,375 |
|
|
$ |
268,143 |
|
Unencumbered investment securities available for sale (1)
|
949,021 |
|
|
978,332 |
|
Total on-balance sheet liquidity |
$ |
1,153,396 |
|
|
$ |
1,246,475 |
|
Off-balance sheet liquidity |
|
|
|
| FRB borrowing availability |
$ |
339,029 |
|
|
$ |
341,449 |
|
FHLB borrowing availability (2)
|
1,635,593 |
|
|
1,469,277 |
|
| Fed funds line borrowing availability with correspondent banks |
145,000 |
|
|
145,000 |
|
Total off-balance sheet liquidity |
$ |
2,119,622 |
|
|
$ |
1,955,726 |
|
| Total available liquidity |
$ |
3,273,018 |
|
|
$ |
3,202,201 |
|
(1) Investment securities available for sale at fair value.
(2) Includes FHLB total borrowing availability of $1.80 billion at June 30, 2026 based on pledged assets, however, maximum credit capacity was 45% of the Bank's total assets one quarter in arrears or $3.82 billion.
Net Interest Income and Net Interest Margin
Net interest income increased $5.6 million, or 8.1%, during the second quarter of 2026 compared to the first quarter of 2026 due to a $7.0 million increase in total interest income, offset partially by an increase in interest expense of $1.4 million. The increase in net interest income was primarily due to one additional month of income attributable to the assets and liabilities obtained in the Merger which was completed on January 31, 2026.
Net interest margin increased three basis points to 3.99% during the second quarter of 2026, from 3.96% during the first quarter of 2026. The increase in net interest margin was due primarily to the increase in yield on investments and decreases in the cost of interest bearing deposits.
The yield on interest earning assets increased two basis points to 5.21% for the second quarter of 2026, compared to 5.19% for the first quarter of 2026. The increase was primarily due to an increase in yield on investments of 12 basis points to 3.55% for the second quarter of 2026, compared to 3.43% for the first quarter of 2026.
The yield on loans receivable decreased one basis point to 5.72% during the second quarter of 2026, compared to 5.73% during the first quarter of 2026. The decrease was due primarily to recovery of interest income on nonaccrual loans recognized in the first quarter of 2026 which contributed six basis points to loan yield for the first quarter of 2026 and had no impact in the second quarter of 2026. Loan yield also benefited from the incremental accretion on purchased loans in both the first and second quarter of 2026.
The following table presents the net interest margin and loan yield and the effect of the incremental accretion on purchased loans on these ratios for the periods indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
Quarter Ended |
|
|
| |
June 30,
2026 |
|
March 31,
2026 |
|
June 30,
2025 |
|
|
|
|
Net Interest Margin, excluding incremental accretion on purchased loans, annualized: |
Net interest margin |
3.99 |
% |
|
3.96 |
% |
|
3.51 |
% |
|
|
|
|
Exclude impact from incremental accretion on purchased loans(2)
|
(0.09) |
% |
|
(0.09) |
% |
|
(0.01) |
% |
|
|
|
|
|
Net interest margin, excluding incremental accretion on purchased
loans(1)
|
3.90 |
% |
|
3.87 |
% |
|
3.50 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Loan yield, excluding incremental accretion on purchased loans, annualized: |
Loan yield |
5.72 |
% |
|
5.73 |
% |
|
5.50 |
% |
|
|
|
|
Exclude impact from incremental accretion on purchased loans(2)
|
(0.12) |
|
|
(0.12) |
|
|
(0.01) |
|
|
|
|
|
Loan yield, excluding incremental accretion on purchased loans(1)
|
5.60 |
% |
|
5.61 |
% |
|
5.49 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Incremental accretion on purchased loans(1)
|
$ |
1,772 |
|
|
$ |
1,623 |
|
|
$ |
76 |
|
|
|
|
|
(1) Represents a non-GAAP financial measure. See “Non-GAAP Financial Measures” section for a reconciliation to the comparable GAAP financial measure.
(2)Represents the amount of interest income recorded on purchased loans in excess of the contractual stated interest rate in the individual loan notes due to incremental accretion of purchased discount or premium. Purchased discount or premium is the difference between the contractual loan balance and the fair value of acquired loans at the acquisition date. The purchased discount is accreted into income over the remaining life of the loan. The impact of incremental accretion on loan yield will change during any period based on the volume of prepayments, but it is expected to decrease over time as the balance of the purchased loans decreases.
The cost of interest bearing deposits decreased four basis points to 1.67% for the second quarter of 2026, from 1.71% for the first quarter of 2026. This decrease was primarily due to one additional month of interest expense on deposits acquired from Olympic, which had a lower cost of deposits.
Net interest margin increased 48 basis points to 3.99% during the second quarter of 2026, compared to 3.51% for the same period in the prior year. Net interest income increased $19.8 million, or 36.1%, during the second quarter of 2026 compared to the same period in the prior year, due to a combination of an increase in average interest earning assets, which increased substantially as a result of the Merger, and an increase in net interest margin.
The following table provides net interest income information for the periods indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
Quarter Ended |
| |
June 30, 2026 |
|
March 31, 2026 |
|
June 30, 2025 |
| |
Average
Balance |
|
Interest
Earned/
Paid |
|
Average
Yield/
Rate (1)
|
|
Average
Balance |
|
Interest
Earned/
Paid |
|
Average
Yield/
Rate (1)
|
|
Average
Balance |
|
Interest
Earned/
Paid |
|
Average
Yield/
Rate (1)
|
|
(Dollars in thousands) |
| Interest Earning Assets: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Loans receivable (2)(3)
|
$ |
5,740,927 |
|
|
$ |
81,935 |
|
|
5.72 |
% |
|
$ |
5,412,943 |
|
|
$ |
76,445 |
|
|
5.73 |
% |
|
$ |
4,768,558 |
|
|
$ |
65,373 |
|
|
5.50 |
% |
| Taxable securities |
1,635,979 |
|
|
14,464 |
|
|
3.55 |
|
|
1,486,343 |
|
|
12,570 |
|
|
3.43 |
|
|
1,374,770 |
|
|
11,579 |
|
|
3.38 |
|
Nontaxable securities (3)
|
15,439 |
|
|
128 |
|
|
3.33 |
|
|
15,662 |
|
|
129 |
|
|
3.34 |
|
|
15,294 |
|
|
137 |
|
|
3.59 |
|
| Interest earning deposits |
124,969 |
|
|
1,147 |
|
|
3.68 |
|
|
172,723 |
|
|
1,531 |
|
|
3.59 |
|
|
127,687 |
|
|
1,411 |
|
|
4.43 |
|
| Total interest earning assets |
7,517,314 |
|
|
97,674 |
|
|
5.21 |
% |
|
7,087,671 |
|
|
90,675 |
|
|
5.19 |
% |
|
6,286,309 |
|
|
78,500 |
|
|
5.01 |
% |
| Noninterest earning assets |
920,006 |
|
|
|
|
|
|
847,331 |
|
|
|
|
|
|
760,634 |
|
|
|
|
|
| Total assets |
$ |
8,437,320 |
|
|
|
|
|
|
$ |
7,935,002 |
|
|
|
|
|
|
$ |
7,046,943 |
|
|
|
|
|
| Interest Bearing Liabilities: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Certificates of deposit |
$ |
1,090,406 |
|
|
$ |
8,817 |
|
|
3.24 |
% |
|
$ |
1,064,676 |
|
|
$ |
8,814 |
|
|
3.36 |
% |
|
$ |
979,997 |
|
|
$ |
9,349 |
|
|
3.83 |
% |
| Savings accounts |
591,458 |
|
|
348 |
|
|
0.24 |
|
|
540,403 |
|
|
315 |
|
|
0.24 |
|
|
425,703 |
|
|
288 |
|
|
0.27 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
Quarter Ended |
| |
June 30, 2026 |
|
March 31, 2026 |
|
June 30, 2025 |
| |
Average
Balance |
|
Interest
Earned/
Paid |
|
Average
Yield/
Rate (1)
|
|
Average
Balance |
|
Interest
Earned/
Paid |
|
Average
Yield/
Rate (1)
|
|
Average
Balance |
|
Interest
Earned/
Paid |
|
Average
Yield/
Rate (1)
|
|
(Dollars in thousands) |
| Interest bearing demand and money market accounts |
3,444,901 |
|
|
12,226 |
|
|
1.42 |
|
|
3,303,007 |
|
|
11,618 |
|
|
1.43 |
|
|
2,770,352 |
|
|
10,513 |
|
|
1.52 |
|
| Total interest bearing deposits |
5,126,765 |
|
|
21,391 |
|
|
1.67 |
|
|
4,908,086 |
|
|
20,747 |
|
|
1.71 |
|
|
4,176,052 |
|
|
20,150 |
|
|
1.94 |
|
| Junior subordinated debentures |
22,455 |
|
|
431 |
|
|
7.70 |
|
|
22,382 |
|
|
430 |
|
|
7.79 |
|
|
22,165 |
|
|
472 |
|
|
8.54 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Borrowings |
105,131 |
|
|
1,036 |
|
|
3.95 |
|
|
27,111 |
|
|
279 |
|
|
4.17 |
|
|
245,663 |
|
|
2,895 |
|
|
4.73 |
|
| Total interest bearing liabilities |
5,254,351 |
|
|
22,858 |
|
|
1.74 |
% |
|
4,957,579 |
|
|
21,456 |
|
|
1.76 |
% |
|
4,443,880 |
|
|
23,517 |
|
|
2.12 |
% |
| Noninterest demand deposits |
1,973,038 |
|
|
|
|
|
|
1,833,284 |
|
|
|
|
|
|
1,602,987 |
|
|
|
|
|
| Other noninterest bearing liabilities |
97,753 |
|
|
|
|
|
|
95,095 |
|
|
|
|
|
|
120,268 |
|
|
|
|
|
| Stockholders’ equity |
1,112,178 |
|
|
|
|
|
|
1,049,044 |
|
|
|
|
|
|
879,808 |
|
|
|
|
|
| Total liabilities and stockholders’ equity |
$ |
8,437,320 |
|
|
|
|
|
|
$ |
7,935,002 |
|
|
|
|
|
|
$ |
7,046,943 |
|
|
|
|
|
| Net interest income and spread |
|
|
$ |
74,816 |
|
|
3.47 |
% |
|
|
|
$ |
69,219 |
|
|
3.43 |
% |
|
|
|
$ |
54,983 |
|
|
2.89 |
% |
| Net interest margin |
|
|
|
|
3.99 |
% |
|
|
|
|
|
3.96 |
% |
|
|
|
|
|
3.51 |
% |
(1) Annualized; average balances are calculated using daily balances.
(2) Average loans receivable includes loans classified as nonaccrual, which carry a zero yield. Interest earned on loans receivable includes the amortization of net deferred loan fees of $1.1 million, $0.8 million and $0.9 million for the second quarter of 2026, first quarter of 2026 and second quarter of 2025, respectively, and the incremental accretion on purchased loans of $1.8 million, $1.6 million, and $76,000 for the second quarter of 2026, first quarter of 2026 and second quarter of 2025, respectively.
(3) Yields on tax-exempt loans and securities have not been stated on a tax-equivalent basis.
Noninterest Income
Noninterest income increased $612,000 to $9.3 million during the second quarter of 2026 from $8.7 million during the first quarter of 2026. The increase was due primarily to increases in service charges and other fees, card revenue and BOLI income due to an additional month of income from the deposit portfolio and bank owned life insurance ("BOLI") acquired from Olympic.
Noninterest income increased $7.8 million during the second quarter of 2026 from the same period in 2025 due primarily to a $6.9 million loss recognized in the second quarter of 2025 resulting from the sale of investment securities as part of the strategic repositioning of the Company's balance sheet, and due to increases in service charges and other fees, card revenue, and BOLI income due to income from the deposit portfolio and BOLI acquired from Olympic.
The following table presents the key components of noninterest income and the change for the periods indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Quarter Ended |
|
Quarter Over Quarter Change |
|
Prior Year
Quarter Change
|
|
June 30,
2026 |
|
March 31,
2026 |
|
June 30,
2025 |
|
$ |
|
% |
|
$ |
|
% |
|
(Dollars in thousands) |
| Service charges and other fees |
$ |
3,592 |
|
|
$ |
3,367 |
|
|
$ |
2,932 |
|
|
$ |
225 |
|
|
6.7 |
% |
|
$ |
660 |
|
|
22.5 |
% |
| Card revenue |
2,595 |
|
|
2,103 |
|
|
2,008 |
|
|
492 |
|
|
23.4 |
|
|
587 |
|
|
29.2 |
|
| Loss on sale of investment securities |
(217) |
|
|
— |
|
|
(6,854) |
|
|
(217) |
|
|
— |
|
|
6,637 |
|
|
96.8 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Interest rate swap fees |
3 |
|
|
— |
|
|
19 |
|
|
3 |
|
|
— |
|
|
(16) |
|
|
(84.2) |
|
BOLI income |
1,485 |
|
|
1,119 |
|
|
1,280 |
|
|
366 |
|
|
32.7 |
|
|
205 |
|
|
16.0 |
|
| Gain on sale of other assets, net |
— |
|
|
— |
|
|
5 |
|
|
— |
|
|
— |
|
|
(5) |
|
|
(100.0) |
|
| Other income |
1,853 |
|
|
2,110 |
|
|
2,127 |
|
|
(257) |
|
|
(12.2) |
|
|
(274) |
|
|
(12.9) |
|
Total noninterest income (loss) |
$ |
9,311 |
|
|
$ |
8,699 |
|
|
$ |
1,517 |
|
|
$ |
612 |
|
|
7.0 |
% |
|
$ |
7,794 |
|
|
513.8 |
% |
Noninterest Expense
Noninterest expense increased $7.8 million, or 13.7%, to $64.3 million during the second quarter of 2026, compared to $56.6 million in the first quarter of 2026. The increase was primarily due to one additional month of expense related to the Merger, including increases related to compensation and employee benefits from increased headcount, occupancy and equipment expense primarily due to additional rent expense, and additional data processing expense due to an increase in transactional accounts and balances.
Merger related expenses, which consisted of severance expense, professional fees, core conversion costs, and contract termination costs incurred in the second quarter of 2026 were $7.5 million compared to $5.2 million in the first quarter of 2026.
The following table presents merger related expenses included in noninterest expense and the change for the periods indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Quarter Ended |
Change |
|
June 30,
2026 |
|
March 31,
2026 |
|
$ |
|
(Dollars in thousands) |
| Compensation and employee benefits |
$ |
1,481 |
|
|
$ |
2,733 |
|
|
$ |
(1,252) |
|
|
|
|
|
|
|
| Data processing |
4,924 |
|
|
491 |
|
|
4,433 |
|
|
|
|
|
|
|
| Professional services |
128 |
|
|
1,868 |
|
|
(1,740) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Other expense |
960 |
|
|
86 |
|
|
874 |
|
| Total noninterest expense |
$ |
7,493 |
|
|
$ |
5,178 |
|
|
$ |
2,315 |
|
Noninterest expense also increased due to the increase in the amortization of intangible assets of $0.9 million, as a result of one additional month of amortization related to the acquisition of Olympic.
Noninterest expense increased $23.2 million, or 56.6%, during the second quarter of 2026 compared to the same period in 2025 due primarily to an increase in expenses related to the Merger and the addition of Olympic operations.
The following table presents the key components of noninterest expense and the change for the periods indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Quarter Ended |
|
Quarter Over Quarter Change |
|
Prior Year Quarter Change |
|
June 30,
2026 |
|
March 31,
2026 |
|
June 30,
2025 |
|
$ |
|
% |
|
$ |
|
% |
|
(Dollars in thousands) |
| Compensation and employee benefits |
$ |
35,769 |
|
|
$ |
33,972 |
|
|
$ |
25,467 |
|
|
$ |
1,797 |
|
|
5.3 |
% |
|
$ |
10,302 |
|
|
40.5 |
% |
| Occupancy and equipment |
6,014 |
|
|
5,330 |
|
|
4,840 |
|
|
684 |
|
|
12.8 |
|
|
1,174 |
|
|
24.3 |
|
| Data processing |
10,218 |
|
|
5,093 |
|
|
3,666 |
|
|
5,125 |
|
|
100.6 |
|
|
6,552 |
|
|
178.7 |
|
| Marketing |
437 |
|
|
383 |
|
|
336 |
|
|
54 |
|
|
14.1 |
|
|
101 |
|
|
30.1 |
|
| Professional services |
939 |
|
|
2,842 |
|
|
1,122 |
|
|
(1,903) |
|
|
(67.0) |
|
|
(183) |
|
|
(16.3) |
|
State/municipal business and use taxes |
1,801 |
|
|
1,674 |
|
|
1,205 |
|
|
127 |
|
|
7.6 |
|
|
596 |
|
|
49.5 |
|
| Federal deposit insurance premium |
881 |
|
|
1,037 |
|
|
810 |
|
|
(156) |
|
|
(15.0) |
|
|
71 |
|
|
8.8 |
|
| Other real estate owned, net |
44 |
|
|
4 |
|
|
— |
|
|
40 |
|
|
1000.0 |
|
|
44 |
|
|
— |
|
| Amortization of intangible assets |
2,957 |
|
|
2,058 |
|
|
302 |
|
|
899 |
|
|
43.7 |
|
|
2,655 |
|
|
879.1 |
|
| Other expense |
5,264 |
|
|
4,158 |
|
|
3,337 |
|
|
1,106 |
|
|
26.6 |
|
|
1,927 |
|
|
57.7 |
|
| Total noninterest expense |
$ |
64,324 |
|
|
$ |
56,551 |
|
|
$ |
41,085 |
|
|
$ |
7,773 |
|
|
13.7 |
% |
|
$ |
23,239 |
|
|
56.6 |
% |
Income Tax Expense
Income tax expense decreased $272,000 in the second quarter of 2026, compared to the first quarter of 2026 due to lower pre-tax income during the second quarter of 2026.
Income tax expense increased $934,000 in the second quarter of 2026, compared to the same period in 2025 due primarily to higher pre-tax income during the second quarter of 2026.
The following table presents the income tax expense and related metrics and the change for the periods indicated:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Quarter Ended |
|
Change |
|
June 30,
2026 |
|
March 31,
2026 |
|
June 30,
2025 |
|
Quarter Over Quarter |
Prior Year Quarter |
|
(Dollars in thousands) |
| Income before income taxes |
$ |
20,724 |
|
|
$ |
22,397 |
|
|
$ |
14,459 |
|
|
$ |
(1,673) |
|
|
$ |
6,265 |
|
| Income tax expense |
$ |
3,178 |
|
|
$ |
3,450 |
|
|
$ |
2,244 |
|
|
$ |
(272) |
|
|
$ |
934 |
|
| Effective income tax rate |
15.3 |
% |
|
15.4 |
% |
|
15.5 |
% |
|
(0.1) |
% |
|
(0.2) |
% |
Dividends
On July 22, 2026, the Company’s Board of Directors declared a quarterly cash dividend of $0.25 per share. The dividend is payable on August 19, 2026 to shareholders of record as of the close of business on August 5, 2026.
Earnings Conference Call
The Company will hold a telephone conference call to discuss second quarter of 2026 earnings on Thursday, July 23, 2026 at 9:00 a.m. Pacific time. Participants may register for the call at the following link: https://registrations.events/direct/Q4I5378922. To access the call via telephone, please dial (888) 500-3691 -- access code 53789 a few minutes prior to 9:00 a.m. Pacific time. The conference call will be recorded and will be available for replay through August 6, 2026 at the following link: https://registrations.events/direct/Q4I5378922
About Heritage Financial Corporation
Heritage Financial Corporation (the “Company”) is an Olympia, Washington-based bank holding company for Heritage Bank, a full-service commercial bank and its sole wholly-owned banking subsidiary. Heritage Bank has a network of branches and loan production offices in Washington, Oregon and Idaho. Heritage Bank does business under the Whidbey Island Bank name on Whidbey Island, Washington and the Kitsap Bank name at certain branches acquired through the acquisition of Olympic Bancorp, Inc. The Company's stock is traded on the Nasdaq Global Select Market under the symbol “HFWA.” More information about the Company can be found on its website at www.hf-wa.com and more information about Heritage Bank can be found on its website at www.heritagebanknw.com.
Contact
Bryan McDonald, President and Chief Executive Officer, (360) 943-1500
Don Hinson, Executive Vice President and Chief Financial Officer, (360) 943-1500
Forward-Looking Statements
This press release may contain "forward-looking statements" within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. The Company intends such forward-looking statements to be covered by the safe harbor provisions for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. Such statements often include words such as "believes," "expects," "anticipates," "estimates," “forecasts,” "intends," “plans,” “targets,” “potentially,” “probably,” “projects,” “outlook” or similar expressions or future or conditional verbs such as “may,” "will," “should,” "would," and "could," as well as the negative of such words. Forward-looking statements are not historical facts but instead represent management's current expectations and forecasts regarding future events, many of which are inherently uncertain and outside of our control. Actual results may differ, possibly materially, from those currently expected or projected in these forward-looking statements. These forward-looking statements are subject to known and unknown risks, uncertainties and other factors that could cause actual results to differ materially from the results anticipated or implied by forward-looking statements. Factors that could cause our actual results to differ materially from those described in the forward-looking statements include, but are not limited to, the following: potential adverse impacts to economic conditions nationally or in our local market areas, other markets where we have lending relationships, or other aspects of our business operations or financial markets, including, without limitation, as a result of credit quality deterioration, pronounced and sustained reductions in real estate market values, employment levels, labor shortages and a potential recession or slowed economic growth; changes in the interest rate environment, which could adversely affect our revenues and expenses, the value of assets and obligations, and the availability and cost of capital and liquidity; the level and impact of inflation and the current and future monetary policies of the Board of Governors of the Federal Reserve System and executive orders in response thereto; previous and potential future disruptions, security breaches, insider fraud, cybersecurity incidents or other adverse events, failures or interruptions in, or attacks on, our information technology systems or on the third-party vendors who perform critical processing functions for our business, including sophisticated attacks using artificial intelligence and similar tools; legislative or regulatory changes that adversely affect our business, including changes in banking, securities, and tax laws, in regulatory policies and principles, or the interpretation and prioritization of such rules and regulations; effects on the U.S. economy resulting from actions taken by the federal government, including the threat or implementation of tariffs, immigration enforcement and changes in foreign policy; the effects of acts of war or terrorism, foreign relations, military conflicts, including the wars in Iran and Ukraine, ongoing conflicts in the Middle East, and other international military conflicts that can increase levels of political and economic unpredictability, contribute to rising energy and commodity prices, affect global supply chains, increase the volatility of financial markets, and other matters beyond our control; effects of other external events on our business and the businesses of our clients; credit and interest rate risks associated with our business, including our customers’ borrowing, repayment, and deposit practices; fluctuations in deposits and the concentration of large deposits from certain customers, who have deposit balances above current FDIC insurance limits; liquidity issues, including our ability to borrow funds or raise additional capital, if necessary; fluctuations in the value of our investment securities; credit risks and risks from concentrations (including by type of geographic area, collateral and industry) within our loan portfolio; the effectiveness of our risk management framework; rapid technological changes implemented by us and other parties, including third-party vendors, which may be more difficult to implement or more expensive than anticipated or which may have unforeseen consequences to us and our customers, including the development and implementation of tools incorporating artificial intelligence; increased competition in the financial services industry from non-banks such as credit unions and financial technology companies, including digital asset service providers; our ability to adapt successfully to technological changes to compete effectively in the marketplace, including as a result of competition from other commercial banks, mortgage banking firms, credit unions, securities brokerage firms, insurance companies, and financial technology companies; emerging issues related to the development and use of artificial intelligence that could give rise to legal or regulatory action, damage our reputation or otherwise materially harm our business or customers; our ability to implement our organic and acquisition growth strategies, including the recent acquisition of Olympic, and our ability to successfully integrate Olympic's customers and operations following the acquisition; effects of critical accounting policies and judgments, including the use of estimates in determining fair value of certain of our assets, which estimates may prove to be incorrect and result in significant declines in valuation; the commencement, costs, effects and outcome of litigation and other legal proceedings and regulatory actions against us or to which we may become subject, including in connection with prior
acquisitions; potential impairment to the goodwill we recorded in connection with our past acquisitions, including as a result of the recent acquisition of Olympic; loss of, or inability to attract, key personnel; our ability to successfully integrate any assets, liabilities, customers, systems, and management personnel we may acquire, including as a result of the recent acquisition of Olympic, into our operations and our ability to realize related revenue synergies and cost savings within expected time frames or at all, and any goodwill charges related thereto and costs or difficulties relating to integration matters, including but not limited to customer and employee retention, which might be greater than expected; the effects of climate change, severe weather events, natural disasters, pandemics, epidemics and other public health crises; the impact of bank failures or adverse developments at other banks and related negative publicity about the banking industry in general on investor and depositor sentiment regarding the stability and liquidity of banks; the extensive regulatory framework that applies to us; the overall health of local and national real estate markets; the level of nonperforming assets on our balance sheet; risks related to acquiring assets in or entering markets in which we have not previously operated and may not be familiar; changes in consumer spending, borrowing and saving habits; the availability of future equity and debt issuances and other capital raising opportunities on favorable terms; our success at managing and responding to the risks involved in the foregoing items; and other factors described in our latest Annual Report on Form 10-K and Quarterly Reports on Form 10-Q and other documents filed with or furnished to the Securities and Exchange Commission (the “SEC”) which are available on our website at www.hf-wa.com and on the SEC's website at www.sec.gov. We caution readers not to place undue reliance on any forward-looking statements. Moreover, any of the forward-looking statements that we make in this press release or the documents we file with or furnish to the SEC are based only on information then actually known to us and upon management's beliefs and assumptions at the time they are made which may turn out to be wrong because of inaccurate assumptions we might make, because of the factors described above or because of other factors that we cannot foresee. Forward-looking statements speak only as of the date they are made, and we do not undertake and specifically disclaim any obligation to revise any forward-looking statements to reflect the occurrence of anticipated or unanticipated events or circumstances after the date of such statements.
HERITAGE FINANCIAL CORPORATION
CONDENSED CONSOLIDATED STATEMENTS OF FINANCIAL CONDITION (Unaudited)
(Dollars in thousands, except shares)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
June 30,
2026 |
|
March 31,
2026 |
|
December 31,
2025 |
| Assets |
|
|
|
|
|
| Cash on hand and in banks |
$ |
102,555 |
|
|
$ |
98,263 |
|
|
$ |
52,587 |
|
| Interest earning deposits |
101,820 |
|
|
169,880 |
|
|
180,502 |
|
| Cash and cash equivalents |
204,375 |
|
|
268,143 |
|
|
233,089 |
|
Investment securities available for sale, at fair value (amortized cost of $1,020,125, $1,043,442 and $647,505, respectively) |
971,437 |
|
|
1,001,148 |
|
|
607,522 |
|
Investment securities held to maturity, at amortized cost (fair value of $607,782, $617,490 and $625,287, respectively) |
661,839 |
|
|
668,263 |
|
|
674,107 |
|
| Total investment securities |
1,633,276 |
|
|
1,669,411 |
|
|
1,281,629 |
|
|
|
|
|
|
|
| Loans receivable |
5,747,741 |
|
|
5,722,238 |
|
|
4,783,266 |
|
| Allowance for credit losses on loans |
(59,473) |
|
|
(60,551) |
|
|
(52,584) |
|
| Loans receivable, net |
5,688,268 |
|
|
5,661,687 |
|
|
4,730,682 |
|
| Other real estate owned |
755 |
|
|
755 |
|
|
— |
|
| Premises and equipment, net |
98,034 |
|
|
100,509 |
|
|
74,690 |
|
| Federal Home Loan Bank stock, at cost |
12,653 |
|
|
6,072 |
|
|
5,163 |
|
BOLI |
146,350 |
|
|
144,865 |
|
|
105,974 |
|
| Accrued interest receivable |
23,056 |
|
|
24,278 |
|
|
19,280 |
|
| Prepaid expenses and other assets |
297,501 |
|
|
293,429 |
|
|
273,925 |
|
| Other intangible assets, net |
47,269 |
|
|
50,226 |
|
|
1,979 |
|
| Goodwill |
279,029 |
|
|
279,029 |
|
|
240,939 |
|
| Total assets |
$ |
8,430,566 |
|
|
$ |
8,498,404 |
|
|
$ |
6,967,350 |
|
|
|
|
|
|
|
| Liabilities and Stockholders' Equity |
|
|
|
|
|
Non-interest bearing deposits |
$ |
1,972,702 |
|
|
$ |
2,066,383 |
|
|
$ |
1,597,650 |
|
Interest bearing deposits |
5,066,004 |
|
|
5,182,154 |
|
|
4,322,549 |
|
| Total deposits |
7,038,706 |
|
|
7,248,537 |
|
|
5,920,199 |
|
| Borrowings |
166,250 |
|
|
20,000 |
|
|
20,000 |
|
| Junior subordinated debentures |
22,497 |
|
|
22,424 |
|
|
22,350 |
|
|
|
|
|
|
|
| Accrued expenses and other liabilities |
93,421 |
|
|
91,752 |
|
|
83,297 |
|
| Total liabilities |
7,320,874 |
|
|
7,382,713 |
|
|
6,045,846 |
|
|
|
|
|
|
|
| Common stock |
707,889 |
|
|
716,432 |
|
|
531,100 |
|
| Retained earnings |
439,799 |
|
|
432,255 |
|
|
421,619 |
|
| Accumulated other comprehensive loss, net |
(37,996) |
|
|
(32,996) |
|
|
(31,215) |
|
| Total stockholders' equity |
1,109,692 |
|
|
1,115,691 |
|
|
921,504 |
|
| Total liabilities and stockholders' equity |
$ |
8,430,566 |
|
|
$ |
8,498,404 |
|
|
$ |
6,967,350 |
|
|
|
|
|
|
|
| Shares outstanding |
40,906,122 |
|
|
41,249,873 |
|
|
33,963,500 |
|
HERITAGE FINANCIAL CORPORATION
CONDENSED CONSOLIDATED STATEMENTS OF INCOME (Unaudited)
(Dollars in thousands, except per share amounts)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Quarter Ended |
|
Six Months Ended |
|
June 30,
2026 |
|
March 31,
2026 |
|
June 30,
2025 |
|
June 30,
2026 |
|
June 30,
2025 |
| Interest Income |
|
|
|
|
|
|
|
|
|
| Interest and fees on loans |
$ |
81,935 |
|
|
$ |
76,445 |
|
|
$ |
65,373 |
|
|
$ |
158,380 |
|
|
$ |
129,809 |
|
| Taxable interest on investment securities |
14,464 |
|
|
12,570 |
|
|
11,579 |
|
|
27,034 |
|
|
23,318 |
|
| Nontaxable interest on investment securities |
128 |
|
|
129 |
|
|
137 |
|
|
257 |
|
|
276 |
|
| Interest on interest earning deposits |
1,147 |
|
|
1,531 |
|
|
1,411 |
|
|
2,678 |
|
|
2,463 |
|
| Total interest income |
97,674 |
|
|
90,675 |
|
|
78,500 |
|
|
188,349 |
|
|
155,866 |
|
| Interest Expense |
|
|
|
|
|
|
|
|
|
| Deposits |
21,391 |
|
|
20,747 |
|
|
20,150 |
|
|
42,138 |
|
|
39,639 |
|
| Junior subordinated debentures |
431 |
|
|
430 |
|
|
472 |
|
|
861 |
|
|
943 |
|
|
|
|
|
|
|
|
|
|
|
| Borrowings |
1,036 |
|
|
279 |
|
|
2,895 |
|
|
1,315 |
|
|
6,611 |
|
| Total interest expense |
22,858 |
|
|
21,456 |
|
|
23,517 |
|
|
44,314 |
|
|
47,193 |
|
| Net interest income |
74,816 |
|
|
69,219 |
|
|
54,983 |
|
|
144,035 |
|
|
108,673 |
|
| (Reversal of) provision for credit losses |
(921) |
|
|
(1,030) |
|
|
956 |
|
|
(1,951) |
|
|
1,007 |
|
| Net interest income after (reversal of) provision for credit losses |
75,737 |
|
|
70,249 |
|
|
54,027 |
|
|
145,986 |
|
|
107,666 |
|
| Noninterest Income |
|
|
|
|
|
|
|
|
|
| Service charges and other fees |
3,592 |
|
|
3,367 |
|
|
2,932 |
|
|
6,959 |
|
|
5,907 |
|
| Card revenue |
2,595 |
|
|
2,103 |
|
|
2,008 |
|
|
4,698 |
|
|
3,741 |
|
| Loss on sale of investment securities, net |
(217) |
|
|
— |
|
|
(6,854) |
|
|
(217) |
|
|
(10,741) |
|
|
|
|
|
|
|
|
|
|
|
| Interest rate swap fees |
3 |
|
|
— |
|
|
19 |
|
|
3 |
|
|
19 |
|
BOLI income |
1,485 |
|
|
1,119 |
|
|
1,280 |
|
|
2,604 |
|
|
2,198 |
|
| Gain on sale of other assets, net |
— |
|
|
— |
|
|
5 |
|
|
— |
|
|
8 |
|
| Other income |
1,853 |
|
|
2,110 |
|
|
2,127 |
|
|
3,963 |
|
|
4,288 |
|
| Total noninterest income (loss) |
9,311 |
|
|
8,699 |
|
|
1,517 |
|
|
18,010 |
|
|
5,420 |
|
| Noninterest Expense |
|
|
|
|
|
|
|
|
|
| Compensation and employee benefits |
35,769 |
|
|
33,972 |
|
|
25,467 |
|
|
69,741 |
|
|
51,266 |
|
| Occupancy and equipment |
6,014 |
|
|
5,330 |
|
|
4,840 |
|
|
11,344 |
|
|
9,766 |
|
| Data processing |
10,218 |
|
|
5,093 |
|
|
3,666 |
|
|
15,311 |
|
|
7,563 |
|
| Marketing |
437 |
|
|
383 |
|
|
336 |
|
|
820 |
|
|
671 |
|
| Professional services |
939 |
|
|
2,842 |
|
|
1,122 |
|
|
3,781 |
|
|
1,856 |
|
| State/municipal business and use taxes |
1,801 |
|
|
1,674 |
|
|
1,205 |
|
|
3,475 |
|
|
2,425 |
|
| Federal deposit insurance premium |
881 |
|
|
1,037 |
|
|
810 |
|
|
1,918 |
|
|
1,622 |
|
| Other real estate owned, net |
44 |
|
|
4 |
|
|
— |
|
|
48 |
|
|
— |
|
| Amortization of intangible assets |
2,957 |
|
|
2,058 |
|
|
302 |
|
|
5,015 |
|
|
605 |
|
| Other expense |
5,264 |
|
|
4,158 |
|
|
3,337 |
|
|
9,422 |
|
|
6,694 |
|
| Total noninterest expense |
64,324 |
|
|
56,551 |
|
|
41,085 |
|
|
120,875 |
|
|
82,468 |
|
| Income before income taxes |
20,724 |
|
|
22,397 |
|
|
14,459 |
|
|
43,121 |
|
|
30,618 |
|
| Income tax expense |
3,178 |
|
|
3,450 |
|
|
2,244 |
|
|
6,628 |
|
|
4,492 |
|
| Net income |
$ |
17,546 |
|
|
$ |
18,947 |
|
|
$ |
12,215 |
|
|
$ |
36,493 |
|
|
$ |
26,126 |
|
|
|
|
|
|
|
|
|
|
|
| Basic earnings per share |
$ |
0.42 |
|
|
$ |
0.49 |
|
|
$ |
0.36 |
|
|
$ |
0.91 |
|
|
$ |
0.77 |
|
| Diluted earnings per share |
$ |
0.42 |
|
|
$ |
0.48 |
|
|
$ |
0.36 |
|
|
$ |
0.90 |
|
|
$ |
0.76 |
|
| Dividends declared per share |
$ |
0.24 |
|
|
$ |
0.24 |
|
|
$ |
0.24 |
|
|
$ |
0.48 |
|
|
$ |
0.48 |
|
| Average shares outstanding - basic |
41,079,781 |
|
38,683,375 |
|
34,028,592 |
|
39,888,198 |
|
34,037,067 |
| Average shares outstanding - diluted |
41,541,763 |
|
39,104,569 |
|
34,446,710 |
|
40,364,364 |
|
34,512,260 |
HERITAGE FINANCIAL CORPORATION
FINANCIAL STATISTICS (Unaudited)
(Dollars in thousands)
Average Balances, Yields, and Rates Paid:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Six Months Ended June 30, |
|
2026 |
|
2025 |
|
Average
Balance |
|
Interest
Earned/
Paid |
|
Average
Yield/
Rate (1)
|
|
Average
Balance |
|
Interest
Earned/
Paid |
|
Average
Yield/
Rate (1)
|
| Interest Earning Assets: |
|
|
|
|
|
|
|
|
|
|
|
Loans receivable(2)(3)
|
$ |
5,577,841 |
|
|
$ |
158,380 |
|
|
5.73 |
% |
|
$ |
4,781,167 |
|
|
$ |
129,809 |
|
|
5.48 |
% |
| Taxable securities |
1,561,574 |
|
|
27,034 |
|
|
3.49 |
|
|
1,401,226 |
|
|
23,318 |
|
|
3.36 |
|
Nontaxable securities(3)
|
15,550 |
|
|
257 |
|
|
3.33 |
|
|
15,489 |
|
|
276 |
|
|
3.59 |
|
| Interest earning deposits |
148,715 |
|
|
2,678 |
|
|
3.63 |
|
|
111,990 |
|
|
2,463 |
|
|
4.44 |
|
| Total interest earning assets |
7,303,680 |
|
|
188,349 |
|
|
5.20 |
% |
|
6,309,872 |
|
|
155,866 |
|
|
4.98 |
% |
| Noninterest earning assets |
883,869 |
|
|
|
|
|
|
765,058 |
|
|
|
|
|
| Total assets |
$ |
8,187,549 |
|
|
|
|
|
|
$ |
7,074,930 |
|
|
|
|
|
| Interest Bearing Liabilities: |
|
|
|
|
|
|
|
|
|
|
|
| Certificates of deposit |
$ |
1,077,612 |
|
|
$ |
17,631 |
|
|
3.30 |
% |
|
$ |
980,166 |
|
|
$ |
19,019 |
|
|
3.91 |
% |
| Savings accounts |
566,072 |
|
|
663 |
|
|
0.24 |
|
|
426,010 |
|
|
581 |
|
|
0.28 |
|
| Interest bearing demand and money market accounts |
3,374,345 |
|
|
23,844 |
|
|
1.42 |
|
|
2,738,197 |
|
|
20,039 |
|
|
1.48 |
|
| Total interest bearing deposits |
5,018,029 |
|
|
42,138 |
|
|
1.69 |
|
|
4,144,373 |
|
|
39,639 |
|
|
1.93 |
|
| Junior subordinated debentures |
22,419 |
|
|
861 |
|
|
7.74 |
|
|
22,126 |
|
|
943 |
|
|
8.59 |
|
|
|
|
|
|
|
|
|
|
|
|
|
| Borrowings |
66,337 |
|
|
1,315 |
|
|
4.00 |
|
|
282,768 |
|
|
6,611 |
|
|
4.71 |
|
| Total interest bearing liabilities |
5,106,785 |
|
|
44,314 |
|
|
1.75 |
% |
|
4,449,267 |
|
|
47,193 |
|
|
2.14 |
% |
| Noninterest demand deposits |
1,903,547 |
|
|
|
|
|
|
1,617,050 |
|
|
|
|
|
| Other noninterest bearing liabilities |
96,432 |
|
|
|
|
|
|
135,358 |
|
|
|
|
|
| Stockholders’ equity |
1,080,785 |
|
|
|
|
|
|
873,255 |
|
|
|
|
|
| Total liabilities and stockholders’ equity |
$ |
8,187,549 |
|
|
|
|
|
|
$ |
7,074,930 |
|
|
|
|
|
| Net interest income and spread |
|
|
$ |
144,035 |
|
|
3.45 |
% |
|
|
|
$ |
108,673 |
|
|
2.84 |
% |
| Net interest margin |
|
|
|
|
3.98 |
% |
|
|
|
|
|
3.47 |
% |
(1) Annualized; average balances are calculated using daily balances.
(2) Average loans receivable includes loans classified as nonaccrual, which carry a zero yield. Interest earned on loans receivable includes the amortization of net deferred loan fees of $1.9 million and $1.7 million for the six months ended June 30, 2026 and 2025, respectively, and incremental accretion on purchased loans of $3.4 million and $229,000, for the six months ended June 30, 2026 and 2025, respectively.
(3) Yields on tax-exempt loans and securities have not been stated on a tax-equivalent basis.
HERITAGE FINANCIAL CORPORATION
FINANCIAL STATISTICS (Unaudited)
(Dollars in thousands)
Nonperforming Assets and Credit Quality Metrics:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Quarter Ended |
|
Six Months Ended |
|
June 30,
2026 |
|
March 31,
2026 |
|
June 30,
2025 |
|
June 30,
2026 |
|
June 30,
2025 |
| Allowance for Credit Losses on Loans: |
|
|
|
|
| Balance, beginning of period |
$ |
60,551 |
|
|
$ |
52,584 |
|
|
$ |
52,160 |
|
|
$ |
52,584 |
|
|
$ |
52,468 |
|
| Initial ACL recorded for PSL and PCD loans acquired during the period |
— |
|
|
9,339 |
|
|
— |
|
|
9,339 |
|
|
— |
|
| (Reversal of) provision for credit losses on loans |
(844) |
|
|
(820) |
|
|
863 |
|
|
(1,664) |
|
|
854 |
|
| Charge-offs: |
|
|
|
|
|
|
|
|
|
| Commercial business |
(180) |
|
|
(400) |
|
|
(454) |
|
|
(580) |
|
|
(676) |
|
Residential real estate |
— |
|
|
(64) |
|
|
— |
|
|
(64) |
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
| Consumer |
(89) |
|
|
(119) |
|
|
(104) |
|
|
(208) |
|
|
(258) |
|
| Total charge-offs |
(269) |
|
|
(583) |
|
|
(558) |
|
|
(852) |
|
|
(934) |
|
| Recoveries: |
|
|
|
|
|
|
|
|
|
| Commercial business |
4 |
|
|
4 |
|
|
18 |
|
|
8 |
|
|
44 |
|
Residential real estate |
2 |
|
|
— |
|
|
— |
|
|
2 |
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
| Consumer |
29 |
|
|
27 |
|
|
46 |
|
|
56 |
|
|
97 |
|
| Total recoveries |
35 |
|
|
31 |
|
|
64 |
|
|
66 |
|
|
141 |
|
| Net (charge-offs) recoveries |
(234) |
|
|
(552) |
|
|
(494) |
|
|
(786) |
|
|
(793) |
|
| Balance, end of period |
$ |
59,473 |
|
|
$ |
60,551 |
|
|
$ |
52,529 |
|
|
$ |
59,473 |
|
|
$ |
52,529 |
|
| Net charge-offs on loans to average loans receivable annualized |
0.02 |
% |
|
0.04 |
% |
|
0.04 |
% |
|
0.03 |
% |
|
0.03 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
June 30,
2026 |
|
March 31,
2026 |
|
December 31,
2025 |
| Nonperforming Assets: |
|
|
|
|
|
| Nonaccrual loans: |
|
|
|
|
|
| Commercial business |
$ |
7,437 |
|
|
$ |
7,454 |
|
|
$ |
6,886 |
|
Residential real estate |
1,338 |
|
|
583 |
|
|
1,196 |
|
| Real estate construction and land development |
6,420 |
|
|
6,514 |
|
|
12,408 |
|
| Consumer |
315 |
|
|
407 |
|
|
486 |
|
| Total nonaccrual loans |
15,510 |
|
|
14,958 |
|
|
20,976 |
|
Accruing loans past due 90 days or more |
— |
|
|
67 |
|
|
194 |
|
Total nonperforming loans |
15,510 |
|
|
15,025 |
|
|
21,170 |
|
| Other real estate owned |
755 |
|
|
755 |
|
|
— |
|
| Nonperforming assets |
$ |
16,265 |
|
|
$ |
15,780 |
|
|
$ |
21,170 |
|
|
|
|
|
|
|
| ACL on loans to: |
|
|
|
|
|
| Loans receivable |
1.03 |
% |
|
1.06 |
% |
|
1.10 |
% |
| Nonaccrual loans |
383.45 |
% |
|
404.81 |
% |
|
250.69 |
% |
Nonaccrual loans to loans receivable |
0.27 |
% |
|
0.26 |
% |
|
0.44 |
% |
Nonperforming loans to loans receivable |
0.27 |
% |
|
0.26 |
% |
|
0.44 |
% |
| Nonperforming assets to total assets |
0.19 |
% |
|
0.19 |
% |
|
0.30 |
% |
HERITAGE FINANCIAL CORPORATION
QUARTERLY FINANCIAL STATISTICS (Unaudited)
(Dollars in thousands, except per share amounts)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
Quarter Ended |
| |
June 30,
2026 |
|
March 31,
2026 |
|
December 31,
2025 |
|
September 30,
2025 |
|
June 30,
2025 |
| Earnings: |
|
|
|
|
|
|
|
|
|
| Net interest income |
$ |
74,816 |
|
|
$ |
69,219 |
|
|
$ |
58,361 |
|
|
$ |
57,371 |
|
|
$ |
54,983 |
|
| (Reversal of) provision for credit losses |
(921) |
|
|
(1,030) |
|
|
(814) |
|
|
1,775 |
|
|
956 |
|
| Noninterest income |
9,311 |
|
|
8,699 |
|
|
7,987 |
|
|
8,325 |
|
|
1,517 |
|
| Noninterest expense |
64,324 |
|
|
56,551 |
|
|
41,483 |
|
|
41,615 |
|
|
41,085 |
|
| Net income |
17,546 |
|
|
18,947 |
|
|
22,237 |
|
|
19,169 |
|
|
12,215 |
|
| Basic earnings per share |
$ |
0.42 |
|
|
$ |
0.49 |
|
|
$ |
0.66 |
|
|
$ |
0.56 |
|
|
$ |
0.36 |
|
| Diluted earnings per share |
$ |
0.42 |
|
|
$ |
0.48 |
|
|
$ |
0.65 |
|
|
$ |
0.55 |
|
|
$ |
0.36 |
|
Adjusted diluted earnings per share (1)
|
$ |
0.57 |
|
|
$ |
0.59 |
|
|
$ |
0.66 |
|
|
$ |
0.56 |
|
|
$ |
0.53 |
|
| Average Balances: |
|
|
|
|
|
|
|
|
|
Loans receivable |
$ |
5,740,927 |
|
|
$ |
5,412,943 |
|
|
$ |
4,770,300 |
|
|
$ |
4,762,648 |
|
|
$ |
4,768,558 |
|
| Total investment securities |
1,651,418 |
|
|
1,502,005 |
|
|
1,301,526 |
|
|
1,329,616 |
|
|
1,390,064 |
|
| Total interest earning assets |
7,517,314 |
|
|
7,087,671 |
|
|
6,223,303 |
|
|
6,258,446 |
|
|
6,286,309 |
|
| Total assets |
8,437,320 |
|
|
7,935,002 |
|
|
6,954,110 |
|
|
7,006,140 |
|
|
7,046,943 |
|
| Total interest bearing deposits |
5,126,765 |
|
|
4,908,086 |
|
|
4,250,589 |
|
|
4,217,041 |
|
|
4,176,052 |
|
| Total noninterest demand deposits |
1,973,038 |
|
|
1,833,284 |
|
|
1,635,539 |
|
|
1,625,945 |
|
|
1,602,987 |
|
| Stockholders' equity |
1,112,178 |
|
|
1,049,044 |
|
|
911,454 |
|
|
892,280 |
|
|
879,808 |
|
| Financial Ratios: |
|
|
|
|
|
|
|
|
|
Return on average assets (2)
|
0.83 |
% |
|
0.97 |
% |
|
1.27 |
% |
|
1.09 |
% |
|
0.70 |
% |
Adjusted return on average assets (1)(2)
|
1.12 |
% |
|
1.18 |
% |
|
1.29 |
% |
|
1.11 |
% |
|
1.03 |
% |
Return on average common equity (2)
|
6.33 |
|
|
7.32 |
|
|
9.68 |
|
|
8.52 |
|
|
5.57 |
|
Return on average tangible common equity (1)(2)
|
10.17 |
|
|
11.14 |
|
|
13.33 |
|
|
11.86 |
|
|
7.85 |
|
Adjusted return on average tangible common equity (1)(2)
|
13.29 |
|
|
13.36 |
|
|
13.51 |
|
|
12.16 |
|
|
11.59 |
|
| Efficiency ratio |
76.5 |
|
|
72.6 |
|
|
62.5 |
|
|
63.3 |
|
|
72.7 |
|
Adjusted efficiency ratio (1)
|
63.9 |
|
|
63.3 |
|
|
61.5 |
|
|
61.9 |
|
|
64.4 |
|
Noninterest expense to average total assets (2)
|
3.06 |
|
|
2.89 |
|
|
2.37 |
|
|
2.36 |
|
|
2.34 |
|
Adjusted noninterest expense to average total assets(1)(2)
|
2.56 |
|
|
2.52 |
|
|
2.33 |
|
|
2.30 |
|
|
2.32 |
|
Net interest spread (2)
|
3.47 |
|
|
3.43 |
|
|
3.15 |
|
|
3.03 |
|
|
2.89 |
|
Net interest margin (2)
|
3.99 |
|
|
3.96 |
|
|
3.72 |
|
|
3.64 |
|
|
3.51 |
|
(1) Represents a non-GAAP financial measure. See “Non-GAAP Financial Measures” section for a reconciliation to the comparable GAAP financial measure.
(2) Annualized.
HERITAGE FINANCIAL CORPORATION
QUARTERLY FINANCIAL STATISTICS (Unaudited)
(Dollars in thousands, except per share amounts)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
As of or for the Quarter Ended |
| |
June 30,
2026 |
|
March 31,
2026 |
|
December 31,
2025 |
|
September 30,
2025 |
|
June 30,
2025 |
| Select Balance Sheet: |
|
|
|
|
|
|
|
|
|
| Total assets |
$ |
8,430,566 |
|
|
$ |
8,498,404 |
|
|
$ |
6,967,350 |
|
|
$ |
7,011,879 |
|
|
$ |
7,070,641 |
|
Loans receivable |
5,747,741 |
|
|
5,722,238 |
|
|
4,783,266 |
|
|
4,769,160 |
|
|
4,774,855 |
|
| Total investment securities |
1,633,276 |
|
|
1,669,411 |
|
|
1,281,629 |
|
|
1,312,857 |
|
|
1,346,274 |
|
| Total deposits |
7,038,706 |
|
|
7,248,537 |
|
|
5,920,199 |
|
|
5,857,464 |
|
|
5,784,413 |
|
| Noninterest demand deposits |
1,972,702 |
|
|
2,066,383 |
|
|
1,597,650 |
|
|
1,617,909 |
|
|
1,584,231 |
|
| Stockholders' equity |
1,109,692 |
|
|
1,115,691 |
|
|
921,504 |
|
|
904,064 |
|
|
888,212 |
|
| Financial Measures: |
|
|
|
|
|
|
|
|
|
| Book value per share |
$ |
27.13 |
|
|
$ |
27.05 |
|
|
$ |
27.13 |
|
|
$ |
26.62 |
|
|
$ |
26.16 |
|
Tangible book value per share (1)
|
19.15 |
|
|
19.07 |
|
|
19.98 |
|
|
19.46 |
|
|
18.99 |
|
| Stockholders' equity to total assets |
13.2 |
% |
|
13.1 |
% |
|
13.2 |
% |
|
12.9 |
% |
|
12.6 |
% |
Tangible common equity to tangible assets (1)
|
9.7 |
|
|
9.6 |
|
|
10.1 |
|
|
9.8 |
|
|
9.4 |
|
| Loans to deposits ratio |
81.7 |
|
|
78.9 |
|
|
80.8 |
|
|
81.4 |
|
|
82.5 |
|
Regulatory Capital Ratios:(2)
|
|
|
|
|
|
|
|
|
|
Common equity tier 1 capital ratio |
12.1 |
% |
|
12.2 |
% |
|
12.7 |
% |
|
12.4 |
% |
|
12.2 |
% |
Leverage ratio |
10.4 |
|
|
10.3 |
|
|
10.8 |
|
|
10.5 |
|
|
10.3 |
|
Tier 1 capital ratio |
12.5 |
|
|
12.5 |
|
|
13.1 |
|
|
12.8 |
|
|
12.6 |
|
Total capital ratio |
13.4 |
|
|
13.5 |
|
|
14.1 |
|
|
13.8 |
|
|
13.6 |
|
| Credit Quality Metrics: |
|
|
|
|
|
|
|
|
|
ACL on loans to:
|
|
|
|
|
|
|
|
|
|
| Loans receivable |
1.03 |
% |
|
1.06 |
% |
|
1.10 |
% |
|
1.13 |
% |
|
1.10 |
% |
Nonaccrual loans |
383.4 |
|
|
404.8 |
|
|
250.7 |
|
|
306.5 |
|
|
532.5 |
|
Nonaccrual loans to loans receivable |
0.27 |
|
|
0.26 |
|
|
0.44 |
|
|
0.37 |
|
|
0.21 |
|
| Nonperforming loans to loans receivable |
0.27 |
|
|
0.26 |
|
|
0.44 |
|
|
0.44 |
|
|
0.39 |
|
| Nonperforming assets to total assets |
0.19 |
|
|
0.19 |
|
|
0.30 |
|
|
0.30 |
|
|
0.26 |
|
Net charge-offs on loans to average loans receivable (3)
|
0.02 |
|
|
0.04 |
|
|
0.04 |
|
|
0.01 |
|
|
0.04 |
|
| Criticized Loans by Credit Quality Rating: |
| Special mention |
$ |
125,108 |
|
|
$ |
103,699 |
|
|
$ |
71,122 |
|
|
$ |
100,160 |
|
|
$ |
114,146 |
|
| Substandard |
105,444 |
|
|
121,331 |
|
|
116,823 |
|
|
94,377 |
|
|
99,715 |
|
| Other Metrics: |
|
|
|
|
|
|
|
|
|
| Number of branches |
66 |
|
|
65 |
|
|
50 |
|
|
50 |
|
|
50 |
|
| Deposits per branch |
$ |
106,647 |
|
|
$ |
111,516 |
|
|
$ |
118,404 |
|
|
$ |
117,149 |
|
|
$ |
115,688 |
|
| Average number of full-time equivalent employees |
976 |
|
|
905 |
|
|
742 |
|
|
749 |
|
|
745 |
|
| Average assets per full-time equivalent employee |
8,645 |
|
|
8,768 |
|
|
9,372 |
|
|
9,354 |
|
|
9,459 |
|
(1) See Non-GAAP Financial Measures section herein.
(2) Current quarter ratios are estimates pending completion and filing of the Company’s regulatory reports.
(3) Annualized.
HERITAGE FINANCIAL CORPORATION
NON-GAAP FINANCIAL MEASURES (Unaudited)
(Dollars in thousands, except per share amounts)
This earnings release contains certain financial measures not presented in accordance with U.S. Generally Accepted Accounting Principles ("GAAP") in addition to financial measures presented in accordance with GAAP. The Company has presented these non-GAAP financial measures in this earnings release because it believes that they provide useful and comparative information to assess trends in the Company’s capital, performance and asset quality reflected in the current quarter and comparable period results and to facilitate comparison of its performance with the performance of its peers. These non-GAAP financial measures have inherent limitations, are not required to be uniformly applied and are not audited. They should not be considered in isolation or as a substitute for financial measures presented in accordance with GAAP. These non-GAAP financial measures may not be comparable to similarly titled measures reported by other companies. Reconciliations of the non-GAAP financial measures used in this earnings release to the comparable GAAP financial measures are presented below.
The Company believes that presenting the adjusted diluted earnings per share provides useful and comparative information to assess trends in the Company's core operations reflected in the current quarter’s results and facilitate the comparison of our performance with the performance of our peers.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
June 30,
2026 |
|
March 31,
2026 |
|
December 31,
2025 |
|
September 30,
2025 |
|
June 30,
2025 |
Diluted Earnings per Share and Adjusted Diluted Earnings per Share: |
| Net income (GAAP) |
$ |
17,546 |
|
|
$ |
18,947 |
|
|
$ |
22,237 |
|
|
$ |
19,169 |
|
|
$ |
12,215 |
|
Exclude loss on sale of investment securities, net |
217 |
|
|
— |
|
|
— |
|
|
— |
|
|
6,854 |
|
|
|
|
|
|
|
|
|
|
|
| Exclude merger related costs |
7,493 |
|
|
5,178 |
|
|
385 |
|
|
635 |
|
|
— |
|
| Exclude gain on sale of premises and equipment |
— |
|
|
— |
|
|
— |
|
|
— |
|
|
(5) |
|
| Exclude tax effect of adjustment |
(1,619) |
|
|
(1,087) |
|
|
(81) |
|
|
(133) |
|
|
(1,438) |
|
|
|
|
|
|
|
|
|
|
|
| Exclude tax expense related to BOLI restructuring |
— |
|
|
— |
|
|
— |
|
|
— |
|
|
515 |
|
Adjusted net income (non-GAAP) |
$ |
23,637 |
|
|
$ |
23,038 |
|
|
$ |
22,541 |
|
|
$ |
19,671 |
|
|
$ |
18,141 |
|
|
|
|
|
|
|
|
|
|
|
| Average number of diluted shares outstanding |
41,541,763 |
|
|
39,104,569 |
|
|
34,405,793 |
|
|
34,413,386 |
|
|
34,446,710 |
|
|
|
|
|
|
|
|
|
|
|
| Diluted earnings per share (GAAP) |
$ |
0.42 |
|
|
$ |
0.48 |
|
|
$ |
0.65 |
|
|
$ |
0.55 |
|
|
$ |
0.36 |
|
| Adjusted diluted earnings per share (non-GAAP) |
$ |
0.57 |
|
|
$ |
0.59 |
|
|
$ |
0.66 |
|
|
$ |
0.56 |
|
|
$ |
0.53 |
|
HERITAGE FINANCIAL CORPORATION
NON-GAAP FINANCIAL MEASURES (Unaudited)
(Dollars in thousands, except per share amounts)
The Company believes that presenting an adjusted return on average assets ratio provides useful and comparative information to assess trends in the Company's core operations reflected in the current quarter’s results and facilitate the comparison of our performance with the performance of our peers.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
June 30,
2026 |
|
March 31,
2026 |
|
December 31,
2025 |
|
September 30,
2025 |
|
June 30,
2025 |
| Adjusted Return on Average Assets ("ROAA"): |
| Net income (GAAP) |
$ |
17,546 |
|
|
$ |
18,947 |
|
|
$ |
22,237 |
|
|
$ |
19,169 |
|
|
$ |
12,215 |
|
| Exclude (gain) loss on sale of investment securities, net |
217 |
|
|
— |
|
|
— |
|
|
— |
|
|
6,854 |
|
|
|
|
|
|
|
|
|
|
|
| Exclude merger related costs |
7,493 |
|
|
5,178 |
|
|
385 |
|
|
635 |
|
|
— |
|
| Exclude gain on sale of premise and equipment |
— |
|
|
— |
|
|
— |
|
|
— |
|
|
(5) |
|
| Exclude tax effect of adjustments |
(1,619) |
|
|
(1,087) |
|
|
(81) |
|
|
(133) |
|
|
(1,438) |
|
|
|
|
|
|
|
|
|
|
|
| Exclude tax expense related to BOLI restructuring |
— |
|
|
— |
|
|
— |
|
|
— |
|
|
515 |
|
| Adjusted net income (non-GAAP) |
$ |
23,637 |
|
|
$ |
23,038 |
|
|
$ |
22,541 |
|
|
$ |
19,671 |
|
|
$ |
18,141 |
|
|
|
|
|
|
|
|
|
|
|
| Average ("Avg") total assets |
$ |
8,437,320 |
|
|
$ |
7,935,002 |
|
|
$ |
6,954,110 |
|
|
$ |
7,006,140 |
|
|
$ |
7,046,943 |
|
|
|
|
|
|
|
|
|
|
|
| ROAA, annualized (GAAP) |
0.83% |
|
0.97% |
|
1.27% |
|
1.09% |
|
0.70% |
| Adjusted ROAA, annualized (non-GAAP) |
1.12% |
|
1.18% |
|
1.29% |
|
1.11% |
|
1.03% |
HERITAGE FINANCIAL CORPORATION
NON-GAAP FINANCIAL MEASURES (Unaudited)
(Dollars in thousands, except per share amounts)
The Company considers the tangible common equity to tangible assets ratio and tangible book value per share to be useful measurements of the adequacy of the Company’s capital levels.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
June 30,
2026 |
|
March 31,
2026 |
|
December 31,
2025 |
|
September 30,
2025 |
|
June 30,
2025 |
| Tangible Common Equity to Tangible Assets and Tangible Book Value Per Share: |
| Total stockholders' equity (GAAP) |
$ |
1,109,692 |
|
|
$ |
1,115,691 |
|
|
$ |
921,504 |
|
|
$ |
904,064 |
|
|
$ |
888,212 |
|
| Exclude intangible assets |
(326,298) |
|
|
(329,255) |
|
|
(242,918) |
|
|
(243,203) |
|
|
(243,487) |
|
| Tangible common equity (non-GAAP) |
$ |
783,394 |
|
|
$ |
786,436 |
|
|
$ |
678,586 |
|
|
$ |
660,861 |
|
|
$ |
644,725 |
|
|
|
|
|
|
|
|
|
|
|
| Total assets (GAAP) |
$ |
8,430,566 |
|
|
$ |
8,498,404 |
|
|
$ |
6,967,350 |
|
|
$ |
7,011,879 |
|
|
$ |
7,070,641 |
|
| Exclude intangible assets |
(326,298) |
|
|
(329,255) |
|
|
(242,918) |
|
|
(243,203) |
|
|
(243,487) |
|
| Tangible assets (non-GAAP) |
$ |
8,104,268 |
|
|
$ |
8,169,149 |
|
|
$ |
6,724,432 |
|
|
$ |
6,768,676 |
|
|
$ |
6,827,154 |
|
|
|
|
|
|
|
|
|
|
|
| Stockholders' equity to total assets (GAAP) |
13.2 |
% |
|
13.1 |
% |
|
13.2 |
% |
|
12.9 |
% |
|
12.6 |
% |
Tangible common equity to tangible assets (non-GAAP) |
9.7 |
% |
|
9.6 |
% |
|
10.1 |
% |
|
9.8 |
% |
|
9.4 |
% |
|
|
|
|
|
|
|
|
|
|
| Shares outstanding |
40,906,122 |
|
|
41,249,873 |
|
|
33,963,500 |
|
|
33,956,738 |
|
|
33,953,194 |
|
|
|
|
|
|
|
|
|
|
|
| Book value per share (GAAP) |
$ |
27.13 |
|
|
$ |
27.05 |
|
|
$ |
27.13 |
|
|
$ |
26.62 |
|
|
$ |
26.16 |
|
| Tangible book value per share (non-GAAP) |
$ |
19.15 |
|
|
$ |
19.07 |
|
|
$ |
19.98 |
|
|
$ |
19.46 |
|
|
$ |
18.99 |
|
HERITAGE FINANCIAL CORPORATION
NON-GAAP FINANCIAL MEASURES (Unaudited)
(Dollars in thousands, except per share amounts)
The Company considers the return on average tangible common equity ratio to be a useful measurement of the Company’s ability to generate returns for its common shareholders. By removing the impact of intangible assets and their related amortization and tax effects, the performance of the Company's ongoing business operations can be evaluated. The Company believes that presenting an adjusted return on tangible common equity ratio provides useful and comparative information to assess trends in the Company's core operations reflected in the current quarter’s results and facilitate the comparison of our performance with the performance of our peers.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Quarter Ended |
|
June 30,
2026 |
|
March 31,
2026 |
|
December 31,
2025 |
|
September 30,
2025 |
|
June 30,
2025 |
| Return on Average Tangible Common Equity, annualized: |
| Net income (GAAP) |
$ |
17,546 |
|
|
$ |
18,947 |
|
|
$ |
22,237 |
|
|
$ |
19,169 |
|
|
$ |
12,215 |
|
| Add amortization of intangible assets |
2,957 |
|
|
2,058 |
|
|
285 |
|
|
284 |
|
|
302 |
|
| Exclude tax effect of adjustment |
(621) |
|
|
(432) |
|
|
(60) |
|
|
(60) |
|
|
(63) |
|
| Tangible net income (non-GAAP) |
$ |
19,882 |
|
|
$ |
20,573 |
|
|
$ |
22,462 |
|
|
$ |
19,393 |
|
|
$ |
12,454 |
|
|
|
|
|
|
|
|
|
|
|
| Tangible net income (non-GAAP) |
$ |
19,882 |
|
|
$ |
20,573 |
|
|
$ |
22,462 |
|
|
$ |
19,393 |
|
|
$ |
12,454 |
|
Exclude loss on sale of investment securities, net |
217 |
|
|
— |
|
|
— |
|
|
— |
|
|
6,854 |
|
|
|
|
|
|
|
|
|
|
|
| Exclude merger related costs |
7,493 |
|
|
5,178 |
|
|
385 |
|
|
635 |
|
|
— |
|
| Exclude gain on sale of premises and equipment |
— |
|
|
— |
|
|
— |
|
|
— |
|
|
(5) |
|
| Exclude tax effect of adjustment |
(1,619) |
|
|
(1,087) |
|
|
(81) |
|
|
(133) |
|
|
(1,438) |
|
|
|
|
|
|
|
|
|
|
|
| Exclude tax expense related to BOLI restructuring |
— |
|
|
— |
|
|
— |
|
|
— |
|
|
515 |
|
| Adjusted tangible net income (non-GAAP) |
$ |
25,973 |
|
|
$ |
24,664 |
|
|
$ |
22,766 |
|
|
$ |
19,895 |
|
|
$ |
18,380 |
|
|
|
|
|
|
|
|
|
|
|
| Average stockholders' equity (GAAP) |
$ |
1,112,178 |
|
|
$ |
1,049,044 |
|
|
$ |
911,454 |
|
|
$ |
892,280 |
|
|
$ |
879,808 |
|
| Exclude average intangible assets |
(328,166) |
|
|
(300,391) |
|
|
(243,069) |
|
|
(243,350) |
|
|
(243,651) |
|
| Average tangible common stockholders' equity (non-GAAP) |
$ |
784,012 |
|
|
$ |
748,653 |
|
|
$ |
668,385 |
|
|
$ |
648,930 |
|
|
$ |
636,157 |
|
|
|
|
|
|
|
|
|
|
|
| Return on average common equity, annualized (GAAP) |
6.33 |
% |
|
7.32 |
% |
|
9.68 |
% |
|
8.52 |
% |
|
5.57 |
% |
| Return on average tangible common equity, annualized (non-GAAP) |
10.17 |
% |
|
11.14 |
% |
|
13.33 |
% |
|
11.86 |
% |
|
7.85 |
% |
| Adjusted return on average tangible common equity, annualized (non-GAAP) |
13.29 |
% |
|
13.36 |
% |
|
13.51 |
% |
|
12.16 |
% |
|
11.59 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
HERITAGE FINANCIAL CORPORATION
NON-GAAP FINANCIAL MEASURES (Unaudited)
(Dollars in thousands, except per share amounts)
The Company believes that presenting an adjusted efficiency ratio and adjusted noninterest expense to average assets ratio provides useful and comparative information to assess trends in the Company's core operations reflected in the current quarter’s results and facilitate the comparison of our performance with the performance of our peers.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Quarter Ended |
|
June 30,
2026 |
|
March 31,
2026 |
|
December 31,
2025 |
|
September 30,
2025 |
|
June 30,
2025 |
Adjusted Efficiency Ratio and Adjusted Noninterest Expense to Average Assets Ratio: |
| Total noninterest expense (GAAP) |
$ |
64,324 |
|
|
$ |
56,551 |
|
|
$ |
41,483 |
|
|
$ |
41,615 |
|
|
$ |
41,085 |
|
| Exclude merger related costs |
7,493 |
|
|
5,178 |
|
|
385 |
|
|
635 |
|
|
— |
|
| Exclude amortization of intangible assets |
2,957 |
|
|
2,058 |
|
|
285 |
|
|
284 |
|
|
302 |
|
| Adjusted noninterest expense (non-GAAP) |
$ |
53,874 |
|
|
$ |
49,315 |
|
|
$ |
40,813 |
|
|
$ |
40,696 |
|
|
$ |
40,783 |
|
|
|
|
|
|
|
|
|
|
|
| Net interest income (GAAP) |
$ |
74,816 |
|
|
$ |
69,219 |
|
|
$ |
58,361 |
|
|
$ |
57,371 |
|
|
$ |
54,983 |
|
|
|
|
|
|
|
|
|
|
|
| Total noninterest income (GAAP) |
$ |
9,311 |
|
|
$ |
8,699 |
|
|
$ |
7,987 |
|
|
$ |
8,325 |
|
|
$ |
1,517 |
|
Exclude loss on sale of investment securities, net |
217 |
|
|
— |
|
|
— |
|
|
— |
|
|
6,854 |
|
|
|
|
|
|
|
|
|
|
|
Exclude gain on sale of premises and equipment |
— |
|
|
— |
|
|
— |
|
|
— |
|
|
(5) |
|
|
|
|
|
|
|
|
|
|
|
| Adjusted total noninterest income (non-GAAP) |
$ |
9,528 |
|
|
$ |
8,699 |
|
|
$ |
7,987 |
|
|
$ |
8,325 |
|
|
$ |
8,366 |
|
|
|
|
|
|
|
|
|
|
|
| Efficiency ratio (GAAP) |
76.5 |
% |
|
72.6 |
% |
|
62.5 |
% |
|
63.3 |
% |
|
72.7 |
% |
| Adjusted efficiency ratio (non-GAAP) |
63.9 |
% |
|
63.3 |
% |
|
61.5 |
% |
|
61.9 |
% |
|
64.4 |
% |
|
|
|
|
|
|
|
|
|
|
| Average Total assets |
$ |
8,437,320 |
|
|
$ |
7,935,002 |
|
|
$ |
6,954,110 |
|
|
$ |
7,006,140 |
|
|
$ |
7,046,943 |
|
|
|
|
|
|
|
|
|
|
|
Noninterest expense to average assets (GAAP) (1)
|
3.06 |
% |
|
2.89 |
% |
|
2.37 |
% |
|
2.36 |
% |
|
2.34 |
% |
Adjusted noninterest expense to average assets (non-GAAP) (1)
|
2.56 |
% |
|
2.52 |
% |
|
2.33 |
% |
|
2.30 |
% |
|
2.32 |
% |
(1) Annualized.
HERITAGE FINANCIAL CORPORATION
NON-GAAP FINANCIAL MEASURES (Unaudited)
(Dollars in thousands, except per share amounts)
The Company believes presenting loan yield and net interest margin excluding the effect of discount accretion on purchased loans is useful in assessing the impact of acquisition accounting on loan yield as the effect of loan discount accretion is expected to decrease as the acquired loans mature or roll off our balance sheet.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
Three Months Ended |
|
|
| |
June 30,
2026 |
|
March 31,
2026 |
|
June 30,
2025 |
|
|
|
|
|
(Dollar amounts in thousands) |
| Loan yield, excluding incremental accretion on purchased loans, annualized: |
| Interest and fees on loans (GAAP) |
$ |
81,935 |
|
|
$ |
76,445 |
|
|
$ |
65,373 |
|
|
|
|
|
| Exclude incremental accretion on purchased loans |
1,772 |
|
|
1,623 |
|
|
76 |
|
|
|
|
|
| Adjusted interest and fees on loans (non-GAAP) |
$ |
80,163 |
|
|
$ |
74,822 |
|
|
$ |
65,297 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average loans receivable, net (GAAP) |
$ |
5,740,927 |
|
|
$ |
5,412,943 |
|
|
$ |
4,768,558 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Loan yield, annualized (GAAP) |
5.72 |
% |
|
5.73 |
% |
|
5.50 |
% |
|
|
|
|
Loan yield, excluding incremental accretion on purchased loans, annualized (non-GAAP) |
5.60 |
% |
|
5.61 |
% |
|
5.49 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net Interest Margin, excluding incremental accretion on purchased loans, annualized: |
|
|
|
|
| Net interest income before provision (GAAP) |
$ |
74,816 |
|
|
$ |
69,219 |
|
|
$ |
54,983 |
|
|
|
|
|
| Exclude incremental accretion on purchased loans |
1,772 |
|
|
1,623 |
|
|
76 |
|
|
|
|
|
| Adjusted net interest income before provision (non-GAAP) |
$ |
73,044 |
|
|
$ |
67,596 |
|
|
$ |
54,907 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average Interest earning assets (GAAP) |
$ |
7,517,314 |
|
|
$ |
7,087,671 |
|
|
$ |
6,286,309 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net interest margin (GAAP) |
3.99 |
% |
|
3.96 |
% |
|
3.51 |
% |
|
|
|
|
| Net interest margin, excluding incremental accretion on purchased loans (non-GAAP) |
3.90 |
% |
|
3.87 |
% |
|
3.50 |
% |
|
|
|
|
 エドガーで原本を確認する